Recycled Plastics Market
Global Industry analysis, Size, Share, Growth, Trends, and Forecast 2026-2031
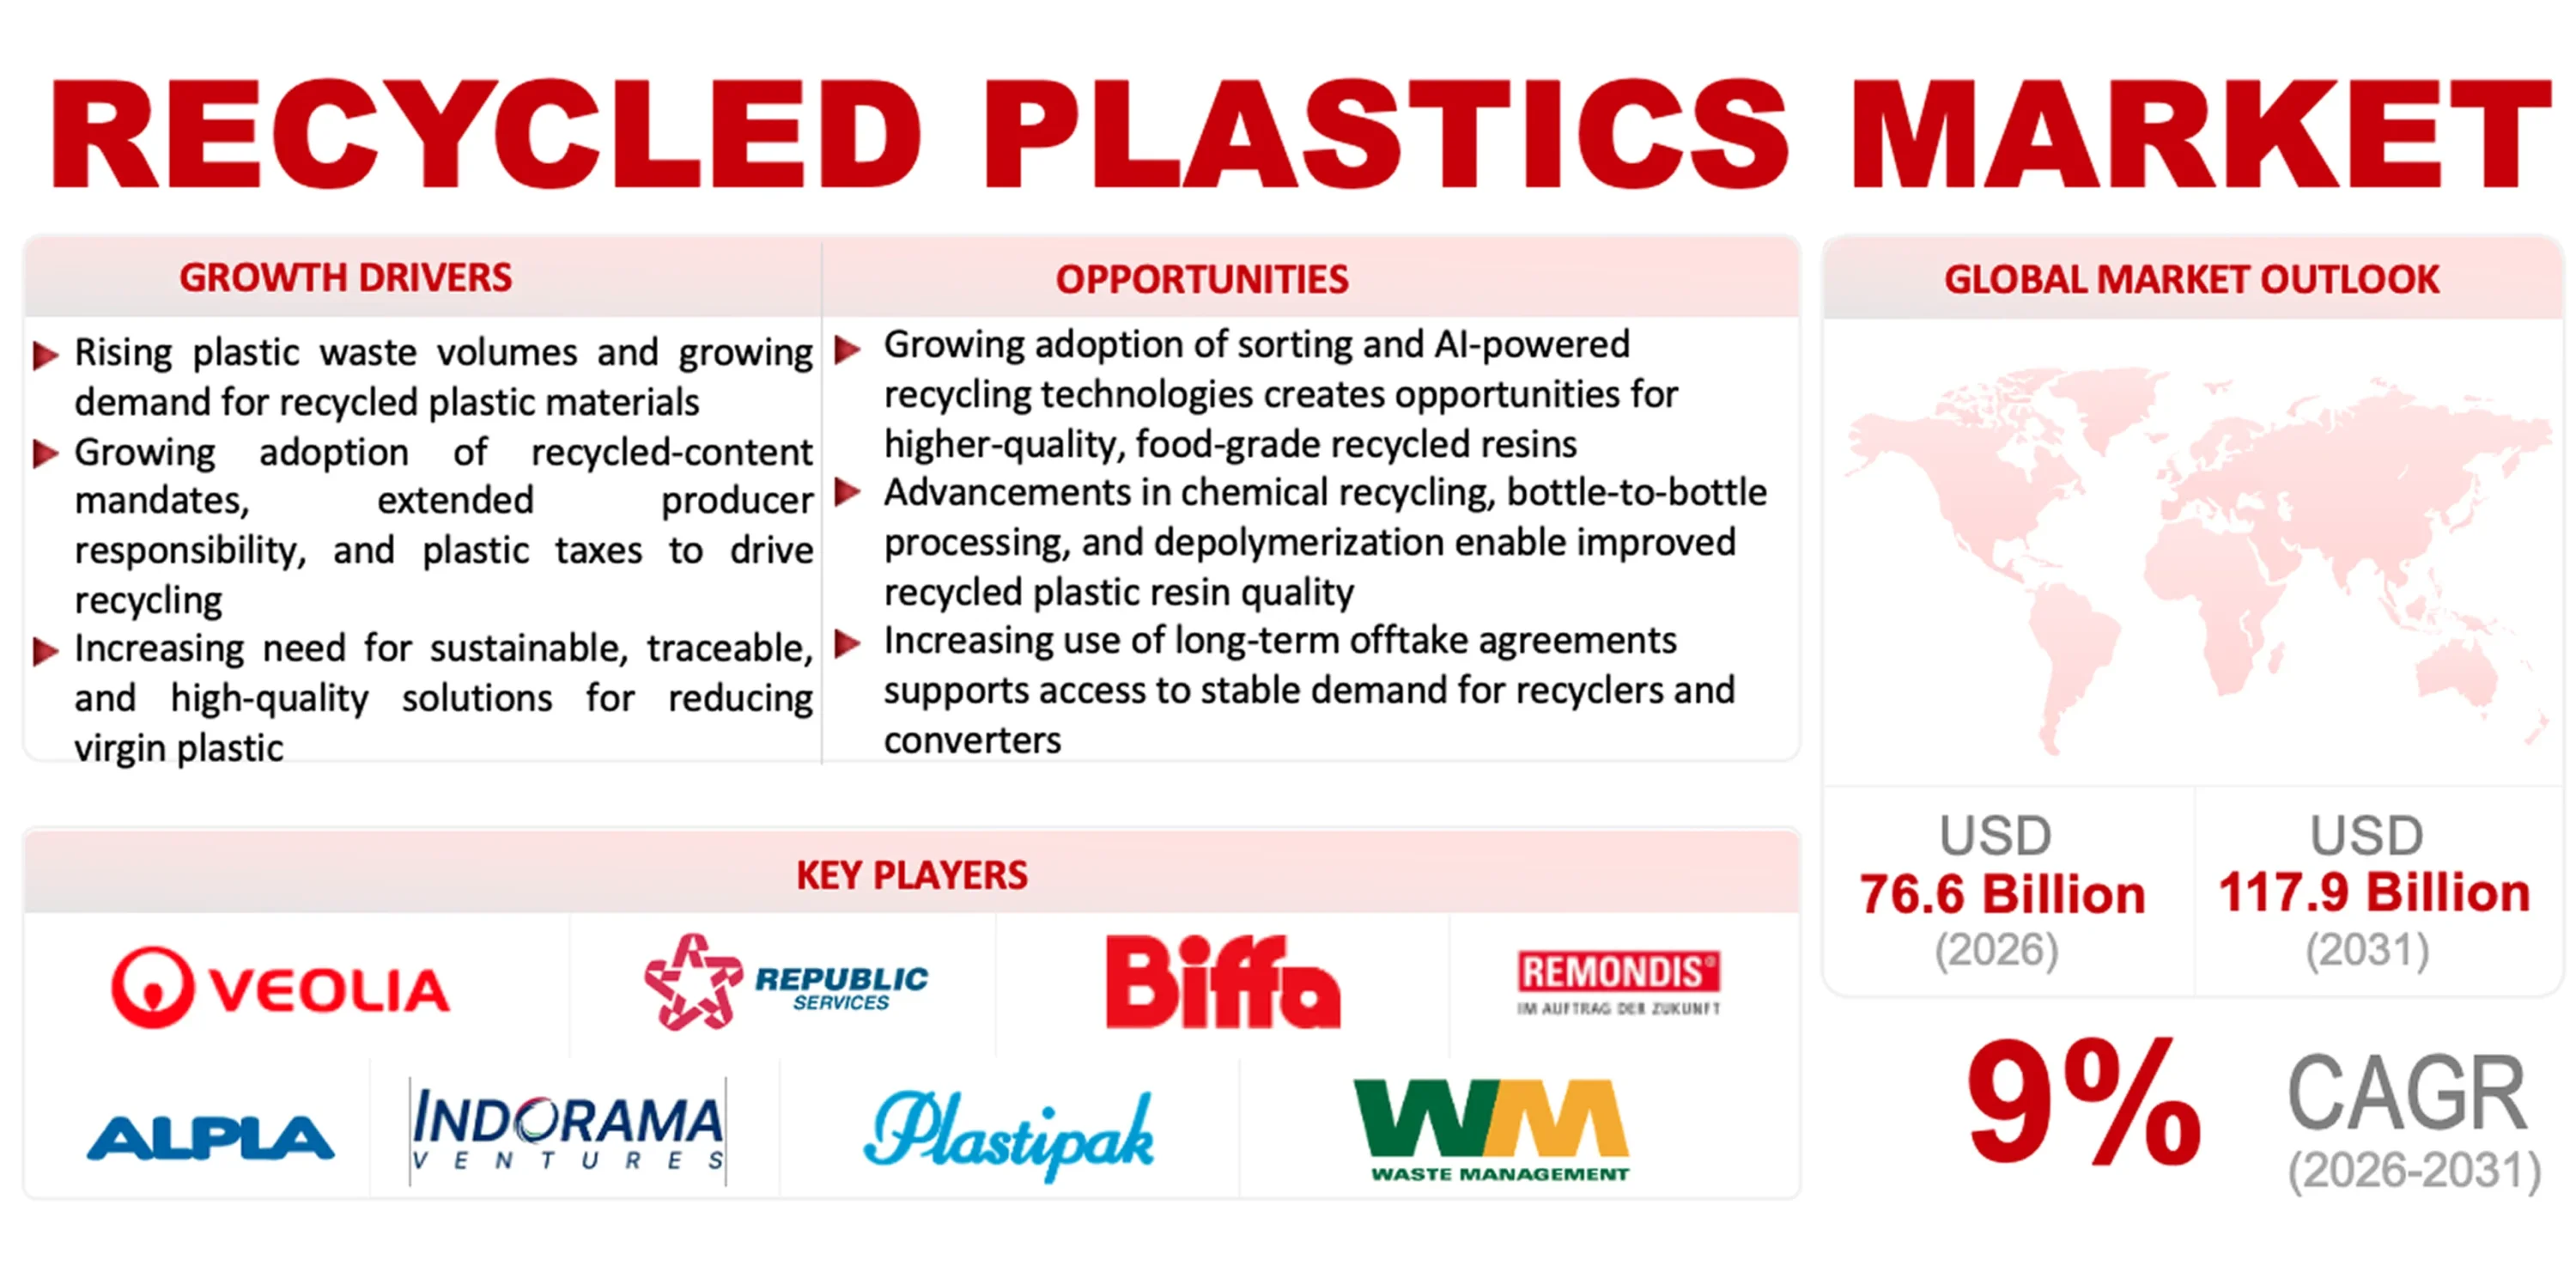
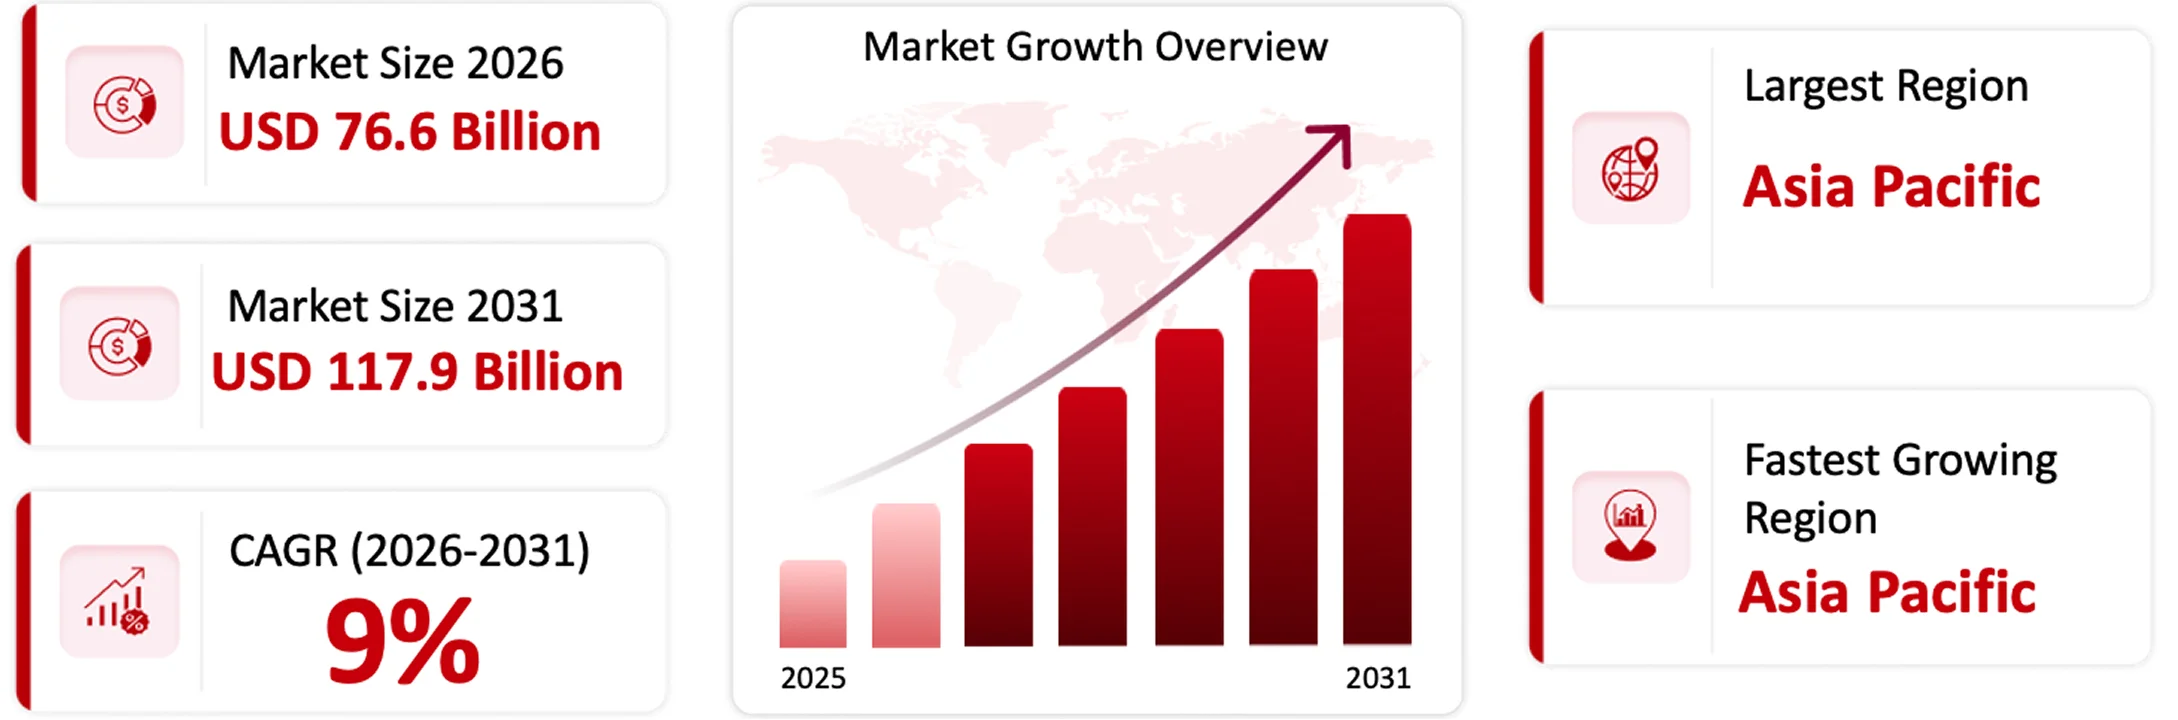
The global recycled plastics market is projected to reach USD 117.9 billion by 2031, growing at a CAGR of 9% during the forecast period.
| Market Size (2026): | Forecast (2031): | CAGR (2026–2031): | Leading Region: |
|---|---|---|---|
| $ 76.6 Billion | $ 117.9 Billion | 9 % | Asia Pacific |
Summarize this report with:


Market Overview
“In my view, the emergence of the recycled plastic industry corresponds to the increasing strides made in curtailing plastic waste and recycling, as well as improving resource efficiency and circular economy processes. Recycled plastics refer to a range of materials obtained from post-consumer or post-industrial plastic waste and reprocessed into raw materials suitable for use in manufacturing. Some of the main types of recycled plastics include polyethylene terephthalate (rPET), high-density polyethylene (rHDPE), low-density polyethylene (rLDPE), polypropylene (rPP), polystyrene (rPS), and recycled polyvinyl chloride (rPVC). These materials can be obtained via several recycling methods such as mechanical recycling, chemical recycling, and other recovery methods. Recycled plastics find application in various industries including packaging, automotive, construction, electrical and electronics, textile, consumer goods, and other industrial applications. The rising volume of plastic waste, government requirements, business sustainability objectives, and the need for recycled material have acted as catalysts for the growth of the market. The expansion of the market also depends on various issues, such as the waste collection infrastructure in place, efficiency in sorting, recycling capacity, material quality, and economics of recycling versus virgin products.”
– Mayur Jain, Research Consultant, Wissen Research
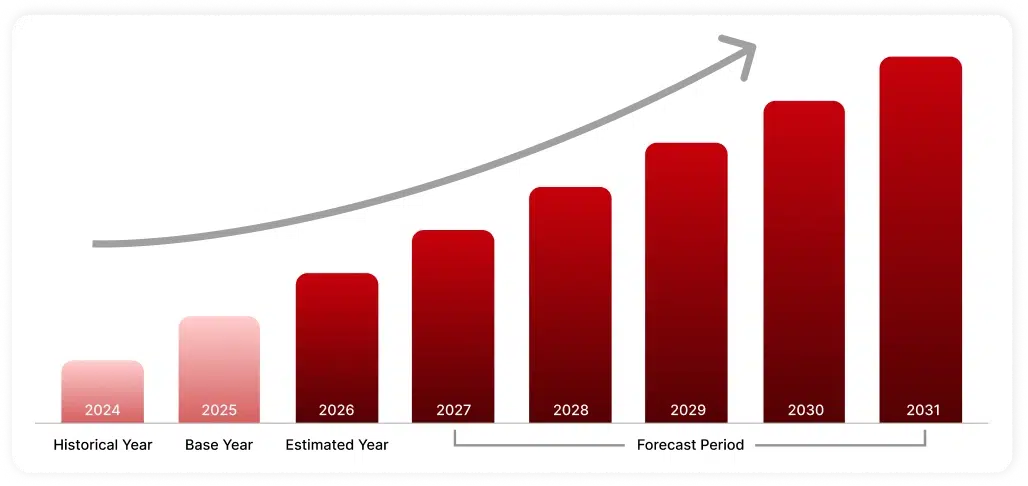
The market is estimated to be USD 76.6 billion in 2026 and is projected to reach USD 117.9 billion by 2031, growing at a CAGR of 9 % during the forecast period (2026-2031).
Technology Overview
The process of producing recycled plastics involves the collection of waste, its sorting into different categories, the cleaning of each category, and various techniques for decreasing the size of waste plastics and recovering plastics for reuse. The type of waste used depends on some factors, such as the type of polymers used, contamination level, availability of waste, requirements for the end-users, and quality standards set by customers. Some methods used in recycling plastics are chemical recycling, mechanical recycling, and advanced sorting technologies. Mechanical recycling consists of collecting, shredding, cleaning/recycling, melting, and creating plastic pellets. On the other hand, chemical recycling uses depolymerization or pyrolysis to retrieve chemical compounds from plastic waste. Division of polymers is achieved due to optical and automatic separation technologies. There is an increase in quality of plastic recovery technology due to improvements in washing, filtration, and decontamination technologies as well as in energy efficiency. Recycling technology is used in packaging and other applications.
Key Growth Drivers
- Increasing plastic waste generation is expanding the availability of recyclable feedstock, encouraging investment in collection, sorting, processing, and material recovery infrastructure across municipal and industrial waste streams.
- Growing environmental awareness is encouraging manufacturers and consumers to support products incorporating recycled plastics, particularly as businesses seek to reduce waste generation and improve resource efficiency.
- Stricter regulations and recycled-content requirements are encouraging manufacturers to incorporate recycled polymers into packaging, automotive components, construction materials, and other plastic-intensive applications.
- Advancements in recycling and sorting technologies are improving polymer separation, contamination removal, processing efficiency, and the quality of recycled materials, supporting broader adoption across end-use industries.
- Increasing corporate sustainability commitments are encouraging companies to establish recycled-content targets, develop circular material strategies, and collaborate with recycling suppliers to improve material traceability and supply availability.
- Growing demand for sustainable packaging and recycled polymer feedstocks is encouraging investment in recycling capacity, product development, and partnerships between waste collectors, recyclers, resin producers, and consumer goods manufacturers.• Growing demand for sustainable packaging and recycled polymer feedstocks is encouraging investment in recycling capacity, product development, and partnerships between waste collectors, recyclers, resin producers, and consumer goods manufacturers.
Recycled Plastics Market Key Highlights
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
Recycled Plastics Market Trends
The recycled plastics sector is showing the trend of evolution from classic waste collection procedures to superior quality of recycling products, unique processing technologies and integrated circular supply chains. The processes in the industry underline successes in polymer sorting, contamination control, tracking of raw materials and keeping the quality of the final product. The importance of recycled PET and recycled PE should be emphasized in the processes related to production of the recycled products, while the role of recycled PP can be considered less significant but still promising. Even though the role of mechanical recycling continues to be unchangeable, the interest in chemical recycling is also rising due to its potential application for some waste streams that cannot be processed through the conventional recycling techniques. The adherence to recycled content goals, sustainable packaging activities and extended producer responsibility systems has also played an important role in the evolution of the market.
Increasing Investment in Chemical Recycling and Advanced Recycling Technologies
- Rising investment in chemical and advanced recycling: Fraunhofer UMSICHT (German Research Institute) identified 65 chemical recycling projects in Europe, representing approximately 2.8 million tonnes/year of announced or under-construction capacity. Pyrolysis dominates the pipeline, with 1.68 million tonnes/year planned. The European plastics industry plans to invest up to €8 billion in chemical recycling, according to the European Commission.
- Major players are expanding recycling capacity: ExxonMobil is investing over $200 million to add 350 million lb/year of advanced recycling capacity, taking its total to 500 million lb/year. Carbios and Wankai are developing a €115 million PET biorecycling plant in China with 50,000 tonnes/year of capacity, while SK Chemicals is investing approximately US$100 million in a 70,000-tonne/year chemical PET plant.
- Advanced sorting technologies are supporting recycling efficiency: Republic Services Indianapolis facility uses 22 optical sorters to improve feedstock purity, highlighting parallel investment in sorting infrastructure to improve the quality of materials entering recycling processes.
- Regulatory clarity and commercial viability remain critical: In December 2025, the European Commission proposed mass-balance allocation rules to determine how chemical recycling outputs can count toward recycled-content targets. High capital costs, feedstock availability, and uncertainty regarding demand and pricing for recycled outputs continue to influence project execution and investment decisions.
Growing Demand for Recycled Plastics and Rising Recycled-Content Requirements
- Regulatory mandates are accelerating recycled-plastic demand: The EU Packaging and Packaging Waste Regulation (PPWR), applying from 12 August 2026, sets minimum recycled-content targets from 2030, including 30% for single-use plastic beverage bottles and 35% for other plastic packaging, rising to 65% for both by 2040. India requires 30% recycled content in rigid packaging in 2025–26, increasing to 60% by 2028–29, while flexible packaging targets rise from 10% to 20%.
- Supply shortages are creating a gap between demand and available capacity: Republic Services estimates that U.S. rPET demand will reach 5 billion lb by 2030, compared with current supply capacity of only 2.5 billion lb. In Europe, Plastics Recyclers Europe estimates that 16 million tonnes of installed recycling capacity are needed to meet recycled-content targets, against approximately 13.2 million tonnes currently available.
- Brand-owner commitments are supporting recycled-content adoption: Coca-Cola increased its recycled PET use by 50% between 2020 and 2024, while signatories to the Ellen MacArthur Foundation’s Global Commitment have tripled their use of recycled content, demonstrating growing industry adoption beyond regulatory requirements.
- Price premiums and weaker voluntary commitments are limiting demand growth: In mid-2025, virgin PET traded at approximately €1,000/tonne, compared with up to €1,800/tonne for rPET, prompting some European bottlers to revert to the 25% legal minimum. Coca-Cola reduced its recycled-content target from 50% by 2030 to 35–40% by 2035, while PepsiCo revised its target from 50% by 2030 to 40% by 2035.
- Feedstock constraints and market integrity remain critical challenges: The European Commission expects a net decrease of approximately one million tonnes in recycling capacity by the end of 2025 and has highlighted concerns about virgin plastics imported and mislabelled as recycled. Regulatory mandates establish baseline demand, but further market growth depends on narrowing the price gap, expanding reliable recycling capacity, and securing consistent feedstock supplies.
Key Players in the Recycled Plastics Market
Leading companies in the recycled plastics market are focusing on recycling capacity, advanced processing technologies, recycled resin quality, supply-chain partnerships, and expansion across packaging, automotive, construction, and consumer goods applications.
Strategic Activities Within the Recycled Plastics Market
Indorama Ventures Public Company Limited (Thailand), through PET Value Philippines, partnered with Republic Cement & Building Materials, Inc. to launch a Zero Waste to Landfill initiative. The partnership recycled post-consumer PET bottles into food-grade rPET and recovered caps and labels for co-processing as alternative fuel in cement manufacturing.
WM (Waste Management, Inc.) (U.S.) completed its Denver East recycling facility in Aurora, Colorado, in Q2 2026, adding approximately 60,000 tons of annual processing capacity. The USD 110 million facility featured an 84,000-square-foot recycling plant equipped with automated optical and AI-driven sorting technologies to improve material recovery and operational efficiency
Plastipak Packaging, Inc. (U.S.) introduced pakPET™ Single Pellet Solution, a PET resin combining virgin PET performance with 30% recycled content. Manufactured in Verbania, Italy, the solution supported food and beverage, pharmaceutical, personal care, and thermoformed packaging applications while simplifying processing and maintaining consistent quality.
Recycled Plastics Market Insights
The recycled plastic industry has emerged as a significant component of the plastic and waste management sector, meeting the demand for the retrieval of used plastic materials and for decreasing the reliance on virgin materials. Recycled plastics are materials that are obtained from plastic waste after consumption or from discarded plastic materials after industry use and treated for further application. The main groups of polymers are recycled polyethylene terephthalate (rPET), recycled high-density polyethylene (rHDPE), recycled low-density polyethylene (rLDPE), recycled polypropylene (rPP), recycled polystyrene (rPS), and recycled polyvinyl chloride (rPVC). The market growth is driven by the rise in the generation of plastic waste, the demand for recycled materials, the existence of laws and regulations, the demands for sustainability from companies, and the growth in recycling facilities.
Various industries utilize recycled plastics, including food packaging, building and construction, automotive, electrical and electronics, textile, agriculture, and consumer goods. Food packaging is a significant part of the application, as many plastic waste is generated by bottles, containers, films, and other packaging products that could enable the implementation of recycling principles. Recycled PET is suitable for specific applications such as bottles, sheets, films, and textiles, while recycled polyethylene and polypropylene are used to manufacture containers, pipes, basic household products, automotive parts, and industrial goods according to the specifications depending on the type of recycled materials used. While in construction industry recycled plastics are used in some pipes, profiles, panels, insulation materials, and composites. Recycled plastics, depending on specifications, are used in interior parts and undercarriages and other automotive elements by automotive manufacturers. Recycled plastics are also used in production of synthetic fibres for textiles as well as being utilized in production of agricultural films as well as in electrical equipment. Use of the applications depends on polymer composition, degree of contamination, mechanical properties, thermal stability, and regulatory requirements. For food applications, it is crucial to obey the rules concerning food-contact materials recycling.
The rising production of plastic waste is a significant driver for the development of the recycled plastics market because of the need for improved systems for collecting, sorting, and recovering plastic waste. Growing eco-consciousness and circular economy policies have pushed some companies to cut down their plastic waste production and use recycled content. Effectiveness of government regulations, which require companies to deal with their packaging waste and introduce extended producer responsibility rules, is another driving factor. Another driver is advancing recycling technologies, such as high-tech optical sorting technology and innovations in washing and filtering technology. Technology efficiency varies according to the recycled material. Growing corporate commitments to sustainability are pushing packaging producers and brand owners to set recycled content goals and secure long-term sources for original materials supply. Also, high demand for eco-friendly packaging solutions and materials, clothing fibres, and construction materials will create a demand for different applications. However, a number of factors will influence the actual application of the technology.
The recycled plastics industry is undergoing constant transformation in mechanical recycling, chemical recycling, automated sorting, and removal of contamination. The market is continuously evolving to achieve higher-quality recycled polymers able to fulfill higher production needs. While there is still significance of mechanical recycling concerning the clean waste of plastic material, chemical recycling attracts investments for the purification of certain plastic materials and types of waste that cannot be processed through conventional means. The demand for recycled materials in packaging is affecting the acquisition of the raw material, the expansion of recycling facilities, and has promoted more cooperation between waste management companies and producers. Nevertheless, there are still various factors inhibiting the development of the market, such as the quality of material being used, inefficiency of waste collection systems, contamination, losses in the process of recycling, high competition from cheap primary plastics, and other factors. The economy of recycling can be affected by energy expenditures, workforce expenses, transportation, and expenses for establishing recycling facilities. There is also a limitation on the number of plastics that can be processed repeatedly.
The Asia Pacific region has ample growth potential in the recycled plastics industry due to the extensive manufacturing capability in the region, rising plastic consumption needs, growing waste generation, and investing in recycling infrastructure. The countries of China, India, Japan, and South Korea form competitive plastics manufacturing and production sectors. The OECD estimates that plastic waste generation will experience substantial growth in developing countries in Asia over the years, signifying the need for enhanced waste collection systems and processing methods. Investments in sorting facilities, recycling facilities, waste recovery systems, and technologies for improving recycled materials can contribute to positive developments in the regional market.
Recycled Plastics Market Dynamics
Drivers: Increasing Plastic Waste Recovery and Demand for Recycled Materials
- Regulatory recycled-content requirements are creating measurable demand. The European Union’s Packaging and Packaging Waste Regulation (PPWR) establishes minimum post-consumer recycled-content targets from 2030, including 30% for single-use plastic beverage bottles and 35% for other plastic packaging, increasing to 65% for both by 2040.
- Corporate purchasing commitments are supporting demand for recycled polymers. The Ellen MacArthur Foundation’s November 2025 Global Commitment report covers companies representing approximately 20% of global plastic packaging production. Its signatories have tripled their use of recycled content, demonstrating adoption among major packaging users.
- Commercial demand is encouraging investment in additional recycling capacity. ExxonMobil announced an investment exceeding $200 million to add 350 million lb/year of advanced recycling capacity at its U.S. sites, increasing its total capacity to 500 million lb/year. The announcement illustrates the scale of industrial investment directed at recovering plastic waste for reuse as feedstock.
- New regulatory accounting rules are strengthening the framework for recycled-content compliance. In June 2026, the European Commission adopted updated rules for calculating, verifying and reporting recycled plastic in single-use beverage bottles, including provisions that allow additional recycling technologies to contribute under mass-balance accounting. These rules improve the framework for demonstrating compliance with recycled-content requirements.
Opportunities: Expansion of Advanced Recycling and High-Quality Recycled Polymer Applications
- Commercial-scale chemical recycling is opening new feedstock pathways. In March 2026, TotalEnergies (France) started production at its Grandpuits advanced plastics recycling plant, with annual capacity of 15,000 tonnes. The plant uses pyrolysis to process household plastic waste that is difficult to recycle mechanically, creating an additional route for recovering plastic feedstocks.
- Large-scale upgrading infrastructure can expand the supply of chemical recycling feedstocks. Neste Corporation (Finland) commissioned a €111 million upgrading facility at its Porvoo refinery in March 2026, with capacity to process up to 150,000 tonnes of liquefied waste plastic annually. The investment demonstrates industrial-scale development of infrastructure for converting waste-derived inputs into higher-quality petrochemical feedstocks.
- Regulatory clarification can unlock investment in advanced recycling. In December 2025, the European Commission identified planned industry investment of up to €8 billion in chemical recycling and proposed mass-balance allocation rules to establish how chemically recycled output can count toward recycled-content targets. Clearer accounting rules can improve investment certainty and support projects that complement mechanical recycling.
- Automotive and other industrial applications offer additional outlets for recycled polymers. In December 2025, the European Commission highlighted proposed recycled-plastic inclusion targets for new vehicles as a potential source of additional demand. Such requirements could create opportunities for suppliers of recycled polypropylene and other engineering polymers, provided the materials meet durability, safety and performance specifications.
- Improved material traceability and quality assurance can expand access to regulated applications. The European Commission’s 2025 plastics circularity package identified inconsistent rules for recycled plastics across EU member states as a barrier to cross-border trade. Harmonised end-of-waste criteria and more consistent compliance requirements could reduce administrative friction and help recyclers supply manufacturers across multiple markets.
Challenges: Feedstock Quality, Recycling Economics, and Technical Limitations
- Insufficient collection and sorting restrict the supply of usable recycled feedstock. The European Commission reported in December 2025 that, of approximately 58 million tonnes of plastics produced in the EU, only half was collected and sorted, while around 13% was recycled into new plastics. This highlights the gap between plastic material flows and the volumes that return to manufacturing as recycled polymers.
- High operating costs and competition from virgin plastics undermine recycling profitability. The European Commission identified high energy costs, unpredictable virgin-plastic prices and competition from lower-priced imports as key pressures on European recyclers. It linked these conditions to reduced capacity utilisation, financial losses and bankruptcies, demonstrating that increased recycling demand does not automatically translate into profitable operations.
- Recycling capacity is contracting despite the need for additional supply. EU installed plastics recycling capacity reached 13.2 million tonnes in 2023, but the European Commission projected a net reduction of approximately one million tonnes by the end of 2025. This projected decline highlights the difficulty of maintaining operating capacity when feedstock, cost and offtake conditions are unfavourable.
- Fragmented regulations and uncertain material status increase operating costs. The European Commission estimated that the absence of EU-wide end-of-waste criteria for plastics adds approximately €120 million annually in costs to the European recycling sector, or around €260,000 per recycler on average. These administrative and compliance costs can reduce margins and complicate cross-border trade in recycled polymers.
- International trade and recycled-content verification create market-integrity risks. The OECD’s 2026 monitoring report found that global trade in plastic waste and scrap continued to decline in 2024, while exports from OECD to non-OECD destinations increased. Separately, the European Commission reported concerns about virgin plastics being mislabelled as recycled in imports, which can undercut legitimate recyclers and weaken confidence in recycled-content claims.
Technology and Market Insights
Recycled plastics technology has progressed toward improved waste identification, polymer separation, material recovery, and production of consistent secondary resins. Manufacturers and recycling companies are developing mechanical recycling systems, chemical recycling processes, optical sorting equipment, automated material identification, advanced washing systems, melt filtration, and pelletizing technologies. Mechanical recycling involves physical processing of recovered plastics into reusable materials, while chemical recycling uses chemical or thermal processes to recover monomers, chemical feedstocks, or other outputs from selected waste streams. Major applications include packaging, construction, automotive components, textiles, agriculture, and consumer goods. Technology selection depends on the polymer type, waste composition, contamination levels, required output quality, processing economics, and end-use requirements. Increasing attention to material traceability, recycled-content verification, and processing efficiency is also influencing investment decisions across the recycling value chain.
Technology Scope and Products
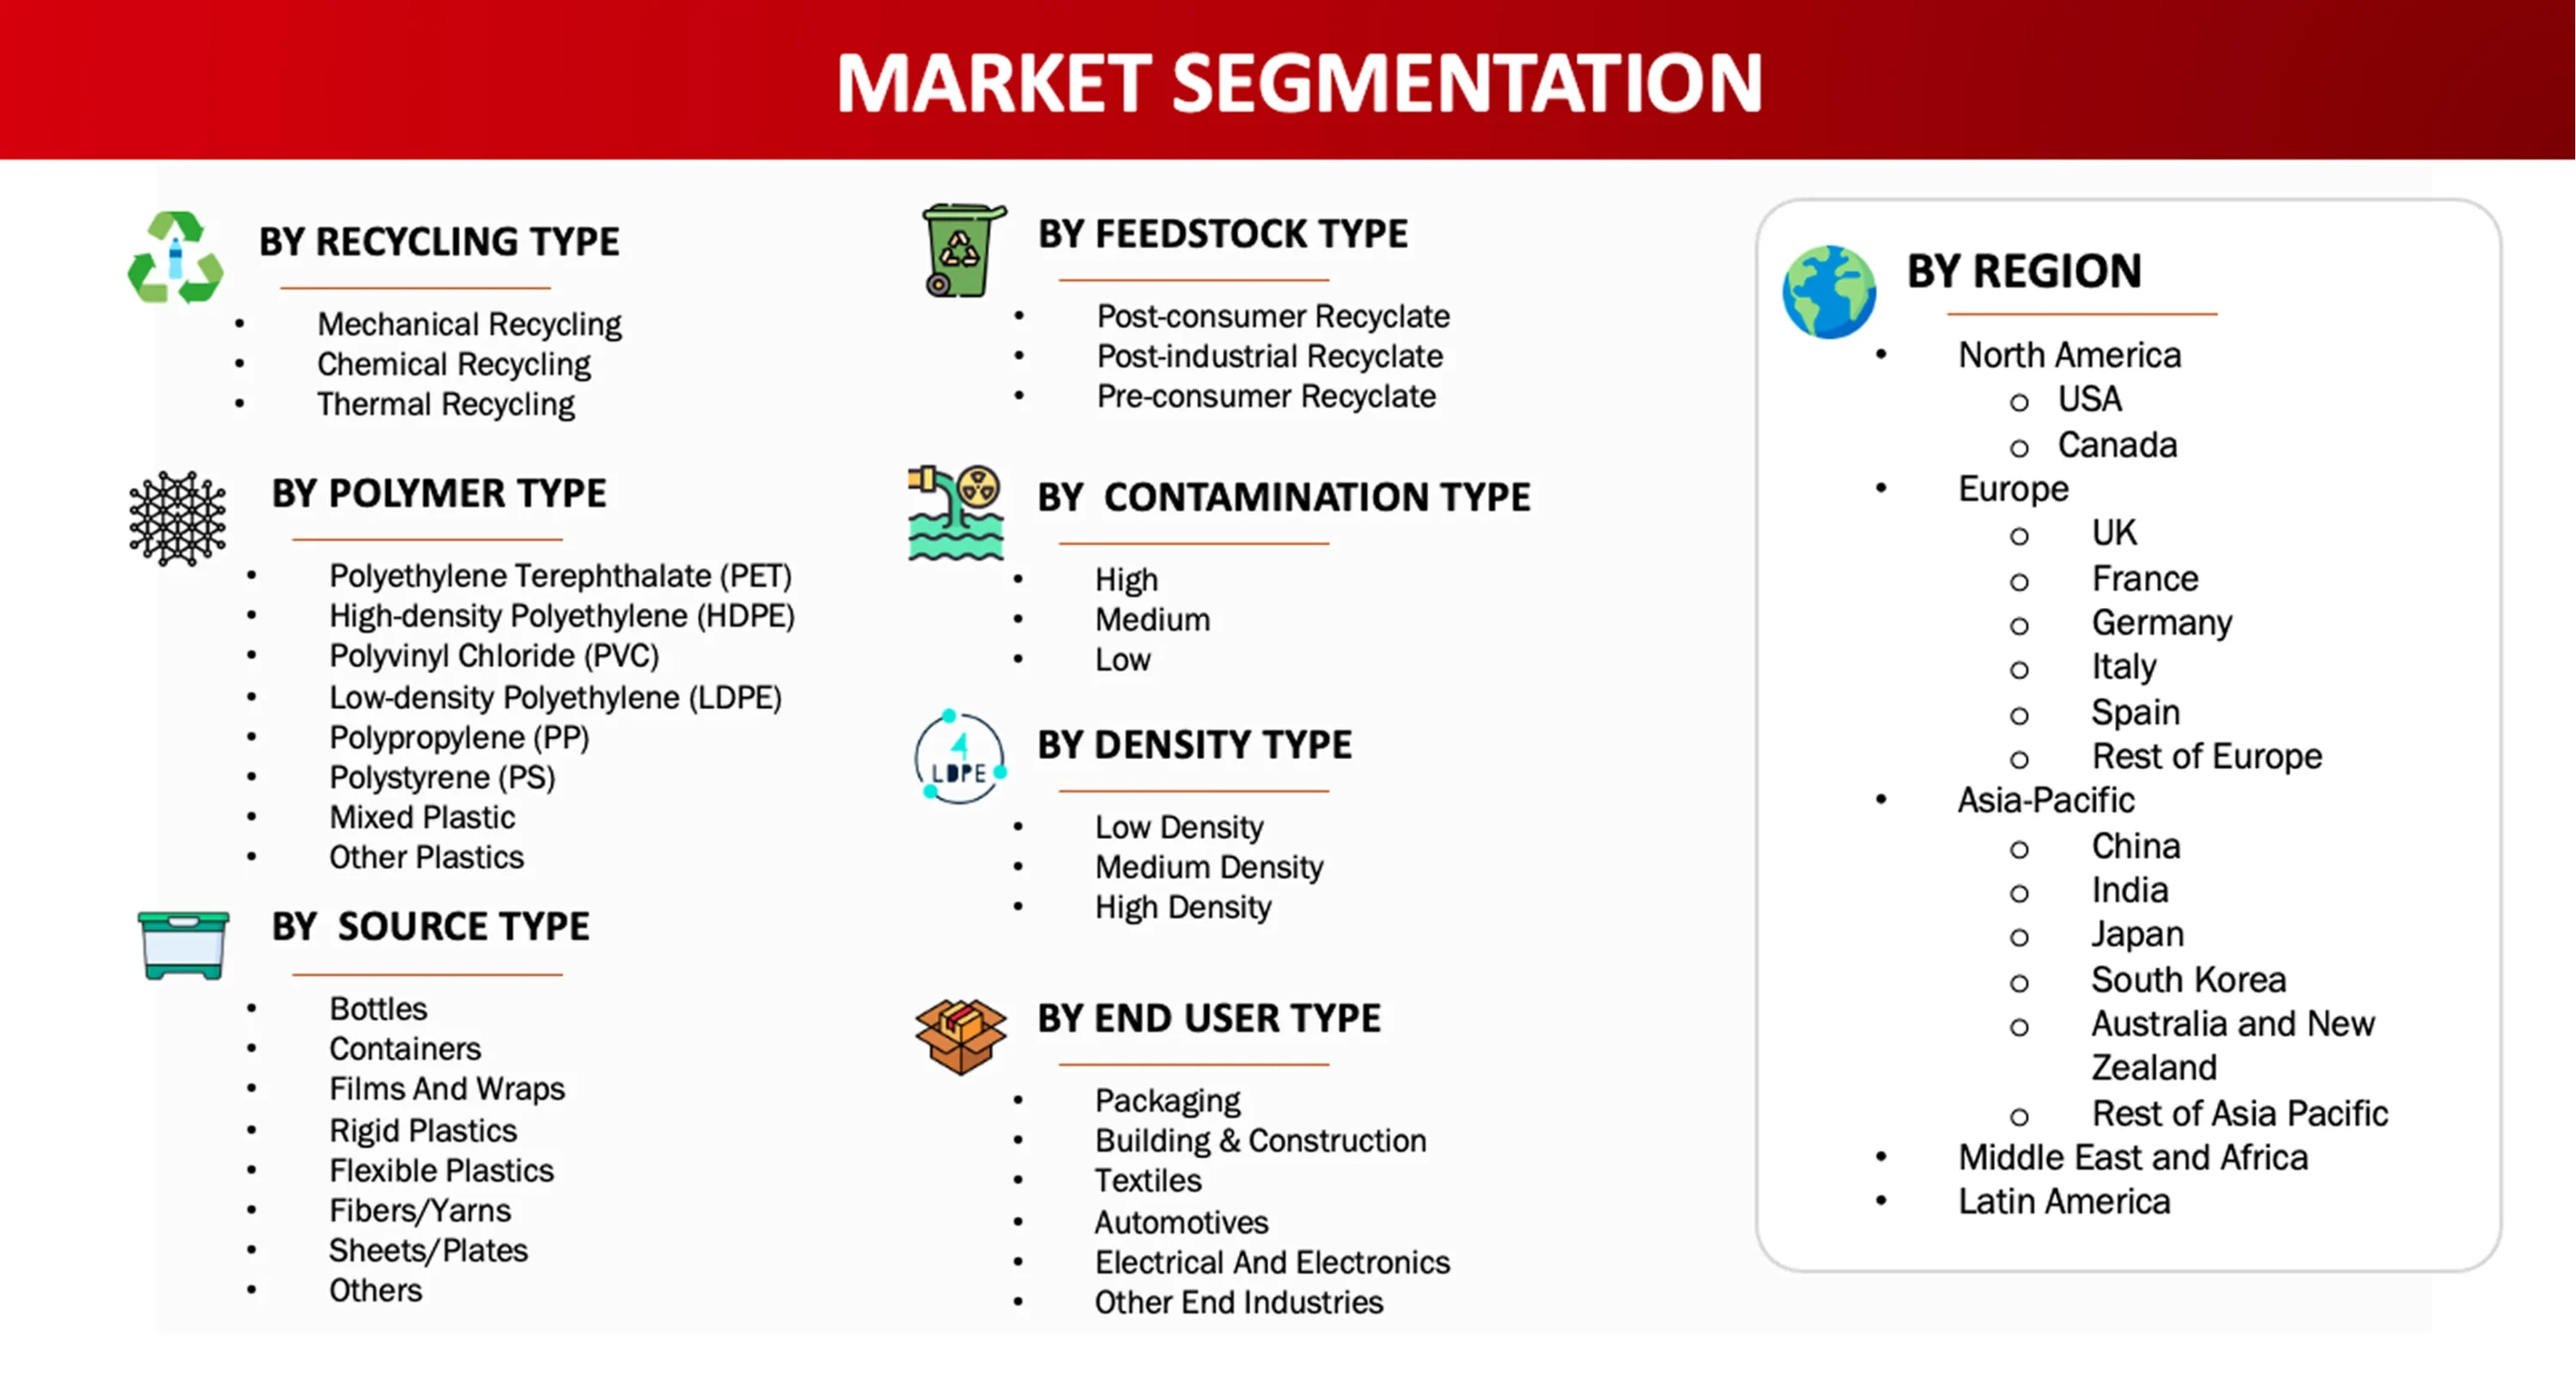
Recycled Plastics Market Segmentation
Want detailed insights from this report?
Competitive Landscape and Market Segments Insights
- The market splits into five player types: integrated PET/packaging leaders (Indorama, ALPLA, Wankai), waste majors (Veolia, Republic Services), petrochemical majors (ExxonMobil, LyondellBasell, SABIC), technology challengers (PureCycle, Carbios, SK Chemicals) and compounders and regional SMEs (Kingfa).
- Waste majors are retreating from reprocessing, led by Europe. Veolia is exiting German plastic recycling entirely and shifting capital to PET in the Nordics and Switzerland and a UK sorting plant. Europe’s roughly 850 plants saw capacity growth stall in 2025 for the first time in years.
- Integrators with captive demand are winning across regions. ALPLA runs 14 plants in ten countries with about 389kt of capacity and uses most of the output in its own packaging. Indorama operates 20+ recycling facilities in 11 countries. Republic Services opened its second US Polymer Center in 2025.
- Petrochemical majors are split between scaling and pausing. ExxonMobil doubled its Baytown advanced recycling capacity in 2025 and targets 1 billion lb/year by 2027. SABIC and Plastic Energy produced first pyrolysis oil at their Geleen JV. In contrast, LyondellBasell delayed its MoReTec-2 investment decision after a $738M net loss and Eastman put its Texas plant on hold for two years.
- Asia is scaling, and Western technology is moving East. Wankai (Zhink Group) holds 70% of a €115M, 50kt PET biorecycling JV with Carbios in China. SK Chemicals is investing about US$100M in a 70kt chemical PET plant in Shantou. PureCycle’s first expansion steps are in Thailand and Belgium.
- Growth in emerging markets is mandate-led. Ganesha Ecosphere recycles 16–18% of India’s PET bottle waste and aims for 25%. Indorama is adding 100kt of capacity in India through a JV with Varun Beverages. In Latin America, Braskem made South America’s first circular PE sale via chemical recycling.
Large-scale post-consumer PET processing supports PET’s market position: Indorama Ventures (Thailand) reported processing 458,500 tonnes of post-consumer PET bales in 2025, supported by an installed bale-input capacity of 837,000 tonnes. This demonstrates the scale of industrial PET recycling operations.
-
PET recycling capacity continues to expand in Asia: Far Eastern New Century Corporation (Taiwan) reported that production of recycled PET (rPET) began at two facilities in 2025, with production scheduled to begin at its Malaysian rPET plant in 2026. The company’s reported capacity equivalent of 34 billion PET bottles annually illustrates the scale of its recycling platform.
-
PET collection remains supported by established recovery systems: NAPCOR’s report published in December 2025 recorded a North American PET bottle collection rate of 39.2% for 2024. This provides recent evidence of an established collection base supplying recycled PET manufacturers.
-
Recycled PET continues to attract investment in new processing facilities: In November 2025, Carbios (France) and Wankai New Materials (China) announced plans for a PET biorecycling plant in China with processing capacity of 50,000 tonnes of PET waste annually, with a longer-term ambition to deploy one million tonnes of capacity.
-
Commercial PET recycling operates at significant industrial scale: Ganesha Ecosphere Limited (India) reported recycling capacity of 206,940 tonnes and more than 8.5 billion PET bottles recycled during FY2025–26. Its operations demonstrate continued industrial demand for post-consumer PET bottle waste as a raw material for recycled products.
Major consumer-goods companies are increasing their use of post-consumer recycled plastic: Unilever (United Kingdom) reported that post-consumer recycled plastic represented 25% of the total plastic used in its packaging in 2025, achieving its stated target for the year. This demonstrates actual commercial use of recovered consumer plastics by a major global packaging buyer.
-
Large recycling companies are processing substantial volumes of post-consumer feedstock: Indorama Ventures (Thailand) reported 458,500 tonnes of post-consumer PET bale input in 2025. This provides a measurable example of post-consumer material being procured and processed at industrial scale.
-
Recycled-content adoption extends across global packaging portfolios: Nestlé (Switzerland) reported that recycled content accounted for 20.6% of its plastic packaging in 2025. The company also reported a 28% reduction in virgin plastic use compared with its 2018 baseline, supporting the relevance of recycled materials to packaging procurement.
-
Packaging producers are incorporating post-consumer recycled material into their products: Amcor plc (Switzerland) reported achieving its target of 10% post-consumer recycled plastic content in its packaging by the end of FY2025. This indicates demand from packaging converters for recovered plastic feedstocks that meet manufacturing requirements.
-
Recycling businesses are developing dedicated post-consumer film recovery operations: Trio world (Sweden) reported in its 2025 sustainability update that it established a dedicated recycling division and inaugurated a facility in Korsberga, Sweden, to expand film recycling and produce post-consumer recycled material for new film applications. This supports the development of feedstock recovery beyond PET bottles into flexible plastic films.
China’s recycled-plastics output increased in 2025: The China Plastics Recycling Association reported that China recovered 20 million tonnes of waste plastics in 2025, up 2.56% year over year, and produced 16.8 million tonnes of recycled plastics, up 2.4%.
-
China’s recycling industry generated substantial economic value: The same association reported that China’s recycled plastics industry generated RMB 103.5 billion in 2025. This demonstrates the scale of commercial activity in one of Asia Pacific’s major markets, although the figure should not be treated as the total regional market value.
-
PET, packaging films and other waste streams support recycled-material supply: China’s industry association reported that PET bottles, packaging films, and plastics recovered from household appliances and end-of-life vehicles represented more than 60% of the country’s waste-plastic recovery mix in 2025. This points to a diversified feedstock base rather than dependence on a single recycling stream.
What This Report Covers-
This report provides a comprehensive analysis of the recycled plastics market, offering insights into key trends, growth drivers, challenges, and future opportunities. It is designed to support strategic decision-making through a combination of quantitative data and qualitative analysis.
Specifically, the report covers:

Market Overview & Definition:
Overview of the market scope, structure, and key terminology

Market Size & Forecast:
Historical data and future projections across key segments and regions

Key Market Trends:
Insights into emerging trends, technological advancements, and evolving demand patterns

Drivers, Restraints & Opportunities:
Analysis of key factors influencing recycled plastics market growth

Competitive Landscape:
Overview of major players, their strategies, and recent developments

Detailed Patent Analysis:
This includes, top assignees, geography focus of top assignees, legal status, technology evolution, key patents and patent trends and innovations

Segmentation Analysis:
Breakdown by recycling process type, by polymer type, by density type, by feedstock type, by source type, by contamination type, by end users’ industry type, and region

Regional Insights:
Key regional trends and growth opportunities

Future Outlook:
Strategic insights and future market direction
Research Methodology
The study of the recycled plastics market is based on a combination of primary and secondary research methodologies, supported by data validation, polymer and recycling technology mapping, plastic waste generation and recovery analysis, recycled resin production and capacity assessment, company revenue and product-portfolio analysis, regulatory and recycled-content requirement assessment, end-use demand analysis, feedstock availability evaluation, recycling infrastructure assessment, trade-flow analysis, and analytical modelling to ensure accuracy and reliability.
Market Definition: Recycled Plastics Market
The recycled plastics market comprises recovered plastic materials processed from post-consumer, post-industrial, and pre-consumer plastic waste for reuse in manufacturing and industrial applications. The market covers recycled polymers, including polyethylene terephthalate (PET), high-density polyethylene (HDPE), polyvinyl chloride (PVC), low-density polyethylene (LDPE), polypropylene (PP), polystyrene (PS), mixed plastics, and other plastics such as polycarbonate (PC), acrylonitrile butadiene styrene (ABS), nylon, and multilayer films.
The market includes recycled plastic materials produced through mechanical recycling and applicable chemical recycling processes, supplied in forms such as flakes, reprocessed granules, pellets, and other reusable polymer feedstocks. Feedstock categories comprise post-consumer recyclate, post-industrial recyclate, and pre-consumer recyclate, classified according to their origin and the study’s defined accounting methodology. The market covers recycled plastics supplied for packaging, building and construction, automotive, electrical and electronics, textiles, consumer goods, and other industrial applications. Recycling equipment, waste collection services, virgin plastics, and recycling technologies themselves are excluded from the market’s material revenue unless explicitly included in the study scope.
Key Stakeholders
The recycled plastics market involves a broad ecosystem of stakeholders:
- Plastic Waste Collection and Recovery Companies
- Plastic Sorting and Processing Companies
- Recycled Plastic Manufacturers
- Mechanical Recycling Companies
- Chemical Recycling Companies
- Packaging Manufacturers and Brand Owners
- Automotive and Transportation Manufacturers
- Building and Construction Companies
- Textile and Fibre Manufacturers
- Electrical, Electronics, and Consumer Goods Manufacturers
- Recycling Technology and Equipment Providers
- Recycled Resin Distributors and Industrial Buyers
Key Objectives of the Study
- To define, describe, analyze, segment, and forecast the recycled plastics market by recycling process type, by polymer type, by density type, by feedstock type, by source type, by contamination type, by end users’ industry type.
- To describe and forecast the market for four key regions: North America, Europe, Asia Pacific, and Rest of the World
- To provide detailed information regarding key drivers, restraints, opportunities, and challenges influencing market growth
- To strategically analyze the micro indicators with respect to individual growth trends, prospects, and contributions to the overall market size
- To analyze opportunities for stakeholders in the recycled plastics industry and emphasize on competitive landscape of the market
- To develop competitive benchmarking of the key market players based on technology specifications and end user
- To strategically profile key players and comprehensively analyze their product portfolio offerings, and core competencies
- To analyze competitive developments, such as launches and approvals, agreements, mergers and acquisitions, partnerships, joint ventures, investments and expansions, and collaborations, recycled plastics domain
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
Research Approach
This research employs a systematic approach by using primary research along with secondary research to achieve full coverage and accuracy of information about the recycled plastics sector. Through this approach, the current market trends in terms of consumer behaviour, technological developments, and competitive environment can be analysed thoroughly.
Secondary Research
Secondary research involves the collection of data from reliable sources such as industry databases, company annual reports, investor presentations, and regulatory filings. This process helps in understanding market trends, identifying key players, and gathering technical and commercial insights.
A comprehensive database of leading companies and market participants is developed through secondary research to support further analysis.
Primary Research
Primary research is conducted to validate findings from secondary research and to gain deeper insights into market dynamics. Interviews are carried out with industry stakeholders across both demand and supply sides, including executives such as CXOs, Vice Presidents, and Directors from business development, marketing, and product teams.
Data is collected through structured questionnaires, email interactions, and telephonic interviews across key regions including North America, Europe, Asia-Pacific, and Rest of the World.
Market Size Estimation
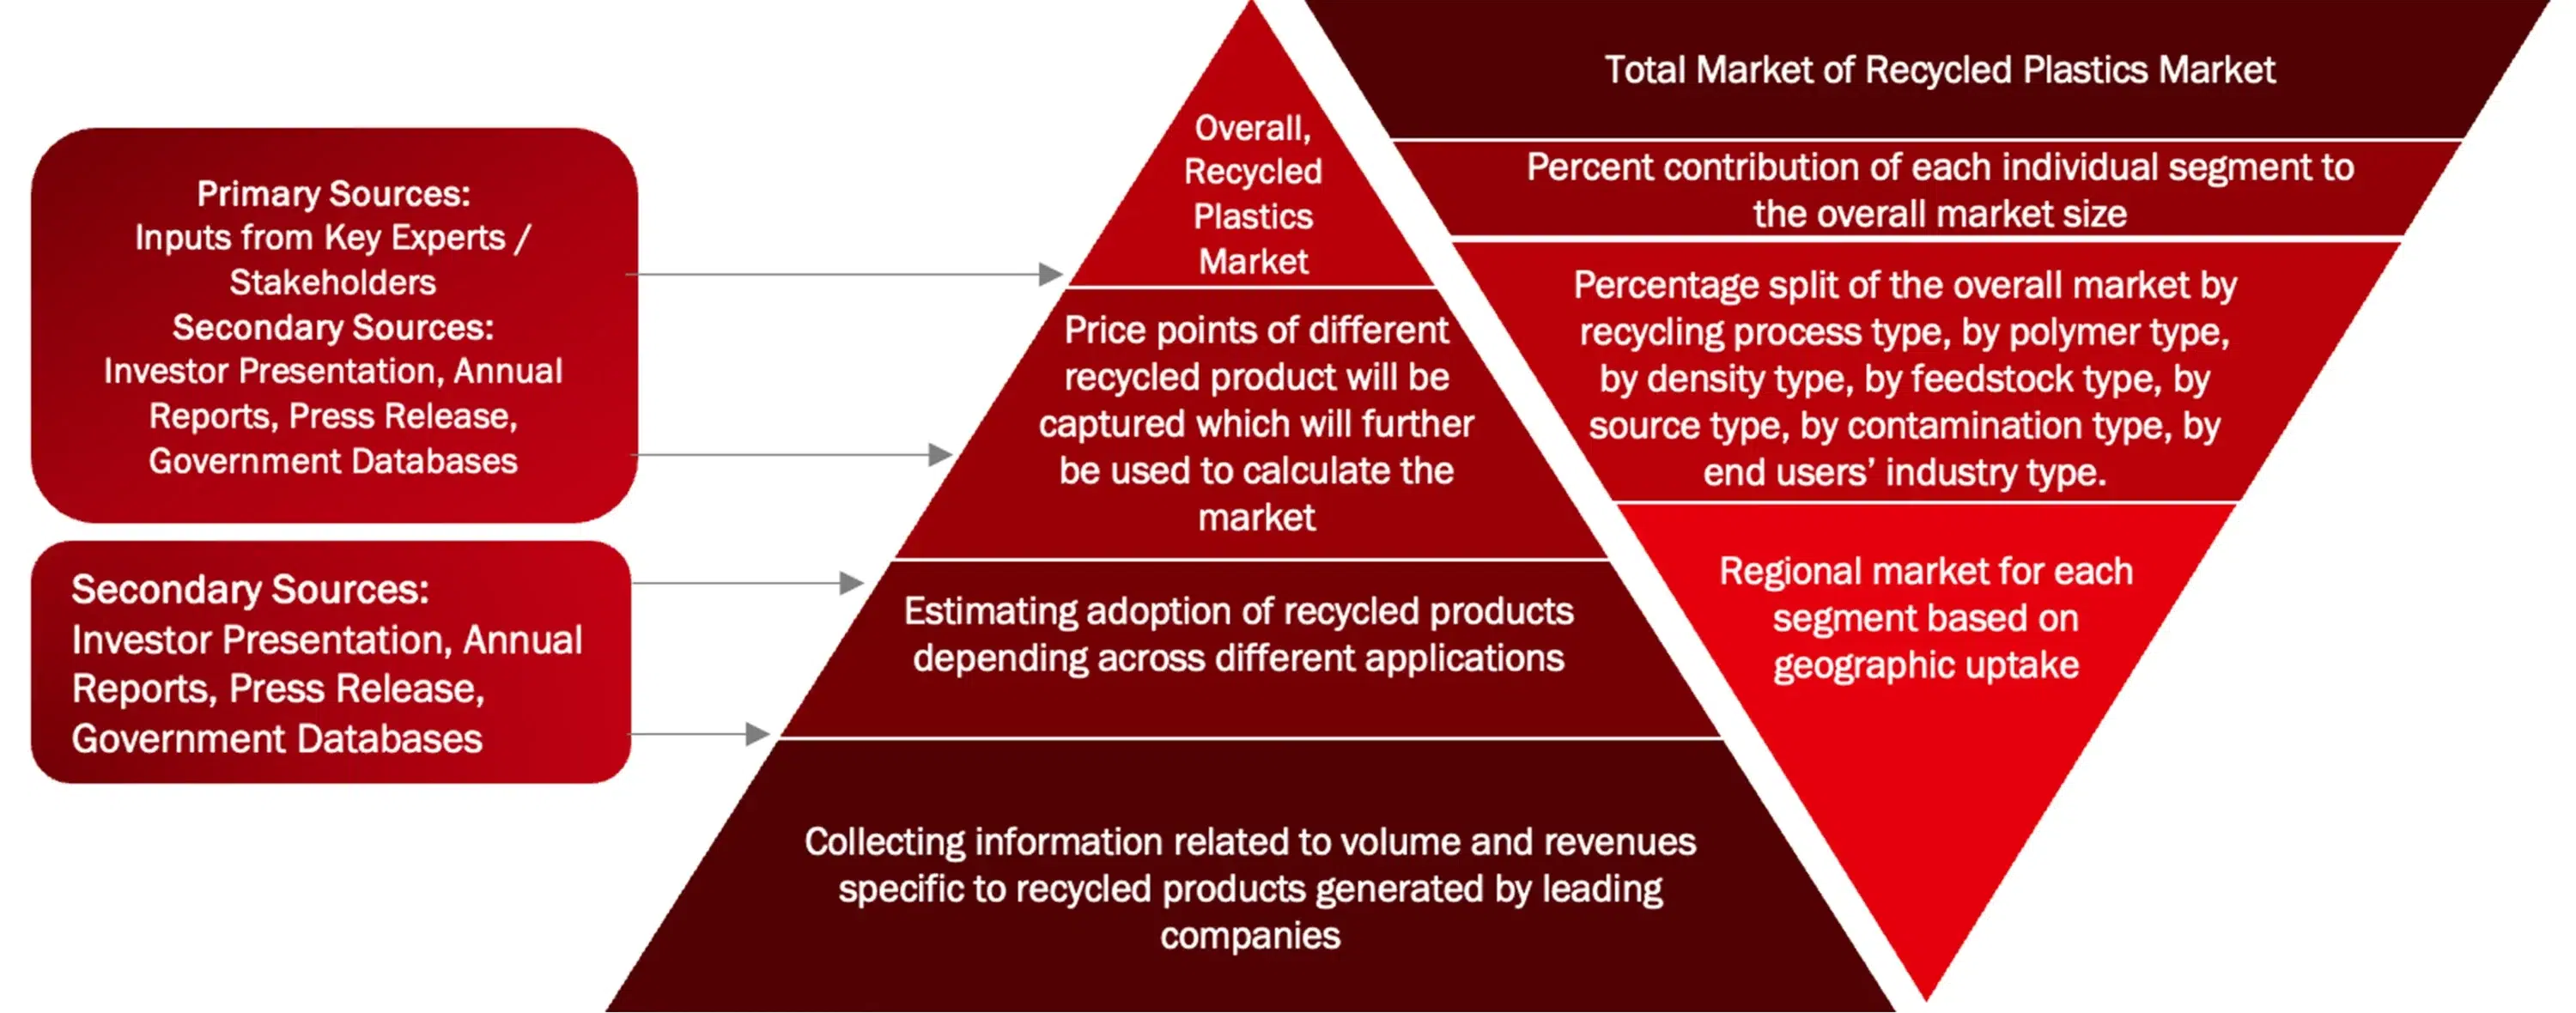
Market size estimation is performed using both top-down and bottom-up approaches. Key market players are identified, and their revenues are analysed to estimate the overall market size.
The market is further segmented based on:
- Product and service mapping across regions
- Adoption patterns across key application segments
- Insights gathered through primary and secondary research
Data Validation and Research Design
After estimating the overall market size, the data is validated using triangulation methods and market breakdown techniques to ensure accuracy and consistency. Both demand-side and supply-side factors are considered to refine the analysis.
The final data is validated through multiple sources to ensure reliability and to provide accurate insights across all market segments and regions.
Assumptions of the Study
The analysis of the recycled plastics market is based on the following key assumptions:
- Trends in the industry are drawn from historical data and current information within the sector
- The future outlook is underpinned by constant economic conditions in the absence of shocks to the market
- The rate of adoption for recycled plastics will rise steadily in all important regions
- The income statement and market share figures are estimated using available information from the industry and publicly available data
- The exchange rate and price trends will not be greatly affected during the forecast period
Scope and Limitations
Scope of the Study
This report offers an exhaustive overview of the global recycled plastics market and includes the following components:
- This report offers an exhaustive overview of the global recycled plastics market and includes the following components:
- This report offers an exhaustive overview of the international recycled plastics market and includes the following components:
- Discussion of primary factors influencing the market
- Competitor analysis
- Insights into regional and national market performance
Limitations of the Study
Despite the best efforts being made to keep the results accurate, the study does suffer from some limitations:
- It has been done using both primary and secondary data that come with their own constraints
- Rapid developments in technology might affect the future course of market dynamics
- Some figures are only approximations due to lack of public disclosure
- The report is not an insurance against any disruptions in macroeconomics and geopolitics
- Future forecasts are indicative and subject to change due to altered industry dynamics
Data Triangulation and Market Breakdown
Data triangulation involved the combination of primary research, secondary research, and the Wissen Research analysis. Once the data points were sourced from the secondary market research, we sanitized the data points to make the market sizing and growth forecast more accurate by developing our own assumptions based on the inputs and insights we gather through the primary interviews with the industry experts. Once the data was thoroughly validated through primary interviews from both, demand and supply side of the market, our team of analyst and other team members involved finalized the market sizing and growth forecast.
Data Triangulation Methodology
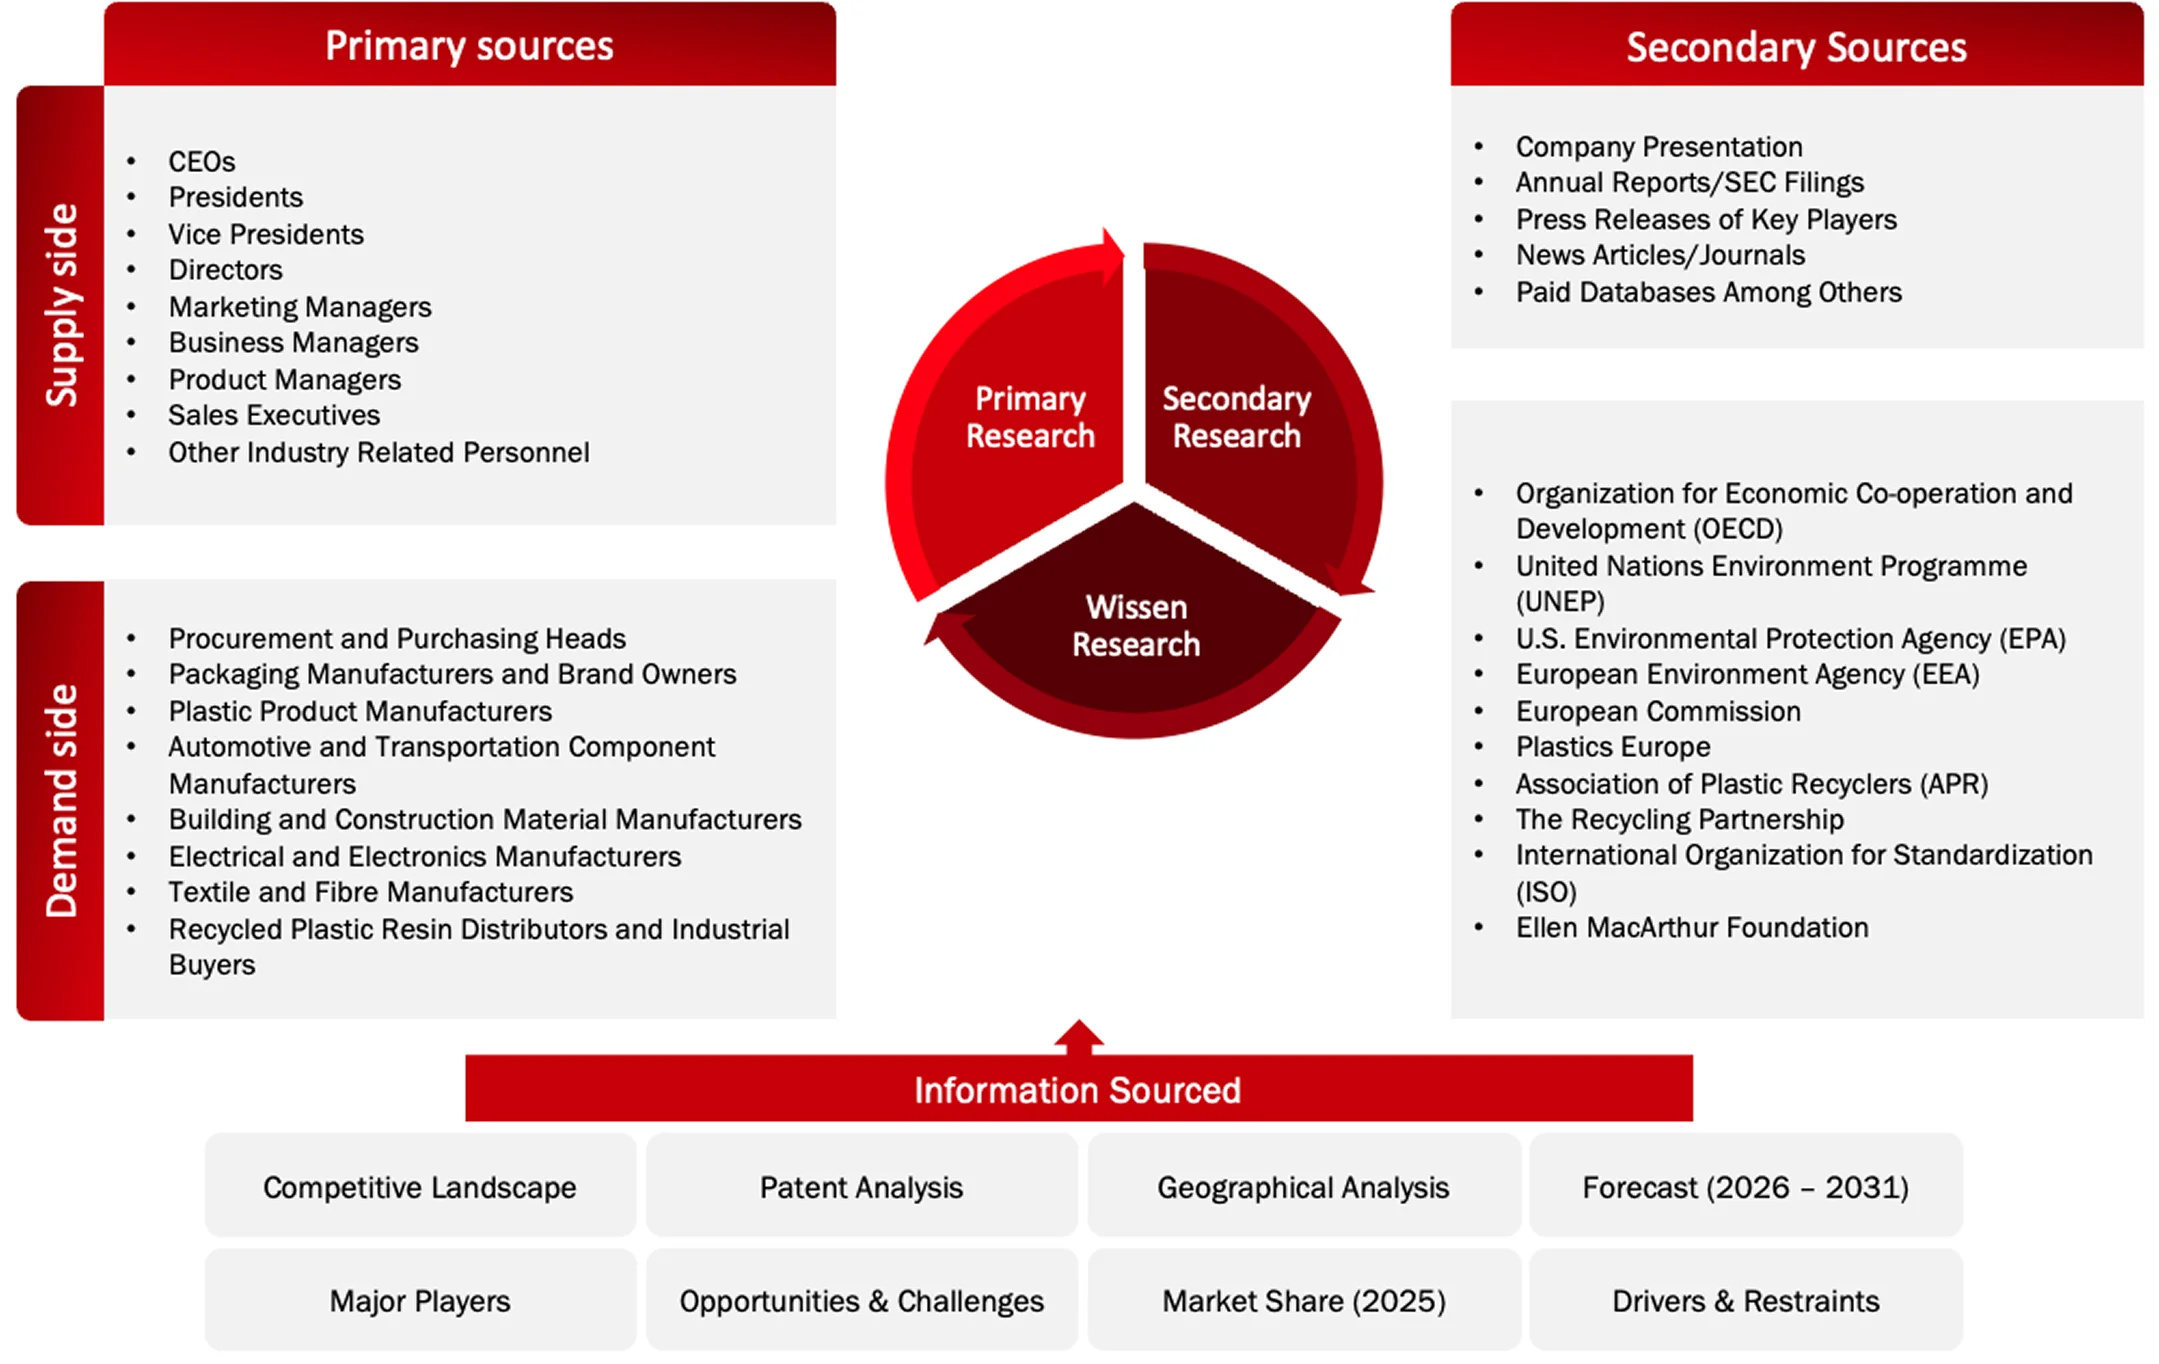
U.S. Environmental Protection Agency, U.S. Department of Energy, European Commission, European Environment Agency, Organisation for Economic Co-operation and Development, United Nations Environment Programme, International Organization for Standardization, Plastics Europe, Association of Plastic Recyclers, European Plastics Recyclers, British Plastics Federation, American Chemistry Council, Company Websites, Press Releases, Annual Reports, Sustainability Reports, Regulatory Filings, Peer-Reviewed Scientific Publications, Paid Data Sources, and Wissen Research Analysis.
Years Framework
Bottom-Up Approach (Demand Side) And Top-Down Approach (Supply Side)
Bottom-Up Approach (Demand-Side Approach):
Determining the market size through the consolidation of demand among end-users, sectors, and geographic areas, which are calculated according to real-world demand conditions.
Top-Down Approach (Supply-Side Approach):
Calculating the market size through revenue and performance of the industry and its important companies, allocating the market size among various sectors.
Want detailed insights from this report?
Buy this Report
Choose the option that best fits your needs