Global Ophthalmic Equipment Market
Global Industry analysis, Size, Share, Growth, Trends, and Forecast 2026-2031
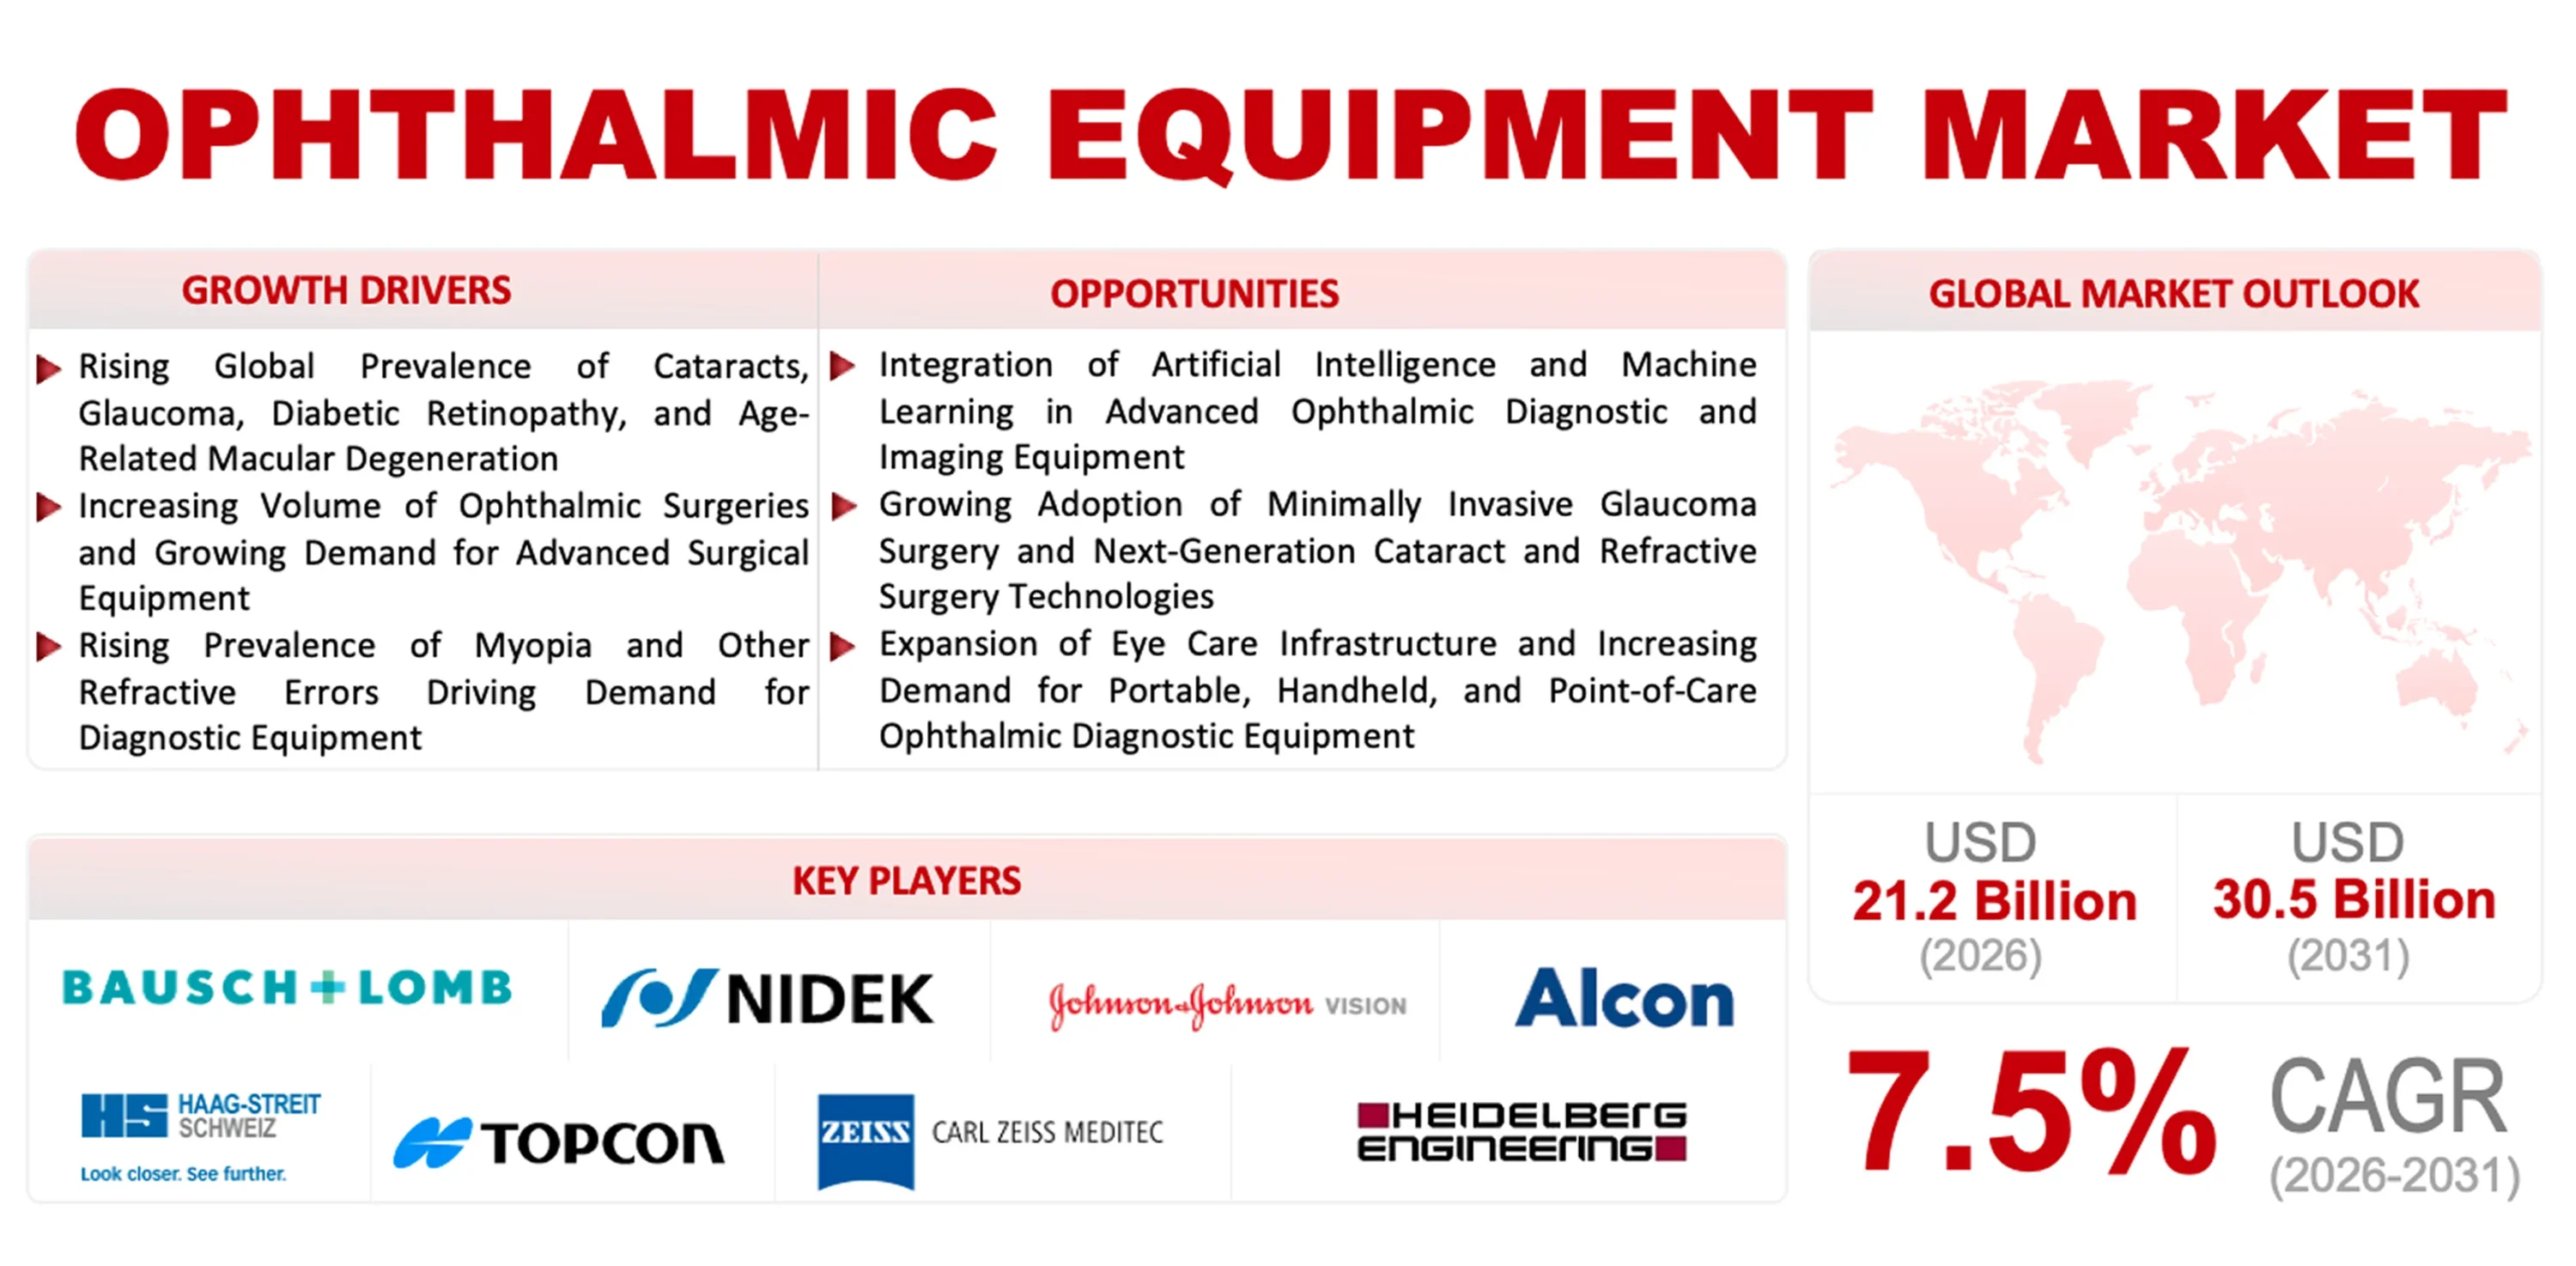
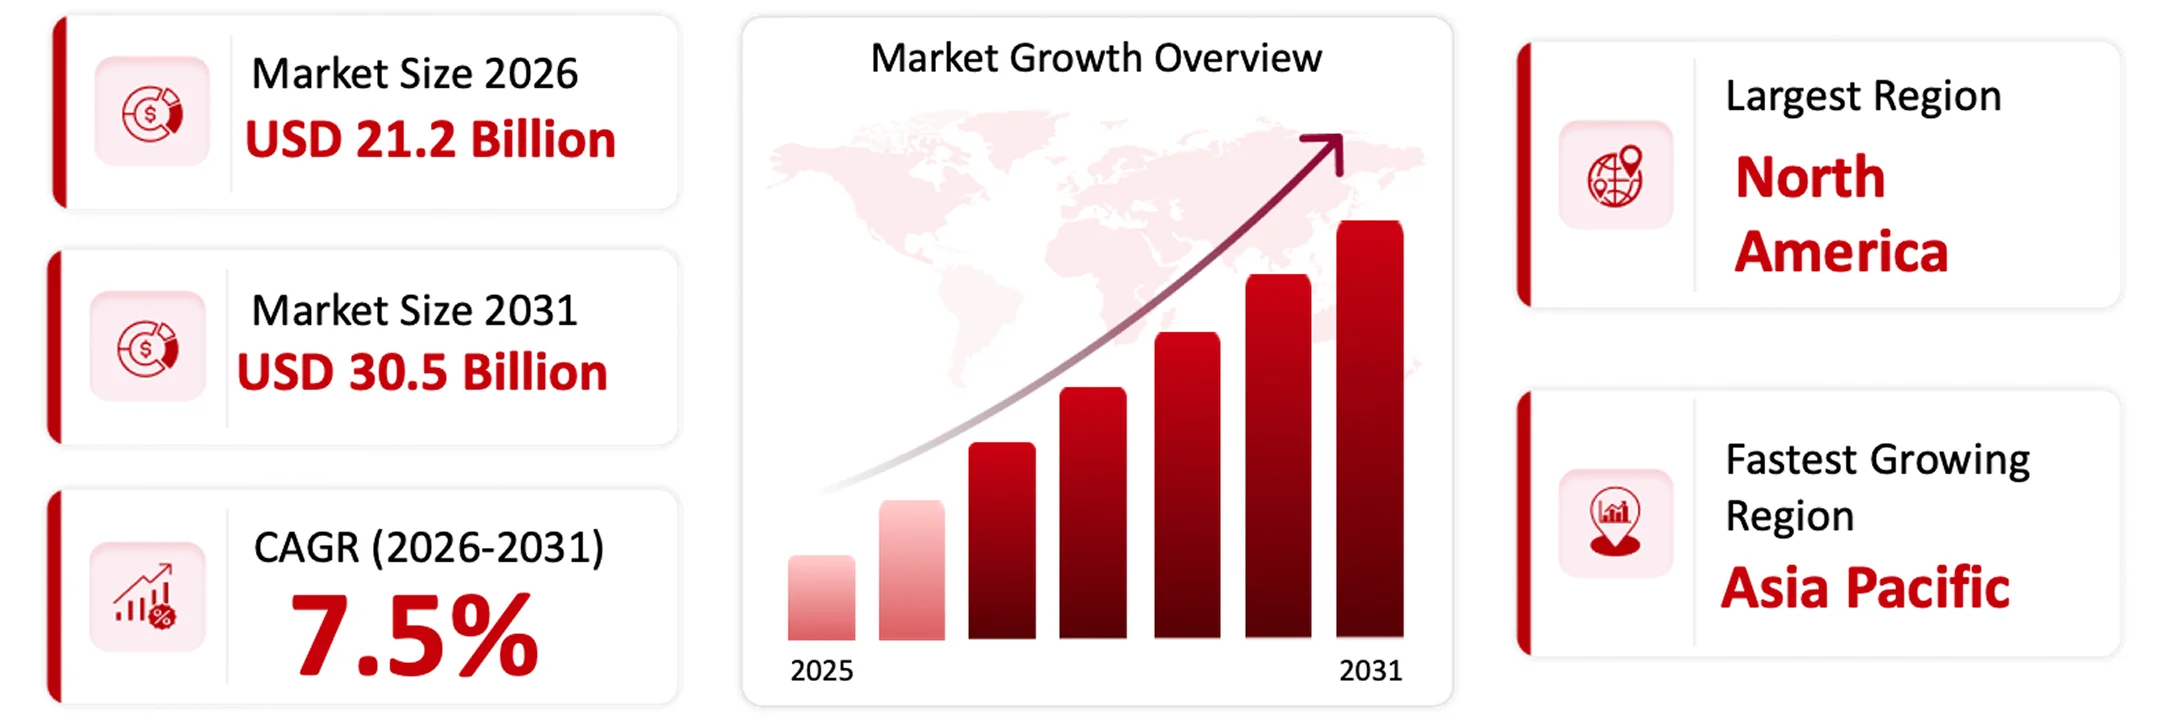
The market is projected to reach USD 30.5 Billion by 2031, growing at a CAGR of 7.5 %during the forecast period (2026-2031).
| Market Size (2026) | Forecast (2031) | CAGR (2026–2031) | Leading Region | Fastest Growing Region |
|---|---|---|---|---|
| USD 21.2 Billion | USD 30.5 Billion | 7.5 % | North America | Asia-Pacific |
Summarize this report with:


Global Ophthalmic Equipment Market Overview
“In my view the global market for ophthalmic equipment is moving towards the adoption of systems that incorporate technology as these systems enhance diagnostic accuracy, surgical results, and efficiency of clinical operations. The demand for cataract surgeries, retinal treatment, treatment of glaucoma, and evading refractive errors has positively impacted the utilization of equipment in hospitals, eye care clinics, and ambulatory surgical centers. Improvements in technology related to Optical coherence tomography, fundus photography, digital imaging, and femtosecond laser ke3ep increasing the efficacy of devices responsible for early diagnosis and minimally invasive treatment. The elderly population, increase in diabetes patients, and improved access to ophthalmological care led to increase in demand, while equipment affordability and distribution issues may limit the introduction of devices globally.”
– Mayur Jain, Research Consultant, Wissen Research
The market is estimated to be USD 21.2 Billion in 2026 and is projected to reach USD 30.5 Billion by 2031, growing at a CAGR of 7.5 %during the forecast period (2026-2031).
Technology Overview
The global ophthalmic equipment market is developing towards high-resolution imaging, artificial intelligence (AI)-based diagnostics, and precision-guided surgical technologies. Optical coherence tomography (OCT) has emerged as the new standard of a retinal imaging technique, with its 30+ million OCT procedures happening each year around the globe, facilitating early disease diagnostics and treatment monitoring. AI-enabled retinal screening as well as automated image processing and portable diagnostic systems expand the spectrum of health checks available beyond specialized eye care facilities. In surgical procedures, femtosecond lasers and image-based technologies are enhancing the precision of surgeries, most notably in cataract operations. The advancements in technology will be subject to clinical validation and affordable pricing as well as workflow integration and regulatory approval.
Key Growth Drivers
- Increasing surgical volumes for cataract treatment: Cataract-related vision loss drives demand for phacoemulsification systems, surgical microscopes, biometry devices, and intraocular lens implantation instruments as healthcare facilities expand surgical capacity and improve procedural efficiency.
- Rising diabetes-related retinal disease burden: Growing diabetes prevalence increases demand for fundus cameras, optical coherence tomography (OCT) systems, and retinal imaging equipment used to detect diabetic retinopathy, monitor disease progression, and guide treatment decisions.
- Shift toward earlier glaucoma detection and monitoring: Glaucoma's often asymptomatic progression increases the need for tonometers, optical coherence tomography, and automated visual field analyzers to identify structural and functional changes before irreversible vision loss occurs.
- Increased occurrence of eye diseases due to age: Increase in population aging will lead to more demand for slit lamps, devices for optical biometry, retinal imaging devices, and equipment for surgery since age-related disorders like cataracts, presbyopia, macular degeneration, etc. require constant monitoring and treatment.
- Wider availability of myopia treatments: Rising cases of myopia and the failures to correct it will lead to the increase of demand for devices such as autorefractors, lensmeters, corneal topographers, and optical biometers across different optometry locations.
- More primary and community-based care services: Government institutions and healthcare providers are extending vision services beyond specialized illustrative establishments. Their demand will raise for such devices as portable fundus cameras, compact refraction systems to provide assistance to those who lack these services and help identify vision-related issues in various communities.
Ophthalmic Equipment Market Key Highlights
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
Ophthalmic Equipment Market Trends
The world of eye medical equipment market is undergoing a transition from traditional medical equipment to ophthalmic equipment that uses AI-enabled diagnostic procedures. Optical coherence tomography (OCT) and wide field retinal imaging considerably influence the detection and monitoring of retinal diseases. Femtosecond lasers and systems of surgical vision significantly improve the precision of surgeries related to cataracts and those that involve refracting. Moreover, mobile devices started being used in remote diagnosis beyond specialized hospitals. However, companies producing the necessary equipment have sought ways to optimize the software, automate their processes, and provide a multitude of equipment functions and features, despite the fact that companies implementing this will be facing big challenges.
AI-enabled ophthalmic imaging and automated diagnostics
Artificial intelligence (AI) in ophthalmic imaging is a key trend in the industry because it allows for automated assessment of the retina and for early detection of diseases as well as expanding the capacity to provide screening outside specialist eye healthcare facilities, where such screening was limited. The availability of AI-based fundus cameras and optical coherence tomography (OCT) machines helps to identify diabetic retinopathy, retinal pathology, and disease progression, which assists eye care professionals in the process of referring patients and managing increasing load of diagnostic testing. The demand is huge: in February of 2026, the World Health Organization reported that at least 2.2 billion people suffer from vision problems at near or far distance — at least 1 billion of which could have been treated.
Recent studies indicated the feasibility of the approach. In December of 2025 National Eye Institute reported that the AI-enabled technology could decrease the amount of data for complex cellular imaging by 75% making the technology closer to commercialization.
Commercial sales are also growing: in 2025 review 36 ophthalmic AI devices were approved by the regulators across Europe and the USA. These developments create opportunities for manufacturers to differentiate equipment through integrated software, automated analysis, and screening efficiency. However, clinical validation, interoperability, regulatory approval, and performance across diverse patient populations remain important adoption considerations.
Shift toward precision-guided ophthalmic surgery and advanced visualization
Advancements in visual technologies, guided-movement systems, and specialized surgical instruments in ophthalmology surgery are becoming more common, creating a conducive environment for surgeons while also making complex surgical procedures easier. The rise of these technologies is clearly seen in the cyst surgery, retina surgery, and refractive surgeries that rely on surgical tools for precise manipulation of tissues and providing good images in the operating room. This is due to the enormous demand for cataract surgeries, according to WHO’s data showing that by 2026 cataract surgery would have produced about 94 million cases of vision limitations, and one out of every two patients who need cataract surgery are unable to undergo the procedure.
The advancement in technologies has gone beyond traditional cataract surgical methods, with introduction of the three-dimensional imaging systems and laser devices making it easier to cut and obtain certain elements in cataract surgical procedures. The review in Current Opinion in Ophthalmology published in September 2026 also included discussions about the progress made in three-dimensional imaging, small-gauge vitrectomy devices, high-speed cutters, and other systems that ease the movement during surgery.
For equipment manufacturers, these developments create opportunities to upgrade surgical platforms and differentiate products through visualization quality, procedural efficiency, and integration with existing operating-room infrastructure. Adoption will depend on capital budgets, training requirements, and demonstrable clinical value.
Key Players in the Ophthalmic Market
Leading companies in the global ophthalmic equipment market are focusing on ophthalmic diagnostic and imaging systems, surgical equipment, laser-based platforms, refractive measurement devices, and advanced visualization technologies. Competition is shaped by diagnostic accuracy, surgical precision, product reliability, technological innovation, installed equipment base, service networks, regulatory compliance, and the ability to integrate equipment with digital clinical workflows.
Strategic Activities Within the Ophthalmic Equipment Market
Alcon Inc. (Switzerland) acquired Neurotech Pharmaceuticals, Inc. (U.S.) for $550 million, adding ENCELTO, the first FDA-approved treatment for Macular Telangiectasia Type 2 (MacTel), to its retinal portfolio. The acquisition strengthened Alcon’s surgical retina capabilities and expanded its presence in innovative implantable retinal therapies.
Haag-Streit Holding AG (Switzerland) launched the Eyesi Surgical Platform 3.0 globally at AAO 2026, introducing advanced virtual-reality simulations for cataract and retinal surgery training. The upgraded platform featured realistic surgical handpieces, an integrated anterior and posterior segment interface, and improved ergonomic components, expanding simulation-based training across surgeons’ professional development.
Johnson & Johnson (U.S.) showcased innovations in cataract care at AAO 2026, including SmartLOAD IOL Delivery Technology, enhancements to the VERITAS Vision System, and advancements in its TECNIS intraocular lens portfolio. The company also reported over one million global implants of TECNIS PureSee and Odyssey IOLs, highlighting continued advancements in cataract surgery.
Carl Zeiss Meditec AG (Germany) launched the DORC EVA NEXUS ophthalmic surgical system in a dedicated cataract configuration, featuring advanced fluidics, intraocular pressure stabilization, and programmable phaco settings. The system expanded ZEISS’s cataract surgery portfolio and was designed to improve surgical precision, stability, and operational control.
Ophthalmic Equipment Market Insights
The global ophthalmic equipment industry is changing to incorporate advanced imaging technology, precision-guided surgical procedures, and digital patient care methods. The driving force for this change is the increasing demand for diagnosing and treating vision-affecting conditions like cataracts, glaucoma, diabetic retinopathy, AMD, and refractive errors. Manufacturers are focused on improving their offerings in the areas of OCT, retinal imaging, optical biometrics, phacoemulsification, and laser surgery. According to WHO, over 2.2 billion individuals around the globe are affected by some kind of vision impairment, including 1 billion individuals who could have prevented their condition if they got proper treatment.
The ophthalmic devices are engaged in examination of eyes, diagnosis of diseases of eyes, sugery of eyes and correction of vision. The use of the devices is in diagnostic purpose which includes imaging of retina, assessing the presence of glaucoma, evaluation of cornea and measuring the intraocular pressure through the use of fundus cameras, OCT machines, tonometer and visual field analyzer respectively. The use of the devices is also in surgical methods through cataract extraction, carrying out retinal surgeries, cornea surgeries and refractive surgeries respectively with the help of surgical microscope, phacoemulsification machine and other instruments of vitreous surgery. In addition, the use of optical biometry and cornea topography facilitates calculation of intraocular lens and planning for refractive surgery respectively. The hospitals and clinics dealing with eye problems need a variety of machines, while the optometrists and people performing community screening tests need small versions of machines. Products are used depending on clinical accuracy, needs of procedures, requirements pertaining to workflow and cost of machines.
AI innovation has introduced several new avenues for development in the sphere of retinal screening, diagnostic tools, surgical visualization solutions, and comprehensive ophthalmological imaging devices. For example, handheld units and portable imaging tools can be used for screening in primary care and rural locations, while automated image processing solutions enable easy prioritization of referrals for healthcare professionals. Digital imaging solutions and advanced technologies for performing phacoemulsification and surgery provide a possibility for making workflow more efficient. According to WHO, there are no less than 1 billion vision impairments which are treatable; thus, there is an urgent need to decrease the gap between provision of diagnostic and treatment services and demand for these services. Moreover, additional revenue can be gained from servicing of devices, software implementation, and complete clinical solutions.
According to industry experts, the principal hurdles in the ophthalmic equipment market include high costs of acquisition, maintenance, requirement of specialized training, and disparity in access to sophisticated technology in eye care. High Capital expenditure on the beneficial technology such as OCT devices, digital retinal imaging devices, femtosecond lasers, and some advanced surgical tools can impede their adoption in smaller clinics and healthcare facilities with limited resources. Moreover, the total cost of equipment ownership is determined by installation and calibration processes, maintenance services, and software upgrades. Insufficient number of ophthalmologists, trained technicians, or patient referral systems may restrict equipment utilization to a low level. Furthermore, it is necessary for manufacturers to fulfill the requirements of medical device regulations and provide proof of the safety, efficiency, and dependability of their products.
The Asia-Pacific region is crucial for the growth of the market in terms of ophthalmic devices due to its vast population of patients, developed health care infrastructure, rising awareness in eye-care and investment in ophthalmology. The demand in China, Japan and India is distinguished, as large screened population, number of operations, advanced imaging systems and adoption of modern surgical techniques can be found in these countries. In regard to India, the National Programme for Control of Blindness and Visual Impairment provides significant help in this field. The development of health care system in Japan and manufacture of ophthalmic equipment by China also contribute to the growth of the market in this region. The necessity for affordable diagnostic devices, surgical instruments, and easily transportable screening tools keeps growing.
Ophthalmic Equipment Market Dynamics
Drivers: Rising Cataract Surgery Demand and the Need to Expand Surgical Capacity
- Large untreated patient pool: In February 2026, the World Health Organization (WHO) reported that cataracts affect more than 94 million people globally, while nearly half of those facing cataract-related blindness still need access to surgery. This supports demand for phacoemulsification systems, surgical microscopes, optical biometry devices, and intraocular lens implantation equipment.
- Surgical coverage is not keeping pace with demand: WHO reported that global cataract surgical coverage increased by approximately 15% over two decades, but projected growth of only 8.4% for the current decade. This gap creates pressure on hospitals and eye-care networks to expand surgical throughput and upgrade equipment.
- Equipment demand is linked to operating-room productivity: Cataract surgery is typically a short procedure, making equipment availability, patient turnover, and operating-room utilization important procurement considerations. Facilities handling large patient volumes have incentives to invest in reliable phacoemulsification platforms and efficient instrument workflows.
- Underserved regions represent additional capacity requirements: WHO reported in February 2026 that three in four people requiring cataract surgery in the African Region remain untreated. Expanding surgical infrastructure in these markets creates potential demand for affordable surgical systems, microscopes, biometry equipment, and dependable maintenance services.
- Commercial implication: Equipment suppliers can target high-volume cataract centres and public eye-care programmes with integrated surgical configurations, financing options, staff training, and service contracts. Procurement decisions will increasingly depend on total cost per procedure, equipment uptime, and patient throughput rather than purchase price alone.
Opportunities: Portable Diagnostics and AI-Enabled Screening in Primary Eye Care
- Substantial unmet screening need: The International Agency for the Prevention of Blindness (IAPB) reported that global effective cataract surgical coverage stood at 44%, based on estimates presented in its 2026 Vision Atlas. This indicates a considerable gap in effective treatment access and reinforces the need for better-connected screening, referral, and treatment infrastructure.
- Handheld refraction equipment can reach underserved populations: In 2025, ATscale published technical guidance on handheld autorefractors, drawing on a multicountry study in Ethiopia, Nepal, and Nigeria. These devices offer a potential alternative to conventional refraction equipment for community-based screening and on-site spectacle provision.
- AI screening has regulatory precedents: The U.S. Food and Drug Administration (FDA) maintains a dedicated classification for software that analyzes retinal images to identify patients with referable diabetic retinopathy. This provides an established regulatory pathway for integrating compatible fundus cameras with automated diagnostic software.
- Screening can be integrated into diabetes care: The American Diabetes Association’s Standards of Care in Diabetes—2025 recognizes retinal photography with remote expert interpretation or FDA-authorized AI algorithms as appropriate strategies for improving diabetic retinopathy screening access. This creates opportunities to supply connected retinal imaging systems to diabetes clinics and primary-care networks.
- Commercial implication: Manufacturers can develop lower-cost, portable diagnostic packages combining fundus cameras, handheld autorefractors, cloud-based image management, and referral software. Partnerships with diabetes clinics, public screening programmes, optical networks, and teleophthalmology providers can expand distribution beyond specialist hospitals.
Challenges: High Equipment Costs and Unequal Access to Diagnostic Infrastructure
- Limited diagnostic access constrains market penetration: A 2024 World Bank article reported that only 19% of people in low-income and lower-middle-income countries had access to the simplest diagnostic tests. Although this figure covers diagnostics broadly rather than ophthalmology alone, it illustrates the wider infrastructure and affordability constraints affecting advanced diagnostic adoption.
- Import dependence increases acquisition costs: The World Bank identifies transportation, distribution expenses, and foreign-currency constraints as factors that make imported medical devices more expensive in many lower-income markets. These barriers can limit procurement of OCT systems, digital retinal cameras, surgical microscopes, and advanced laser platforms.
- After-sales support affects equipment utilization: The World Bank also highlights shortages of trained personnel, replacement parts, and repair technicians as barriers to keeping medical equipment operational. For ophthalmic equipment suppliers, inadequate local servicing can increase downtime and reduce the effective value of installed systems.
- Advanced systems require complementary clinical capabilities: OCT interpretation, retinal disease assessment, laser-assisted surgery, and complex ophthalmic procedures require appropriately trained professionals. Where specialist availability is limited, purchasing advanced equipment alone may not translate into higher patient volumes or better clinical outcomes.
- Commercial implication: Manufacturers must compete on total cost of ownership, local service coverage, operator training, equipment durability, and financing flexibility. Modular product portfolios, locally supported distribution, and simplified systems designed for lower-resource settings can improve adoption while reducing the risk of underutilized installations.
Technology and Market Insights
Global technological advancements in the ophthalmic equipment industry show that many innovations are emerging in high-res diagnostic imaging, AI-based disease diagnostics, precision surgery, and integration into clinical workflows. The manufactures have begun to improve OCTs, wide field retinal imaging technologies, optical biometric devices, corneal topography, and automated visual field tests to enhance the efficacy of diagnostics. From the point of view of surgery development, modern phacoemulsification system construction, femtosecond laser technologies, and digital surgical microscopes are the key innovations in this market. At the same time, AI-assisted retinal testing and imaging devices based on remote technology are becoming part and parcel of local screening and tele-ophthalmology.
Technology Scope and Products
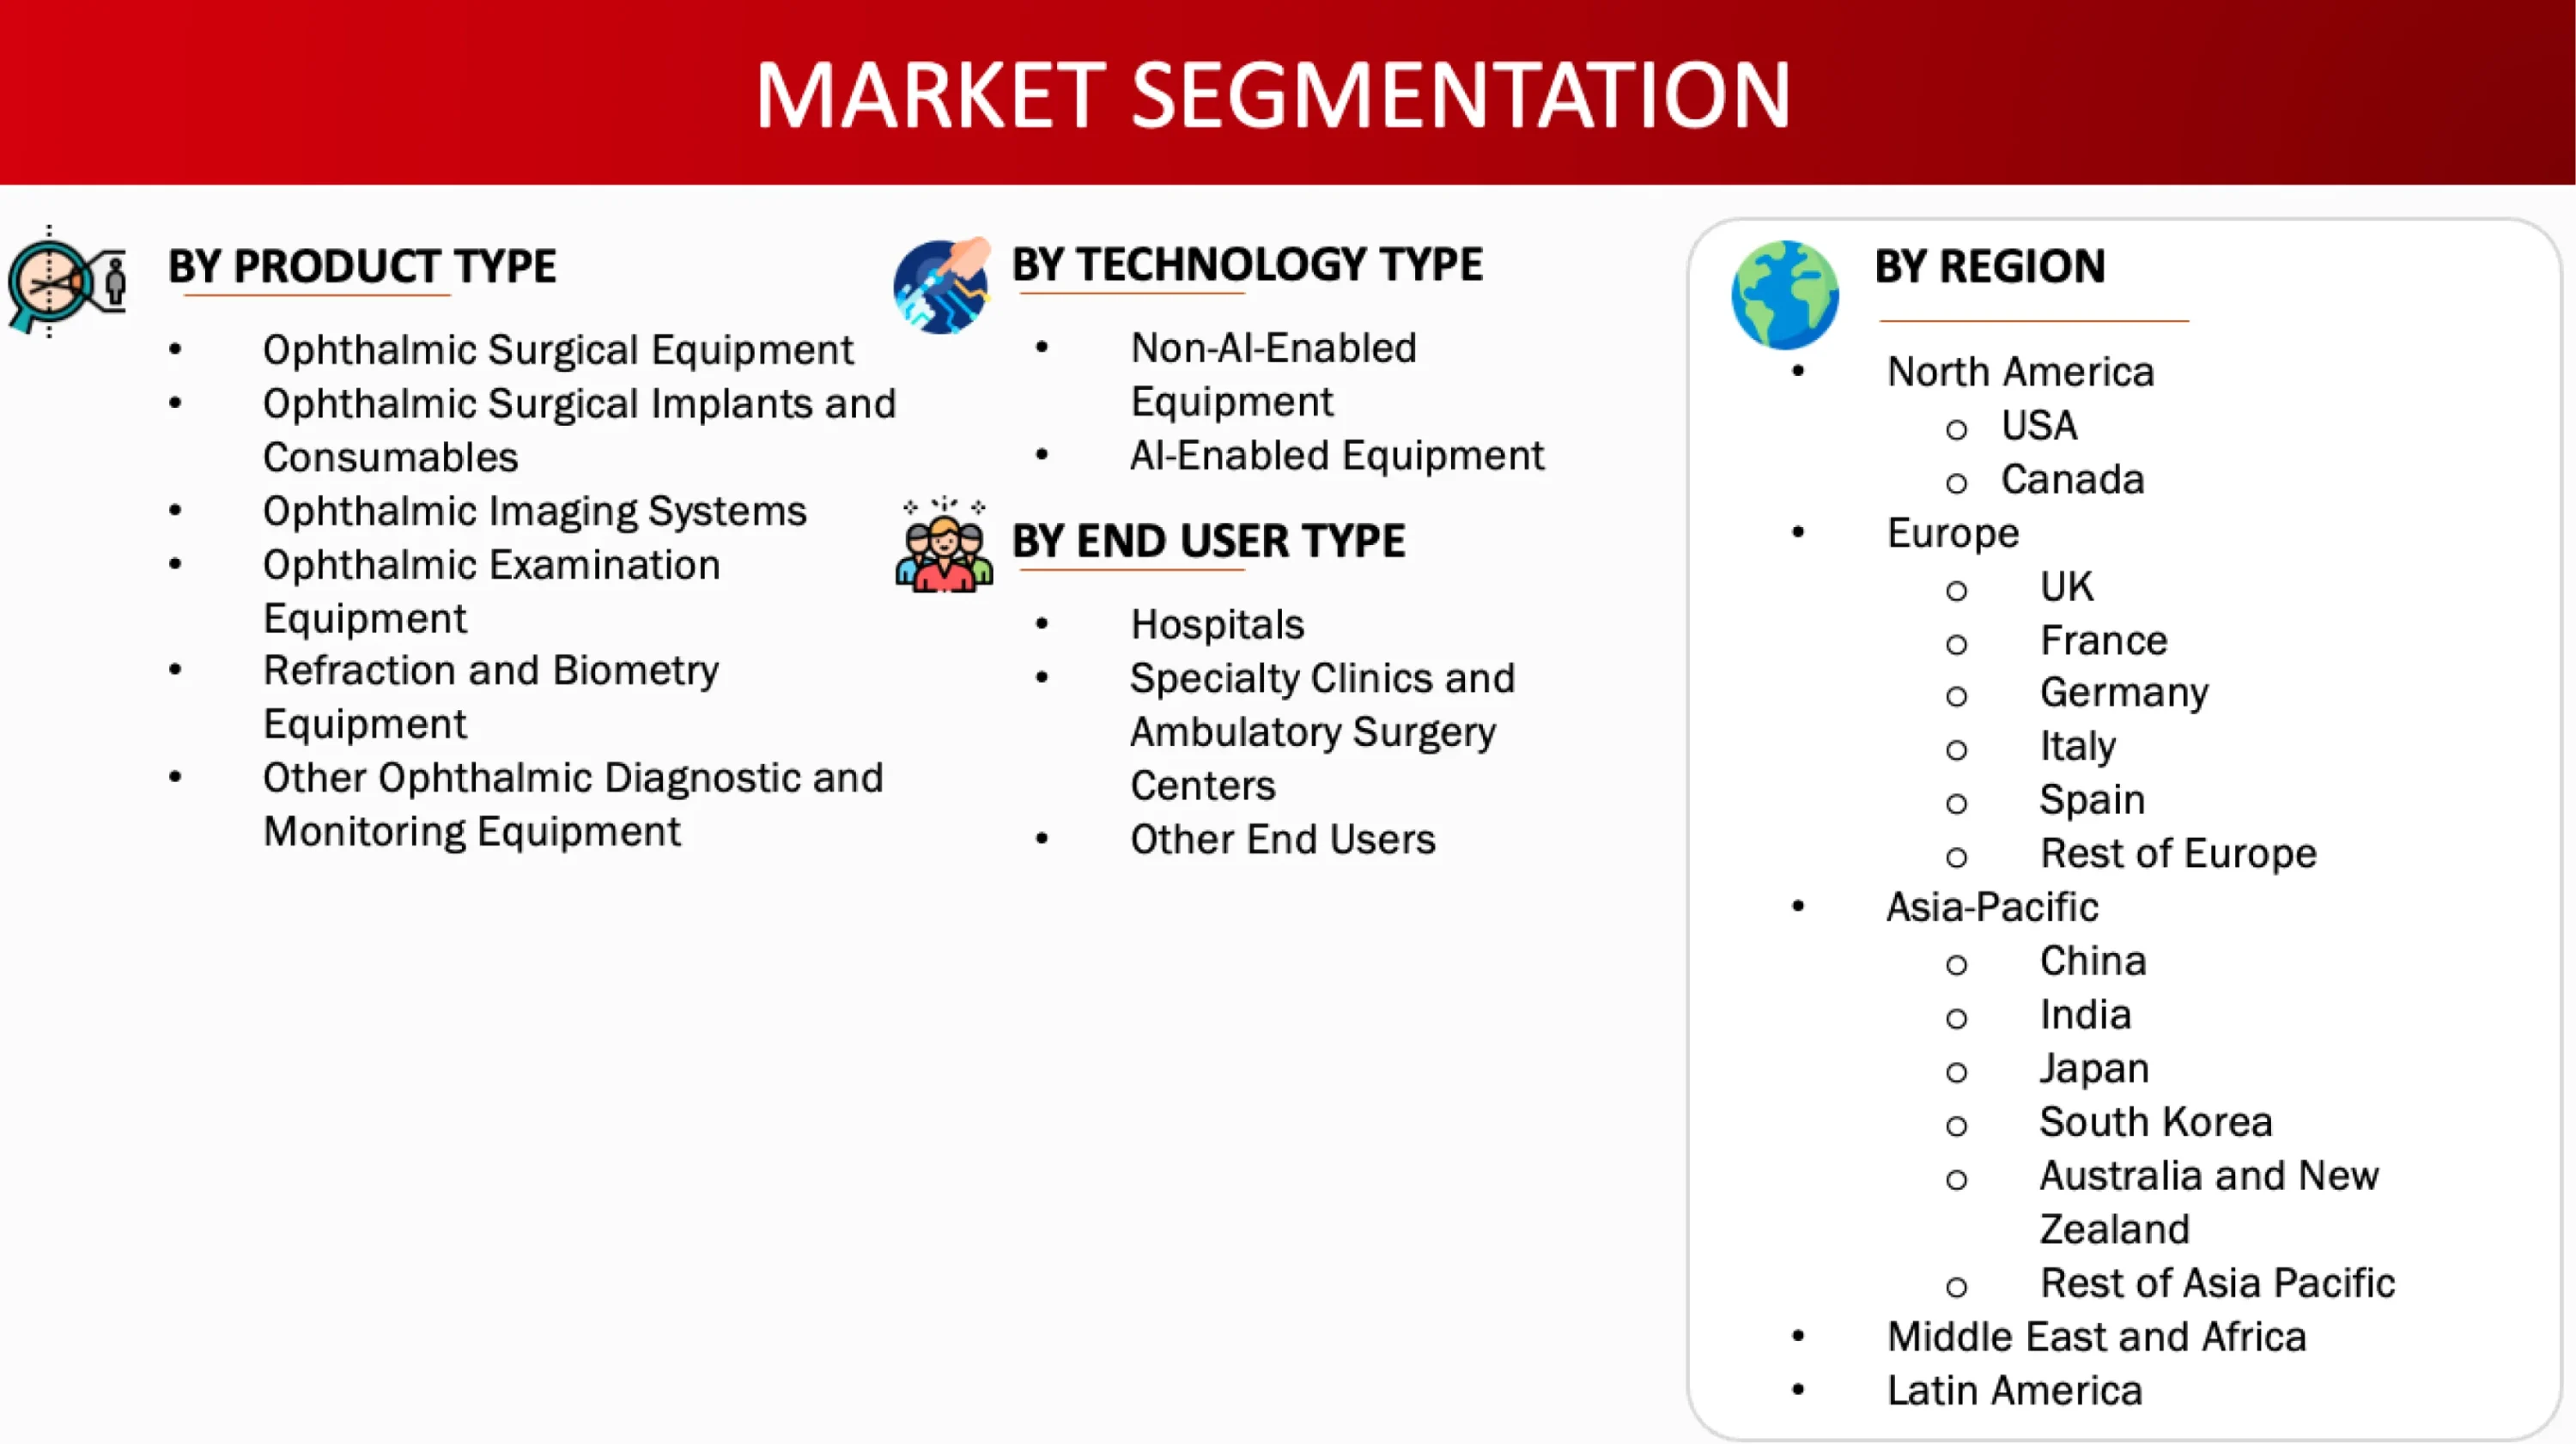
Ophthalmic Equipment Market Segmentation
Want detailed insights from this report?
Competitive Landscape and Market Segments Insights
- Category-specific market leadership: Alcon Inc. (Switzerland) reported $10.3 billion in total 2025 sales and leadership in ophthalmic surgery, while Carl Zeiss Meditec AG (Germany) and specialized manufacturers compete across diagnostic imaging, examination, and measurement equipment.
- Installed-base advantage and recurring revenue: Alcon Inc. (Switzerland) generated $3.03 billion from surgical consumables in 2025, compared with $941 million from surgical equipment and other products, illustrating how equipment installations support recurring consumables demand and customer retention.
- Broad portfolios versus specialist expertise: Alcon Inc. (Switzerland) and Bausch + Lomb Corporation (Canada) compete across multiple ophthalmic categories, whereas Heidelberg Engineering GmbH (Germany) focuses on diagnostic imaging. Buyers balance consolidated procurement against specialized clinical capabilities.
- Technology differentiation drives competitive positioning: Carl Zeiss Meditec AG (Germany) generated €1,723.7 million in ophthalmology revenue in fiscal 2024/25, up 8.5%, supported partly by equipment recovery, intraocular lens growth, and the DORC acquisition.
- Global distribution and service coverage shape competitiveness: Alcon Inc. (Switzerland) operates in 56 countries and serves customers across more than 140 countries and territories, demonstrating the importance of distribution reach, technical support, clinician training, and maintenance.
- Competition varies between premium and cost-sensitive segments: Advanced surgical and imaging platforms compete through clinical capabilities and workflow efficiency, while routine examination equipment faces stronger affordability pressures, making local servicing, financing, reliability, and lifetime ownership costs important differentiators.
Ophthalmic surgical implants and consumables maintained a strong market position in 2025, supported by recurring cataract procedures, demand for intraocular lenses, and the continuous use of procedure-specific supplies. Unlike durable equipment, these products require replenishment with each procedure, creating sustained demand.
-
Substantial surgical consumables revenue: Alcon Inc. (Switzerland) reported approximately USD 3.0 billion in surgical consumables sales in 2025, demonstrating the commercial importance of recurring ophthalmic surgical products.
-
Large cataract patient population: The World Health Organization (WHO) reported in 2026 that cataracts affect more than 94 million people globally, supporting demand for intraocular lenses and associated surgical supplies.
-
Significant procedure volumes: Eurostat reported more than 5 million cataract surgeries across the European Union in 2023, illustrating the substantial requirement for implants and procedure-related consumables.
-
Established commercial scale: Alcon reported approximately USD 5.8 billion in total surgical business sales in 2025, encompassing equipment, consumables, and implants, highlighting the importance of surgical products within ophthalmic care.
Non-AI-enabled equipment maintained a broad clinical presence in 2025 because routine eye examinations, conventional imaging, refractive assessment, and ophthalmic surgery continue to rely on established devices. Its widespread clinical use, established workflows, and broad applicability support adoption across hospitals and specialist clinics.
-
Established surgical equipment sales: Alcon Inc. (Switzerland) reported approximately USD 941 million in surgical equipment and other product sales in 2025, reflecting continuing demand for conventional surgical platforms.
-
Broad diagnostic applications: Slit lamps, tonometers, autorefractors, and conventional visual field analyzers support routine eye examinations and disease monitoring across healthcare settings, sustaining demand beyond AI-enabled applications.
-
AI adoption remains application-specific: The U.S. Food and Drug Administration (FDA) authorizes AI-enabled medical devices for defined clinical purposes, including certain retinal screening applications. This specialized scope contrasts with the wider range of routine examinations and surgical procedures performed using established equipment.
-
Established clinical workflows: Conventional ophthalmic equipment supports familiar diagnostic protocols and existing clinical infrastructure, while AI-enabled systems may require additional validation, software integration, and workflow adjustments before deployment.
North America benefits from established ophthalmic surgical infrastructure, access to advanced diagnostic technologies, reimbursement for eligible procedures, and the presence of major equipment manufacturers. These factors support the adoption of premium imaging systems, surgical platforms, and procedure-related consumables.
-
Substantial U.S. disease burden: The U.S. Centers for Disease Control and Prevention (CDC) estimates that 20.5 million Americans aged 40 years and older have cataracts in one or both eyes, supporting demand for diagnostic and surgical equipment.
-
Reimbursement-supported cataract procedures: Medicare Part B covers eligible cataract surgery and conventional intraocular lens implantation, supporting access to surgical treatment and associated equipment.
-
Significant U.S. commercial presence: Alcon Inc. (Switzerland) reported approximately USD 4.7 billion in U.S. sales in 2025, representing around 45% of its total revenue across its business portfolio.
-
Established regulatory pathway: The FDA’s medical-device regulatory framework supports the introduction of ophthalmic diagnostic and surgical technologies, including authorized AI-enabled retinal screening devices.
What This Report Covers-
This report provides a comprehensive analysis of the ophthalmic equipment market, offering insights into key trends, growth drivers, challenges, and future opportunities. It is designed to support strategic decision-making through a combination of quantitative data and qualitative analysis.
Specifically, the report covers:

Market Overview & Definition:
Overview of the market scope, structure, and key terminology

Market Size & Forecast:
Historical data and future projections across key segments and regions

Key Market Trends:
Insights into emerging trends, technological advancements, and evolving demand patterns

Drivers, Restraints & Opportunities:
Analysis of key factors influencing ophthalmic equipment market growth

Competitive Landscape:
Overview of major players, their strategies, and recent developments

Detailed Patent Analysis:
This includes, top assignees, geography focus of top assignees, legal status, technology evolution, key patents and patent trends and innovations

Segmentation Analysis:
Breakdown by product type, by technology by end users type, by region.

Regional Insights:
Key regional trends and growth opportunities

Future Outlook:
Strategic insights and future market direction
Research Methodology
The study of the global ophthalmic equipment market is based on a combination of primary and secondary research methodologies, supported by data validation, ophthalmic product and technology mapping, procedure-wise demand assessment, diagnostic and surgical equipment evaluation, end-user analysis, company revenue and product portfolio assessment, installed-base and replacement-demand evaluation, technological advancement assessment, regulatory approval analysis, clinical adoption assessment, pricing and reimbursement evaluation, competitive benchmarking, and analytical modelling to ensure accuracy and reliability.
Market Definition: Ophthalmic Equipment Market
The global ophthalmic equipment market comprises the development, manufacturing, and commercialization of medical equipment and devices used for the diagnosis, examination, monitoring, and surgical treatment of eye conditions and vision disorders. The market covers ophthalmic surgical equipment, ophthalmic surgical implants and consumables, ophthalmic imaging systems, ophthalmic examination equipment, refraction and biometry equipment, and other ophthalmic equipment.
The market includes equipment used in cataract surgery, refractive surgery, retinal diagnostics, glaucoma assessment, corneal examination, visual acuity testing, and other ophthalmic procedures. Technologies covered include optical coherence tomography (OCT), fundus imaging, corneal topography, optical biometry, phacoemulsification, femtosecond lasers, and AI-enabled diagnostic systems. The study evaluates equipment adoption across hospitals, specialty clinics, ambulatory surgery centers, and other end users, while assessing technological innovation, clinical utility, regulatory approvals, installed-base expansion, equipment replacement cycles, pricing, reimbursement, and competitive positioning.
Key Stakeholders
The global ophthalmic equipment market involves a broad ecosystem of stakeholders:
- Ophthalmic Equipment Manufacturers
- Ophthalmic Surgical Implants and Consumables Manufacturers
- Ophthalmic Imaging and Diagnostic System Manufacturers
- Refraction and Biometry Equipment Manufacturers
- AI-Enabled Ophthalmic Technology Developers
- Ophthalmic Equipment Distributors and Suppliers
- Hospitals and Multispecialty Healthcare Providers
- Ophthalmology Specialty Clinics and Ambulatory Surgery Centers
- Ophthalmologists, Vitreoretinal Surgeons, and Optometrists
- Regulatory Authorities and Medical Device Approval Organizations
Key Objectives of the Study
- To define, describe, analyze, segment, and forecast the ophthalmic equipment market by product type, by technology type, by end user industry type.
- To describe and forecast the market for five key regions: North America, Europe, Asia Pacific, Latin America, Middle East & Africa.
- To provide detailed information regarding key drivers, restraints, opportunities, and challenges influencing market growth
- To strategically analyze the micro indicators with respect to individual growth trends, prospects, and contributions to the overall market size
- To analyze opportunities for stakeholders in the ophthalmic equipment industry and emphasize on competitive landscape of the market
- To develop competitive benchmarking of the key market players based on technology specifications and end user
- To strategically profile key players and comprehensively analyze their product portfolio offerings, and core competencies
- To analyze competitive developments, such as launches and approvals, agreements, mergers and acquisitions, partnerships, joint ventures, investments and expansions, and collaborations, ophthalmic equipment domain
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
Research Approach
This research employs a systematic approach by using primary research along with secondary research to achieve full coverage and accuracy of information about the ophthalmic equipment sector. Through this approach, the current market trends in terms of consumer behaviour, technological developments, and competitive environment can be analysed thoroughly.
Secondary Research
Secondary research involves the collection of data from reliable sources such as industry databases, company annual reports, investor presentations, and regulatory filings. This process helps in understanding market trends, identifying key players, and gathering technical and commercial insights.
A comprehensive database of leading companies and market participants is developed through secondary research to support further analysis.
Primary Research
Primary research is conducted to validate findings from secondary research and to gain deeper insights into market dynamics. Interviews are carried out with industry stakeholders across both demand and supply sides, including executives such as CXOs, Vice Presidents, and Directors from business development, marketing, and product teams.
Data is collected through structured questionnaires, email interactions, and telephonic interviews across key regions including North America, Europe, Asia-Pacific, and Rest of the World.
Market Size Estimation
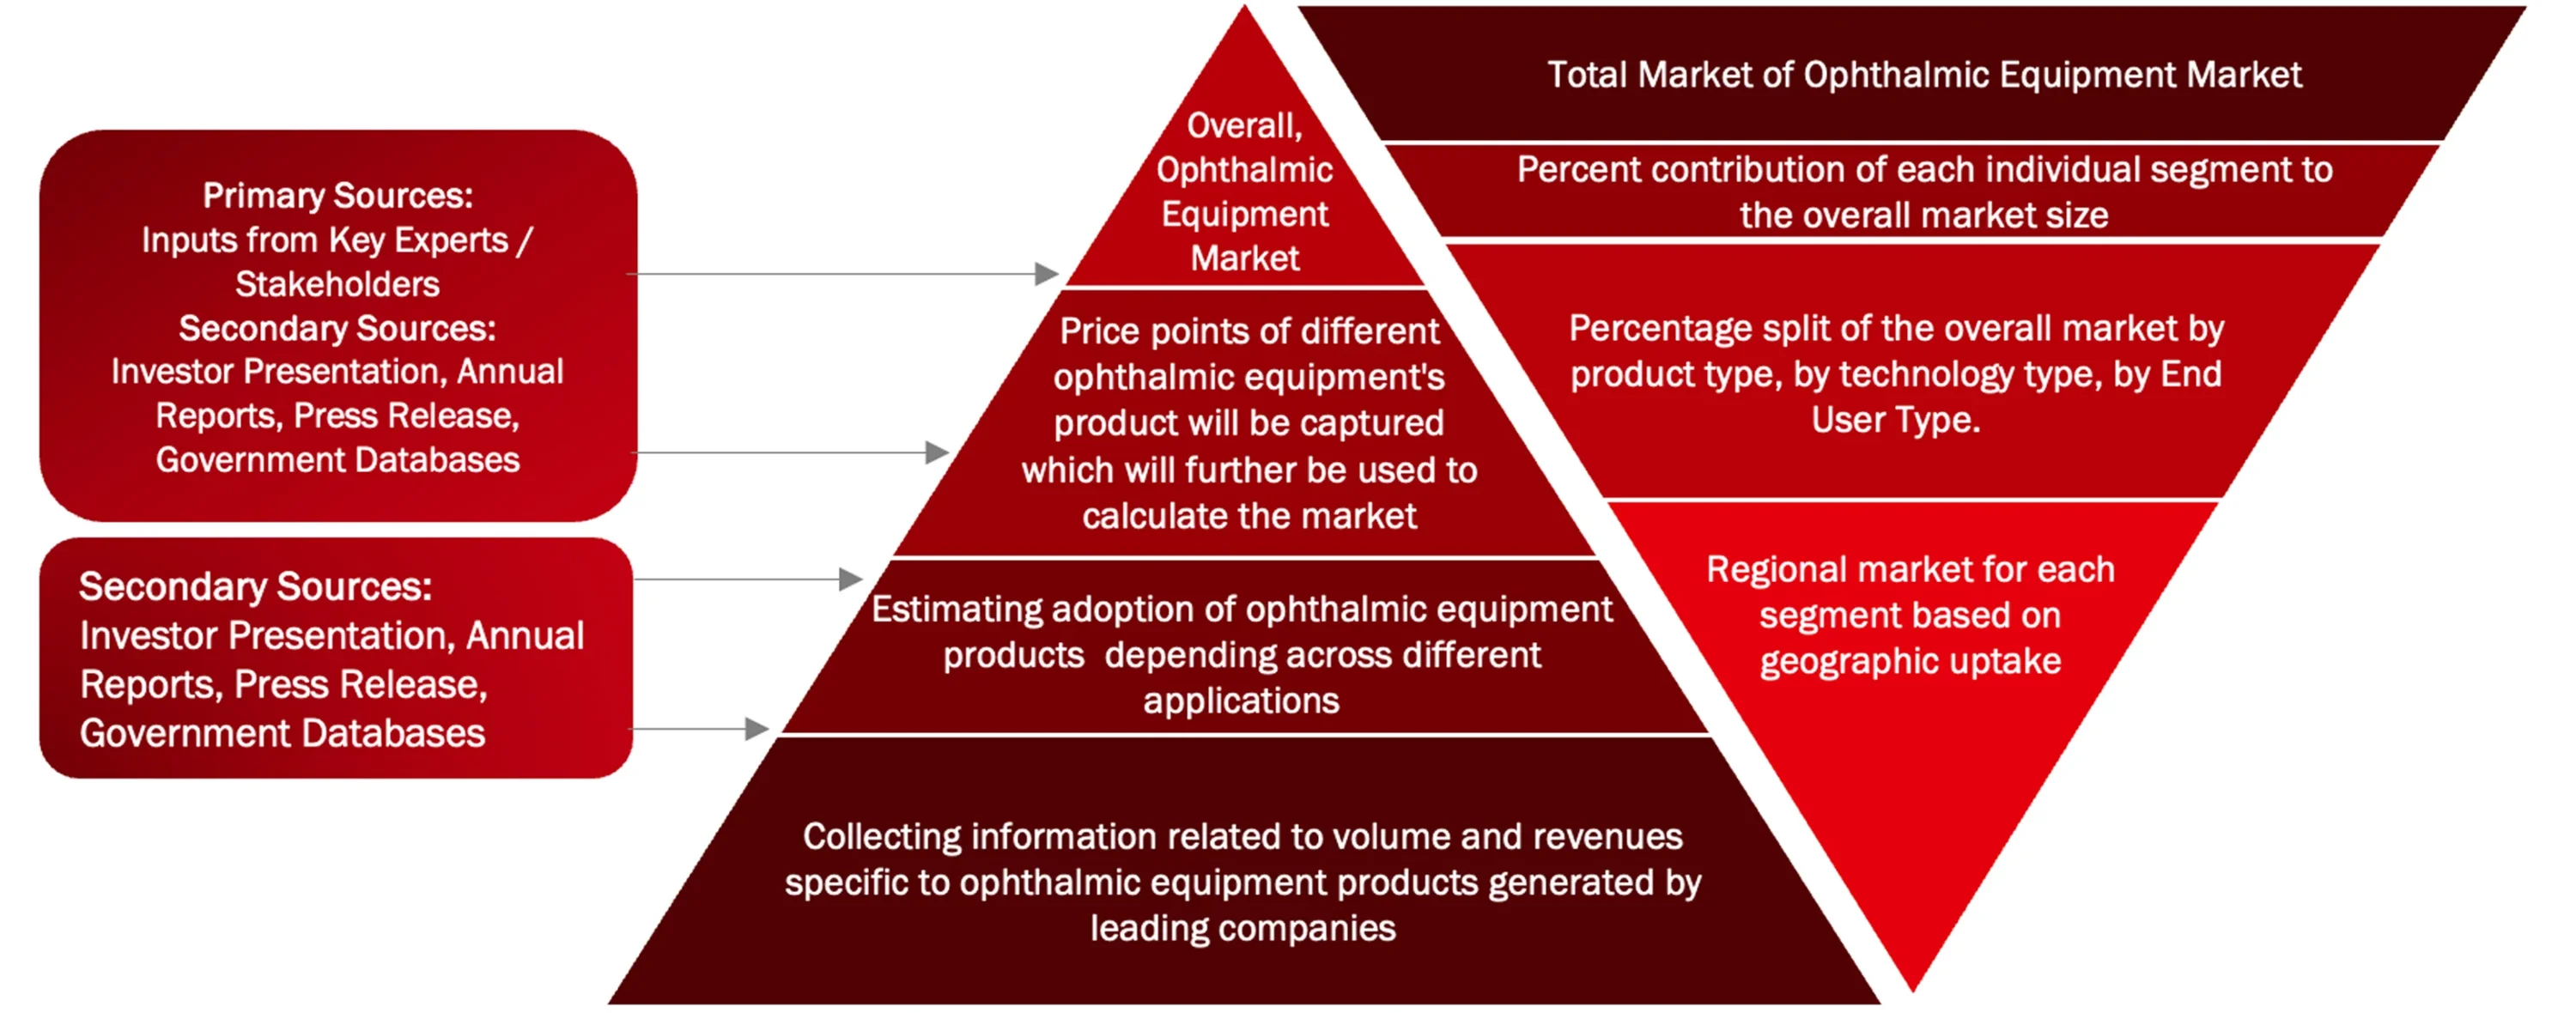
Market size estimation is performed using both top-down and bottom-up approaches. Key market players are identified, and their revenues are analysed to estimate the overall market size.
The market is further segmented based on:
- Product and service mapping across regions
- Adoption patterns across key application segments
- Insights gathered through primary and secondary research
Data Validation and Research Design
After estimating the overall market size, the data is validated using triangulation methods and market breakdown techniques to ensure accuracy and consistency. Both demand-side and supply-side factors are considered to refine the analysis.
The final data is validated through multiple sources to ensure reliability and to provide accurate insights across all market segments and regions.
Assumptions of the Study
The analysis of the ophthalmic equipment market is based on the following key assumptions:
- Trends in the industry are drawn from historical data and current information within the sector
- The future outlook is underpinned by constant economic conditions in the absence of shocks to the market
- The rate of adoption for ophthalmic equipment will rise steadily in all important regions
- The income statement and market share figures are estimated using available information from the industry and publicly available data
- The exchange rate and price trends will not be greatly affected during the forecast period
Scope and Limitations
Scope of the Study
This report offers an exhaustive overview of the international ophthalmic equipment market and includes the following components:
- Summary of market size, growth trends, and projections
- Carefully segmented market based on market by product type, by technology type, by end user industry type.
- Discussion of primary factors influencing the market
- Competitor analysis
- Insights into regional and national market performance
Limitations of the Study
Despite the best efforts being made to keep the results accurate, the study does suffer from some limitations:
- It has been done using both primary and secondary data that come with their own constraints
- Rapid developments in technology might affect the future course of market dynamics
- Some figures are only approximations due to lack of public disclosure
- The report is not an insurance against any disruptions in macroeconomics and geopolitics
- Future forecasts are indicative and subject to change due to altered industry dynamics
Data Triangulation and Market Breakdown
Data triangulation involved the combination of primary research, secondary research, and the Wissen Research analysis. Once the data points were sourced from the secondary market research, we sanitized the data points to make the market sizing and growth forecast more accurate by developing our own assumptions based on the inputs and insights we gather through the primary interviews with the industry experts. Once the data was thoroughly validated through primary interviews from both, demand and supply side of the market, our team of analyst and other team members involved finalized the market sizing and growth forecast.
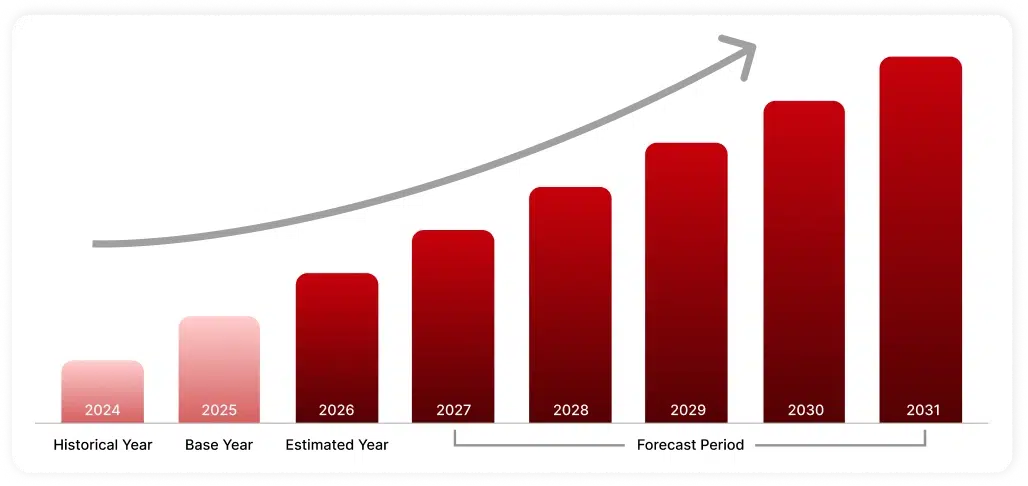
Year Framework
Bottom-Up Approach (Demand Side) And Top-Down Approach (Supply Side)
Bottom-Up Approach (Demand-Side Approach):
Determining the market size through the consolidation of demand among end-users, sectors, and geographic areas, which are calculated according to real-world demand conditions.
Top-Down Approach (Supply-Side Approach):
Calculating the market size through revenue and performance of the industry and its important companies, allocating the market size among various sectors.
Want detailed insights from this report?
Buy this Report
Choose the option that best fits your needs