
In Vitro Diagnostics Market
Global Industry analysis, Size, Share, Growth, Trends, and Forecast 2026-2031
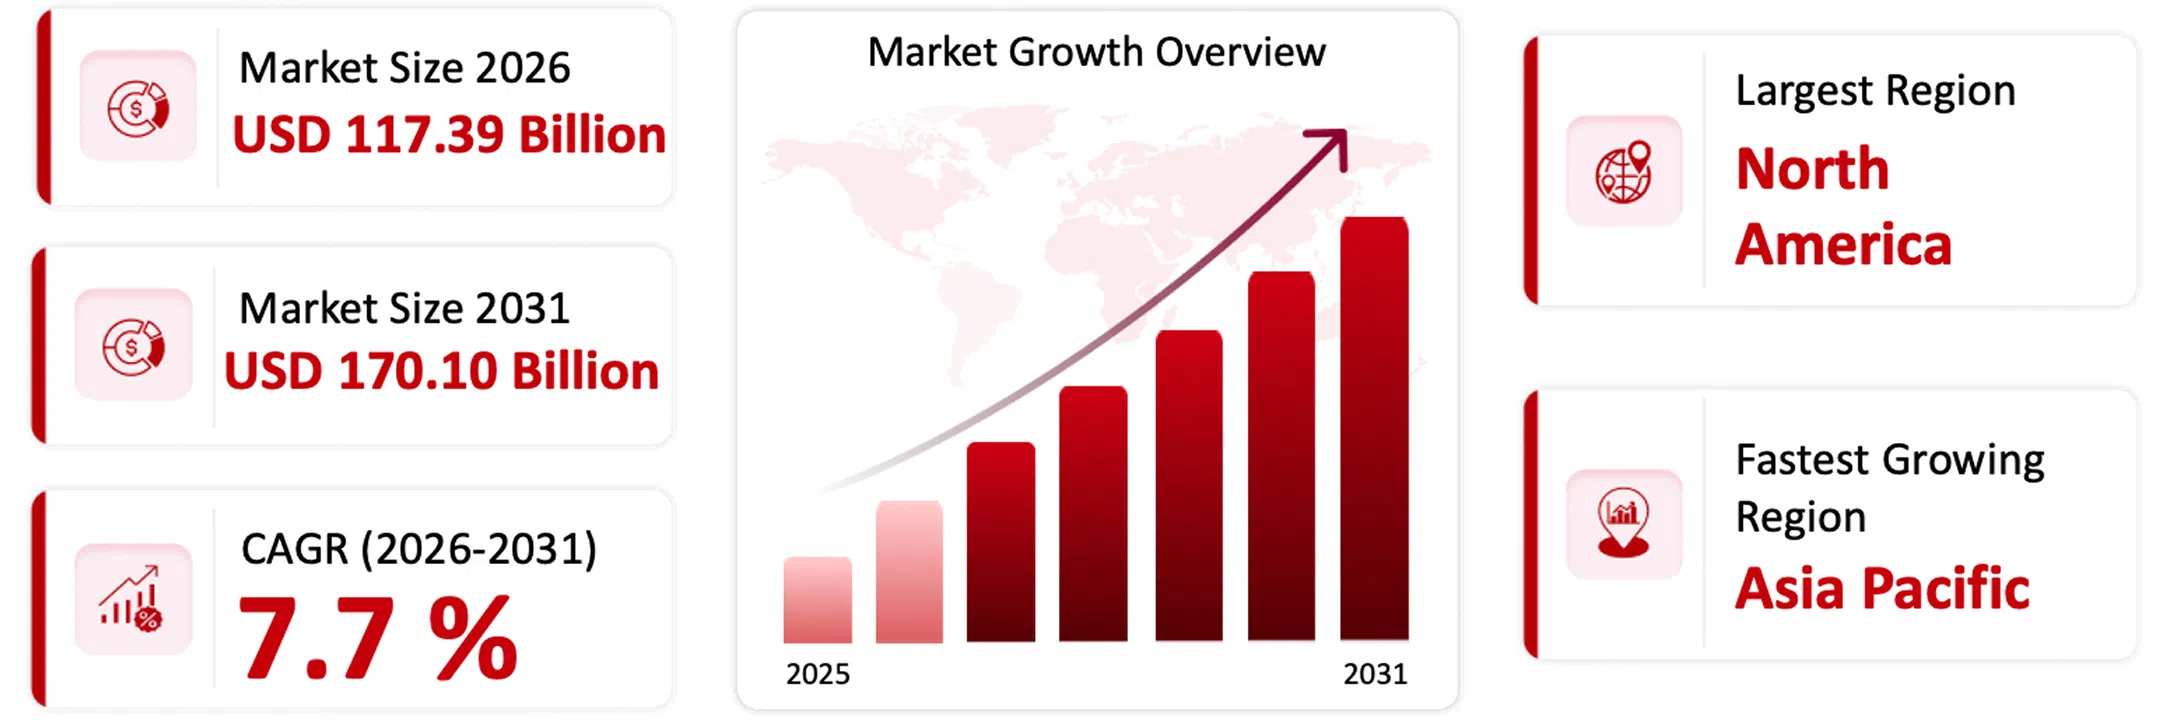
The global in vitro diagnostics market is projected to reach USD 170.10 billion by 2031, growing at a CAGR of 7.7% during the forecast period.
| Market Size (2026): | Forecast (2031): | CAGR (2026–2031): | Leading Region: | Fastest Growing Region: |
|---|---|---|---|---|
| $ 117.39 Billion | $ 170.10 Billion | 7.7 % | North America | Asia Pacific |
Summarize this report with:


Market Overview
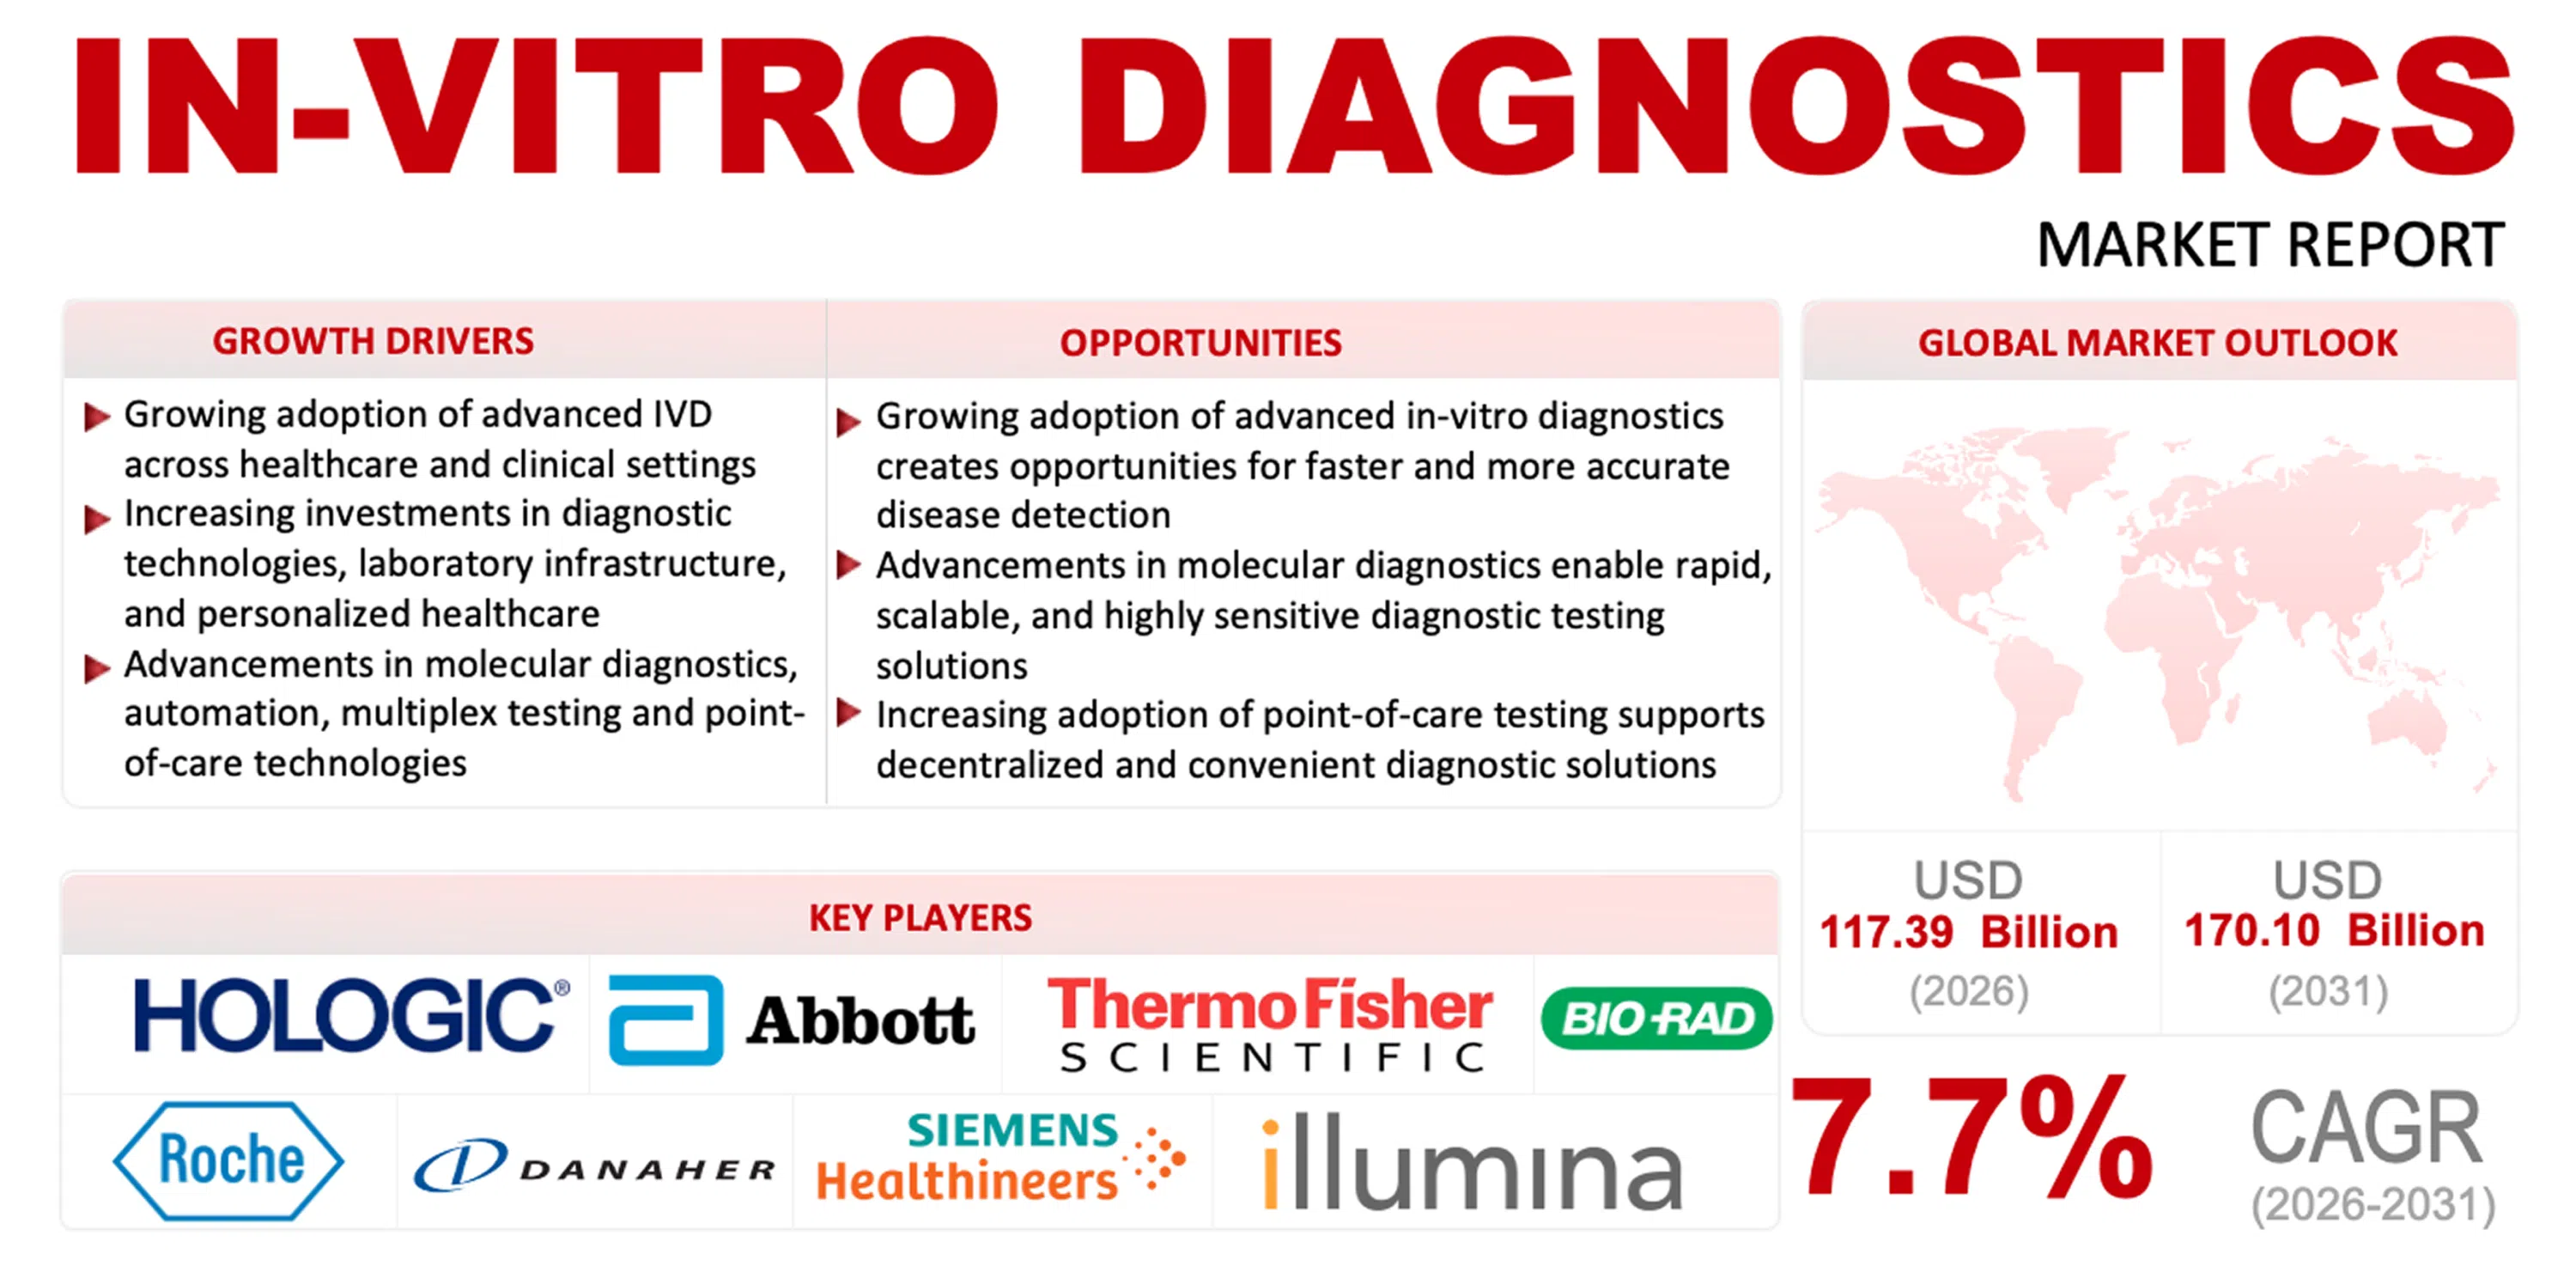
The global in-vitro diagnostics market is experiencing significant growth, driven by increasing demand for early disease detection, accurate diagnosis, disease monitoring, and personalized healthcare. Rising prevalence of chronic and infectious diseases, growing adoption of point-of-care testing, and increasing healthcare expenditure are supporting market expansion. In addition, advancements in clinical chemistry, immunoassay, molecular diagnostics, hematology, microbiology, and coagulation technologies are improving the accuracy, speed, and efficiency of diagnostic testing. Growing use of diagnostic instruments, reagents, and software across hospitals, diagnostic laboratories, and home-care settings, particularly for infectious diseases, oncology, diabetes, cardiology, nephrology, and autoimmune diseases, is further contributing to market growth. The market is estimated to be USD 117.39 billion in 2026 and is projected to reach USD 170.10 billion by 2031, growing at a CAGR of 7.7% during the forecast period (2026-2031).
Technology Overview
In-vitro diagnostics (IVD) are diagnostic tests performed on biological samples, such as blood, urine, and tissue, outside the human body to detect, diagnose, monitor, and manage diseases and health conditions. IVD products include instruments, reagents, and software used across various testing methods, including clinical chemistry, immunoassay, molecular diagnostics, hematology, microbiology, and coagulation. Advancements in diagnostic technologies are improving testing accuracy, sensitivity, specificity, automation, and turnaround time. The growing demand for early disease detection, point-of-care testing, personalized healthcare, and disease monitoring is further supporting the adoption of IVD solutions across diagnostic laboratories, hospitals, home-care settings, pharmaceutical and biotechnology companies, and research institutions.
Key Growth Drivers
- In-vitro diagnostics (IVD) are diagnostic tests performed on biological samples, such as blood, urine, and tissue, outside the human body to detect, diagnose, monitor, and manage diseases and health conditions. IVD products include instruments, reagents, and software used across various testing methods, including clinical chemistry, immunoassay, molecular diagnostics, hematology, microbiology, and coagulation. Advancements in diagnostic technologies are improving testing accuracy, sensitivity, specificity, automation, and turnaround time. The growing demand for early disease detection, point-of-care testing, personalized healthcare, and disease monitoring is further supporting the adoption of IVD solutions across diagnostic laboratories, hospitals, home-care settings, pharmaceutical and biotechnology companies, and research institutions.
- Rising prevalence of chronic and infectious diseases, including diabetes, cancer, cardiovascular diseases, and respiratory infections
- Growing adoption of point-of-care testing and rapid diagnostic solutions for faster clinical decision-making
- Technological advancements in molecular diagnostics, immunoassays, clinical chemistry, automation, and multiplex testing
- Increasing healthcare expenditure, expansion of diagnostic laboratories, and growing adoption of IVD solutions across hospitals and home-care settings
In Vitro Diagnostics Market Key Highlights
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
In Vitro Diagnostics Market Trends
The in-vitro diagnostics market is witnessing strong growth due to increasing demand for early disease detection, accurate diagnosis, disease monitoring, and personalized healthcare. The growing adoption of molecular diagnostics, immunoassays, clinical chemistry, point-of-care testing, and automated diagnostic systems, along with advancements in multiplex testing, digital diagnostics, and laboratory automation, is supporting market expansion. Key trends include increasing demand for rapid and decentralized testing, integration of automation and digital technologies, and growing applications of IVD solutions across a wide range of diseases and healthcare settings.
The rising adoption of IVD testing for infectious diseases, oncology, diabetes, cardiovascular diseases, autoimmune diseases, and other chronic conditions is creating new opportunities for market participants. In addition, increasing healthcare expenditure, growing diagnostic testing volumes, and continued investments in advanced diagnostic technologies are encouraging the development of faster, more sensitive, and more cost-effective testing solutions.
Increasing Demand for Early Disease Detection and Point-of-Care Testing
The growing prevalence of chronic and infectious diseases is increasing demand for early, accurate, and timely diagnosis. Point-of-care and rapid diagnostic tests enable faster clinical decision-making and are increasingly being adopted across hospitals, diagnostic laboratories, emergency settings, and home-care environments. Advances in portable diagnostic platforms and rapid testing technologies are further supporting decentralized testing and improving access to diagnostic services.
Growing Adoption of Advanced Molecular and Immunodiagnostic Technologies
Advancements in PCR, sequencing, isothermal nucleic acid amplification, immunoassays, chemiluminescence, and fluorescence-based technologies are improving the sensitivity, specificity, speed, and accuracy of diagnostic testing. The development of multiplex and automated testing platforms is enabling simultaneous detection of multiple biomarkers or pathogens, supporting applications across infectious diseases, oncology, cardiology, diabetes, and other therapeutic areas.
Key Players in the In Vitro Diagnostics Market
Leading companies in the in vitro diagnostics market are focusing on product innovation, advanced diagnostic technologies, strategic partnerships, research and development, product launches, geographic expansion, and technology development to strengthen their market presence.
Strategic Activities Within the In Vitro Diagnostics Market
Siemens Healthineers (Germany) launched a new core-lab capillary testing menu on its Atellica CH, IM, and CI analyzers following CE marking for 24 capillary blood testing claims. The launch expands the Atellica testing portfolio and enables laboratories to perform a broader range of tests, including metabolic, lipid, thyroid, Vitamin D, and HbA1c testing using capillary samples.
Danaher Corporation (US) completed the acquisition of Masimo Corporation (US) for approximately US$9.9 billion, adding Masimo’s advanced sensor technology and AI-enabled patient monitoring capabilities to Danaher’s Diagnostics segment. The acquisition strengthens Danaher’s diagnostics portfolio and expands its capabilities in acute-care settings.
Roche (Switzerland) entered into a definitive agreement to acquire PathAI (US), a company specializing in AI-powered digital pathology. The acquisition is intended to strengthen Roche’s digital pathology capabilities, improve laboratory workflow efficiency, and advance AI-enabled companion diagnostics and biomarker discovery.
In Vitro Diagnostics Market Insights
The global in-vitro diagnostics market is experiencing strong growth due to increasing demand for early disease detection, accurate diagnosis, disease monitoring, and personalized healthcare. Rising prevalence of chronic and infectious diseases, increasing healthcare expenditure, and advancements in diagnostic technologies are supporting market expansion. Developments in molecular diagnostics, immunoassays, clinical chemistry, point-of-care testing, automation, and multiplex testing are further creating growth opportunities for IVD market participants worldwide.
In-vitro diagnostics are widely used for the diagnosis, screening, monitoring, and management of infectious diseases, oncology, diabetes, cardiology, nephrology, autoimmune diseases, and other health conditions. Diagnostic laboratories and hospitals are the major end users, while home-care settings are increasingly adopting point-of-care and rapid diagnostic solutions. Pharmaceutical and biotechnology companies, research institutions, and healthcare providers are also increasingly using IVD technologies for clinical research, biomarker analysis, companion diagnostics, and disease monitoring.
Increasing demand for early and accurate disease detection is a major factor driving the in-vitro diagnostics market. Rising prevalence of chronic and infectious diseases, growing adoption of point-of-care testing, increasing healthcare expenditure, and expanding diagnostic testing volumes are accelerating market growth. Technological advancements in PCR, sequencing, immunoassays, chemiluminescence, clinical chemistry, and automated diagnostic platforms are further improving testing accuracy, speed, sensitivity, and scalability.
Key trends in the in-vitro diagnostics market include increasing adoption of molecular diagnostics, point-of-care testing, multiplex testing, automation, digital diagnostics, and personalized healthcare. Growing demand for rapid and decentralized testing, integration of artificial intelligence and digital technologies, and development of high-throughput diagnostic platforms are creating new opportunities across healthcare settings. However, the market faces challenges such as high instrument and development costs, stringent regulatory requirements, complex reimbursement processes, data management and cybersecurity concerns, and the need for specialized technical expertise.
The Asia-Pacific is expected to witness strong growth in the in-vitro diagnostics market due to increasing healthcare expenditure, expanding diagnostic infrastructure, growing pharmaceutical and biotechnology industries, and rising demand for advanced diagnostic technologies. China, Japan, South Korea, India, and other countries are contributing to regional growth through investments in healthcare infrastructure, molecular diagnostics, laboratory automation, and point-of-care testing. Rising disease burden, increasing diagnostic testing volumes, expanding healthcare access, and growing adoption of advanced diagnostic solutions are expected to further strengthen the IVD market across the region.
In Vitro Diagnostics Market Dynamics
Drivers: Increasing Demand for Early and Accurate Disease Diagnosis
The major driver of the in-vitro diagnostics market is the growing demand for early, accurate, and timely detection of diseases. The increasing prevalence of chronic and infectious diseases, including cancer, diabetes, cardiovascular diseases, respiratory infections, and autoimmune disorders, is supporting the adoption of advanced diagnostic solutions. In addition, growing healthcare expenditure, increasing diagnostic testing volumes, and rising adoption of personalized healthcare are accelerating market growth. Advancements in molecular diagnostics, immunoassays, clinical chemistry, point-of-care testing, and laboratory automation are further improving the accuracy, speed, and efficiency of diagnostic testing.
Opportunities: Expansion of Molecular Diagnostics, Point-of-Care Testing, and Personalized Healthcare
The increasing use of IVD technologies in disease screening, diagnosis, monitoring, companion diagnostics, and personalized healthcare is creating significant opportunities for market participants. Rising investments by diagnostic companies, pharmaceutical and biotechnology companies, hospitals, and research institutions are encouraging the development of innovative diagnostic products and platforms. In addition, growing adoption of molecular diagnostics, multiplex testing, rapid testing, and point-of-care technologies is expanding the application scope of IVD solutions.
Challenges: High Development Costs, Regulatory Complexity, and Technical Requirements
Despite strong growth potential, the in-vitro diagnostics market faces challenges such as high research and development costs, complex regulatory requirements, stringent quality standards, reimbursement limitations, and the need for specialized technical expertise. Maintaining diagnostic accuracy, sensitivity, specificity, reliability, and consistency can increase product development and manufacturing complexity. Market participants also need to address regulatory and quality requirements while improving testing efficiency, reducing costs, and ensuring reliable performance to support the broader adoption of advanced IVD solutions.
Technology and Market Insights
From a market perspective, the in-vitro diagnostics market is witnessing strong growth due to increasing demand for early disease detection, disease monitoring, point-of-care testing, and personalized healthcare. The growing adoption of IVD technologies across diagnostic laboratories, hospitals, home-care settings, pharmaceutical and biotechnology companies, and research institutions is driving investments in advanced diagnostic products, instruments, reagents, and software.
Continuous developments in clinical chemistry, immunoassays, molecular diagnostics, hematology, microbiology, coagulation, automation, multiplex testing, and digital diagnostics are improving testing accuracy, sensitivity, specificity, speed, and scalability. These innovations are enabling market participants to develop advanced and reliable diagnostic solutions while supporting wider adoption across infectious diseases, oncology, cardiology, diabetes, nephrology, autoimmune diseases, and other therapeutic areas.
Technology Scope and Products
In Vitro Diagnostics Market Segmentation
Want detailed insights from this report?
Industry Developments and Competitive Landscape
The in-vitro diagnostics market is witnessing continuous technological advancements driven by growing demand for early disease detection, accurate diagnosis, disease monitoring, and personalized healthcare. IVD companies are investing in advanced diagnostic instruments, reagents, molecular testing, immunoassays, automation, multiplex testing, and point-of-care technologies to improve testing accuracy, sensitivity, speed, and efficiency. The integration of laboratory automation, digital technologies, artificial intelligence, and advanced molecular diagnostic platforms is further supporting market growth by enabling reliable, scalable, and high-throughput diagnostic solutions and meeting the evolving requirements of hospitals, diagnostic laboratories, pharmaceutical and biotechnology companies, and home-care settings.
The reagents and kits segment held the largest revenue share of approximately 70% in 2025, supported by their essential role in performing diagnostic tests across clinical chemistry, immunoassay, molecular diagnostics, hematology, microbiology, and coagulation. Reagents and kits are continuously consumed during diagnostic testing, resulting in recurring demand across diagnostic laboratories and hospitals. Increasing testing volumes, rising prevalence of chronic and infectious diseases, and growing adoption of molecular and immunodiagnostic technologies are further supporting segment growth. In addition, advancements in multiplex testing, automated assay systems, and highly sensitive reagents are enabling faster and more accurate diagnosis, contributing to the strong market position of the reagents and kits segment.
The molecular diagnostics segment is projected to register the highest CAGR of approximately 14.7% during the forecast period, driven by increasing demand for highly sensitive and specific diagnostic testing. Molecular diagnostic technologies such as PCR, sequencing, isothermal nucleic acid amplification, in-situ hybridization, and other nucleic acid-based techniques enable the detection of pathogens, genetic abnormalities, biomarkers, and disease-associated mutations at the molecular level. Growing applications in infectious disease testing, oncology, genetic testing, and personalized medicine, along with advancements in multiplex molecular testing, automation, and rapid molecular platforms, are expected to further accelerate segment growth.
The infectious disease segment accounted for the largest market share in 2025, supported by the continued global burden of infectious diseases and the increasing demand for rapid, accurate, and early diagnosis. IVD technologies are widely used to detect bacterial, viral, fungal, and parasitic infections across hospitals, diagnostic laboratories, and point-of-care settings. Increasing adoption of molecular diagnostics, immunoassays, rapid diagnostic tests, and multiplex testing is improving pathogen identification and supporting timely clinical decision-making. In addition, continued surveillance of infectious diseases and the need for rapid outbreak detection are expected to sustain demand for IVD solutions in this application segment.
North America accounted for the largest revenue share of approximately 39% of the global in-vitro diagnostics market in 2025, supported by advanced healthcare infrastructure, high diagnostic testing volumes, significant healthcare expenditure, and the presence of leading IVD companies. The region benefits from strong adoption of advanced molecular diagnostics, immunoassays, clinical chemistry, laboratory automation, and point-of-care testing technologies. Increasing prevalence of chronic and infectious diseases, growing demand for early disease detection, and continued investments in innovative diagnostic technologies are further supporting regional market growth. In addition, the presence of major industry participants such as Danaher Corporation, Abbott, Thermo Fisher Scientific Inc., and Hologic, Inc. strengthens North America’s position as a leading market for in-vitro diagnostics.
What This Report Covers-
This report provides a comprehensive analysis of the in vitro diagnostics market, offering insights into key trends, growth drivers, challenges, and future opportunities. It is designed to support strategic decision-making through a combination of quantitative data and qualitative analysis.
Specifically, the report covers:

Market Overview & Definition:
Overview of the market scope, structure, and key terminology

Market Size & Forecast:
Historical data and future projections across key segments and regions

Key Market Trends:
Insights into emerging trends, technological advancements, and evolving demand patterns

Drivers, Restraints & Opportunities:
Analysis of key factors influencing in-vitro diagnostics market growth

Competitive Landscape:
Overview of major players, their strategies, and recent developments

Detailed Patent Analysis:
This includes, top assignees, geography focus of top assignees, legal status, technology evolution, key patents and patent trends and innovations

Segmentation Analysis:
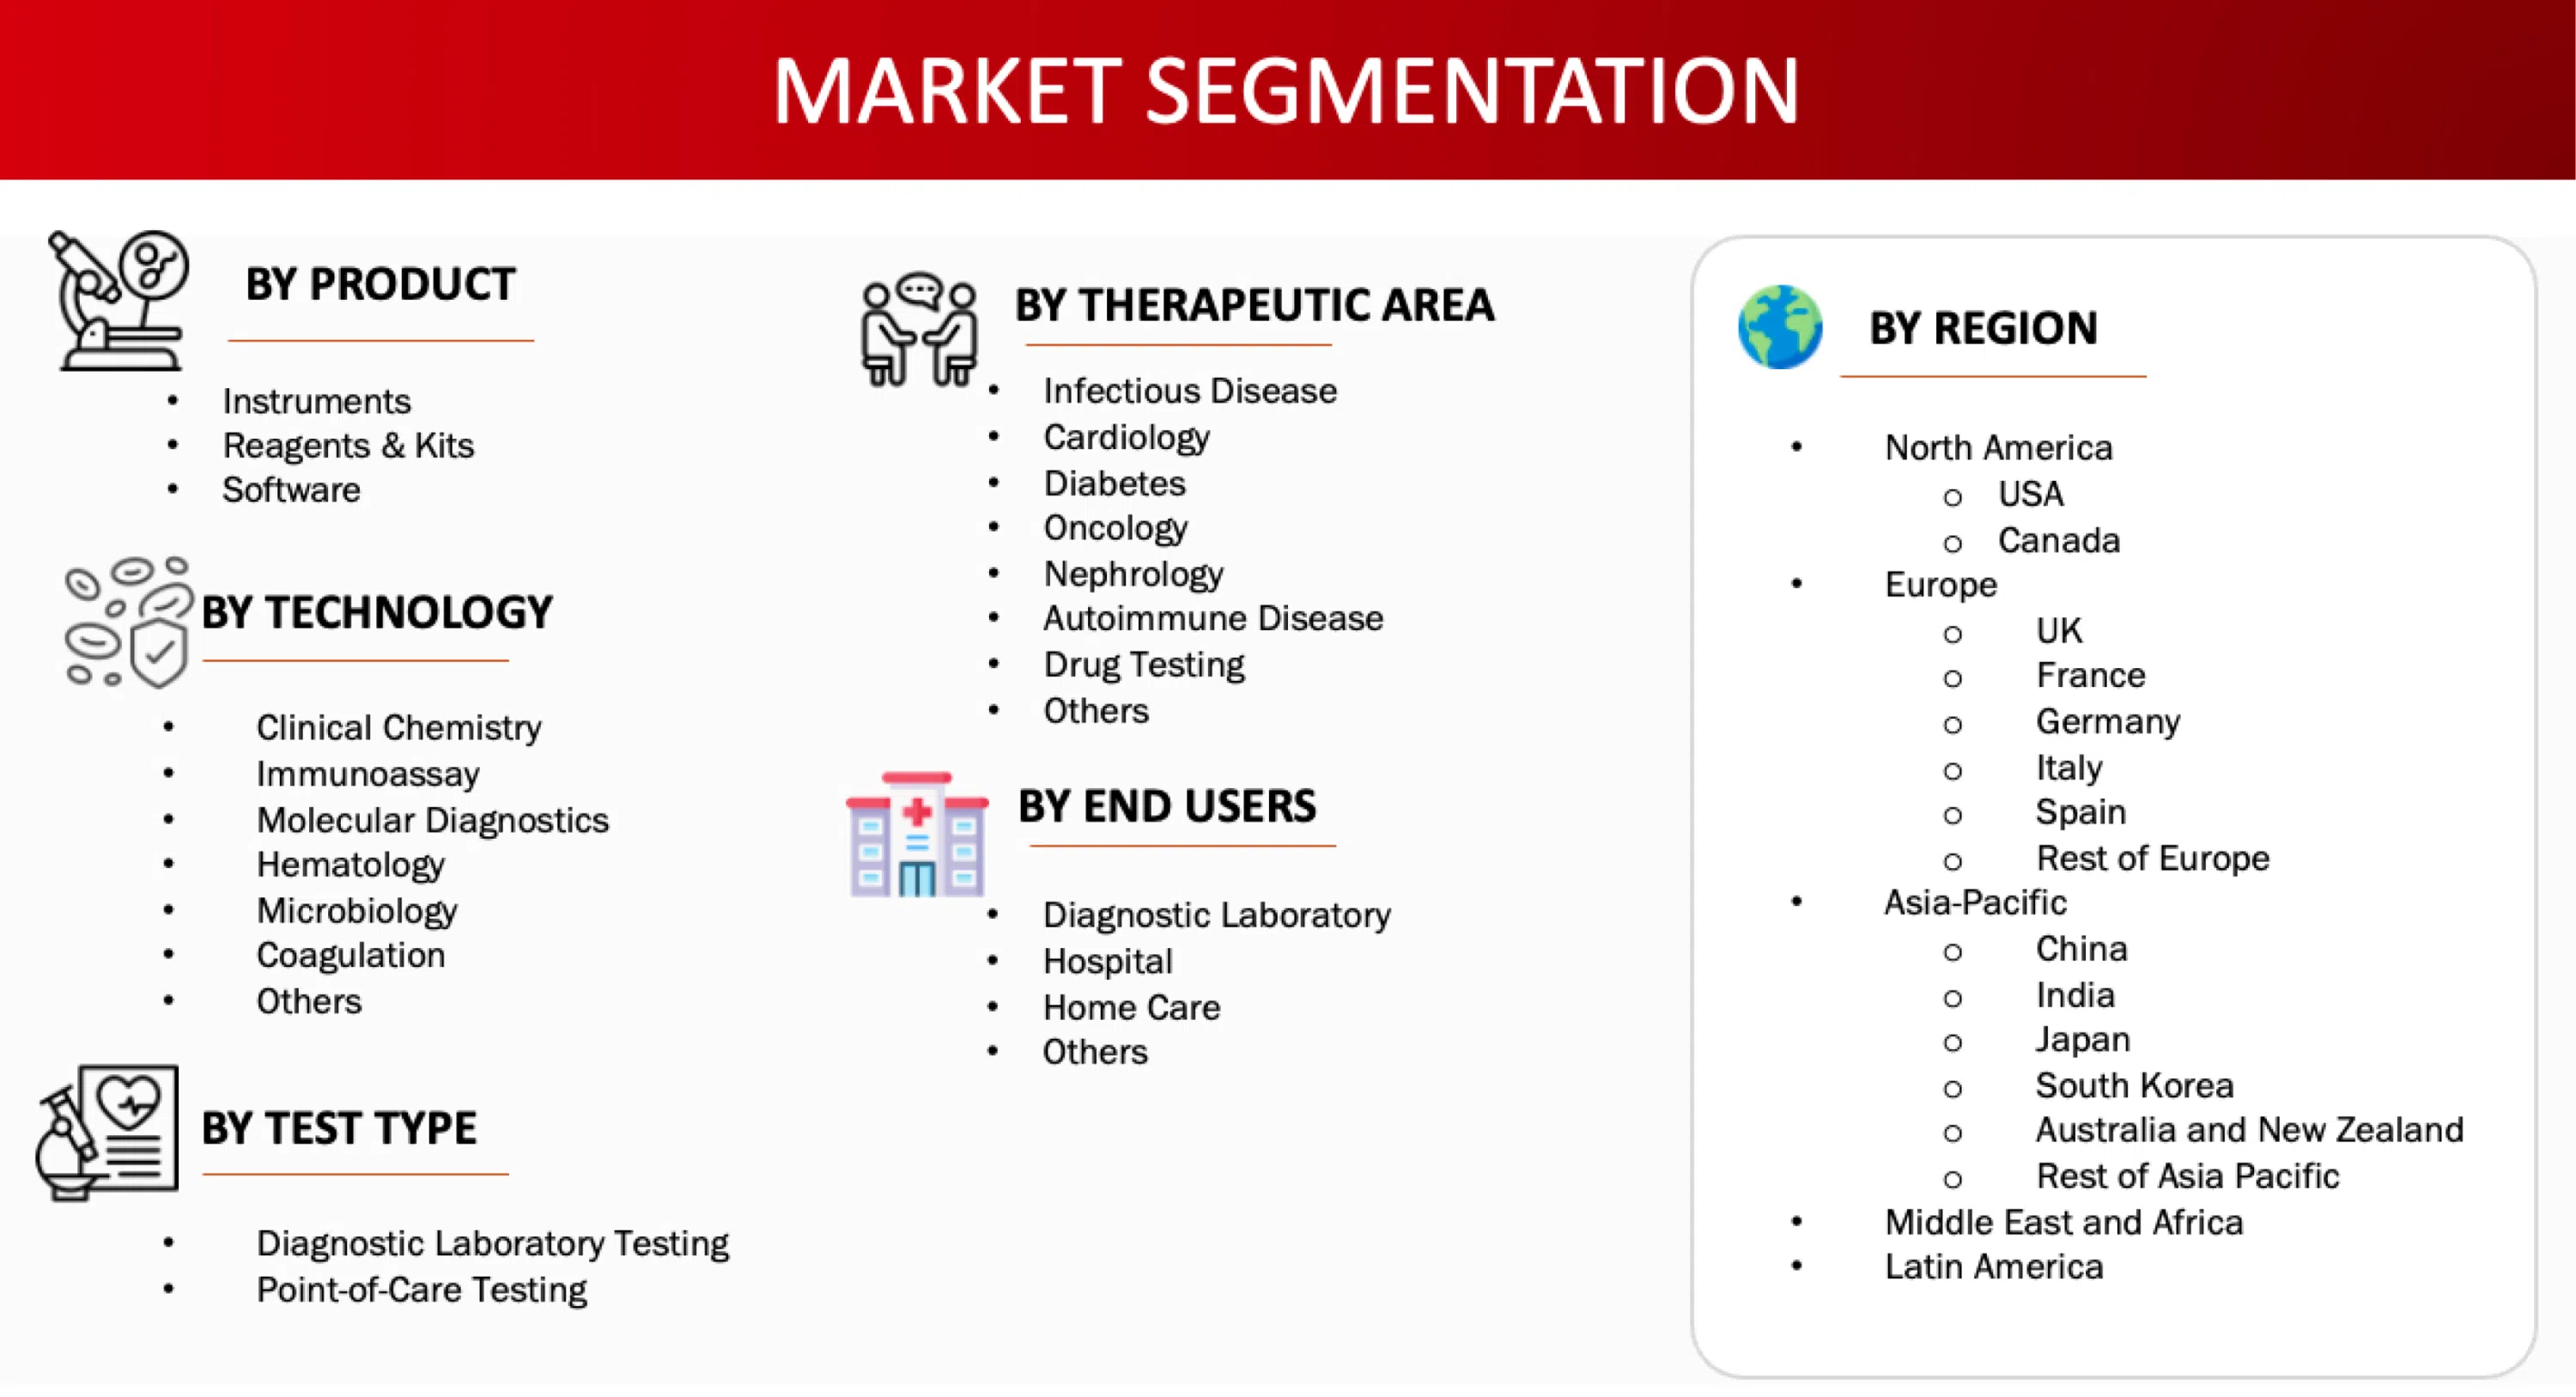
Breakdown by product, test type, technology, therapeutic area, end-user, and region

Regional Insights:
Key regional trends and growth opportunities

Future Outlook:
Strategic insights and future market direction
Research Methodology
The analysis of the in-vitro diagnostics market is based on a combination of primary and secondary research approaches, complemented by data validation and analytical assessment to ensure the accuracy, consistency, and reliability of market findings.
Market Definition: In-Vitro Diagnostics Market
The in-vitro diagnostics (IVD) market refers to the development, production, and supply of diagnostic products and technologies used to analyze biological samples outside the human body for the detection, diagnosis, screening, monitoring, and management of diseases and health conditions. IVD solutions include diagnostic instruments, reagents, and software used across clinical chemistry, immunoassay, molecular diagnostics, hematology, microbiology, and coagulation testing.
Modern IVD technologies incorporate advanced testing, automation, multiplexing, molecular analysis, and digital diagnostic capabilities to improve testing accuracy, sensitivity, specificity, speed, and efficiency. Key technology categories include metabolic, electrolyte, liver, lipid, and renal panels under clinical chemistry; ELISA, chemiluminescence, fluorescence immunoassay, rapid tests, and ELISPOT under immunoassay; PCR, sequencing, isothermal nucleic acid amplification, in-situ hybridization, chips and microarrays, and mass spectrometry under molecular diagnostics; as well as hematology, microbiology, and coagulation technologies. IVD solutions are used across diagnostic laboratories, hospitals, and home-care settings for applications including infectious diseases, oncology, cardiology, diabetes, nephrology, autoimmune diseases, and drug testing.
Key Stakeholders
The in vitro diagnostics market involves a diverse ecosystem of stakeholders:
- Diagnostic Technology Developers
- IVD Instrument Manufacturers
- IVD Reagent and Consumables Manufacturers
- Molecular Diagnostics and Genomics Companies
- Immunoassay and Clinical Chemistry Technology Providers
- Point-of-Care Diagnostic Companies
- Pharmaceutical and Biotechnology Companies
- Hospitals and Healthcare Providers
- Diagnostic Laboratories
- Academic and Research Institutions
- Clinical Research Organizations
- Regulatory and Government Organizations
- Investors and Industry Associations
Key Objectives of the Study
- To define, describe, analyze, segment, and forecast the in-vitro diagnostics market by product, test type, technology, therapeutic area, and end-user
- To describe and forecast the market for four key regions: North America, Europe, Asia Pacific, and Rest of the World
- To provide detailed information regarding key drivers, restraints, opportunities, and challenges influencing market growth
- To strategically analyze the micro indicators with respect to individual growth trends, prospects, and contributions to the overall market size
- To analyze opportunities for stakeholders in the in-vitro diagnostics industry and emphasize the competitive landscape of the market
- To develop competitive benchmarking of key market players based on technology specifications, product offerings, and end-user applications
- To strategically profile key players and comprehensively analyze their product portfolio offerings, technological capabilities, and core competencies
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
Research Approach
This research employs a systematic approach by using primary research along with secondary research to achieve full coverage and accuracy of information about the in-vitro diagnostics sector. Through this approach, the current market trends in terms of consumer behavior, technological developments, and competitive environment can be analyzed thoroughly.
Secondary Research
Secondary research involves the collection of data from reliable sources such as industry databases, company annual reports, investor presentations, and regulatory filings. This process helps in understanding market trends, identifying key players, and gathering technical and commercial insights.
A comprehensive database of leading companies and market participants is developed through secondary research to support further analysis.
Primary Research
Primary research is conducted to validate findings from secondary research and to gain deeper insights into market dynamics. Interviews are carried out with industry stakeholders across both demand and supply sides, including executives such as CXOs, Vice Presidents, and Directors from business development, marketing, and product teams.
Data is collected through structured questionnaires, email interactions, and telephonic interviews across key regions including North America, Europe, Asia-Pacific, and Rest of the World.
Market Size Estimation
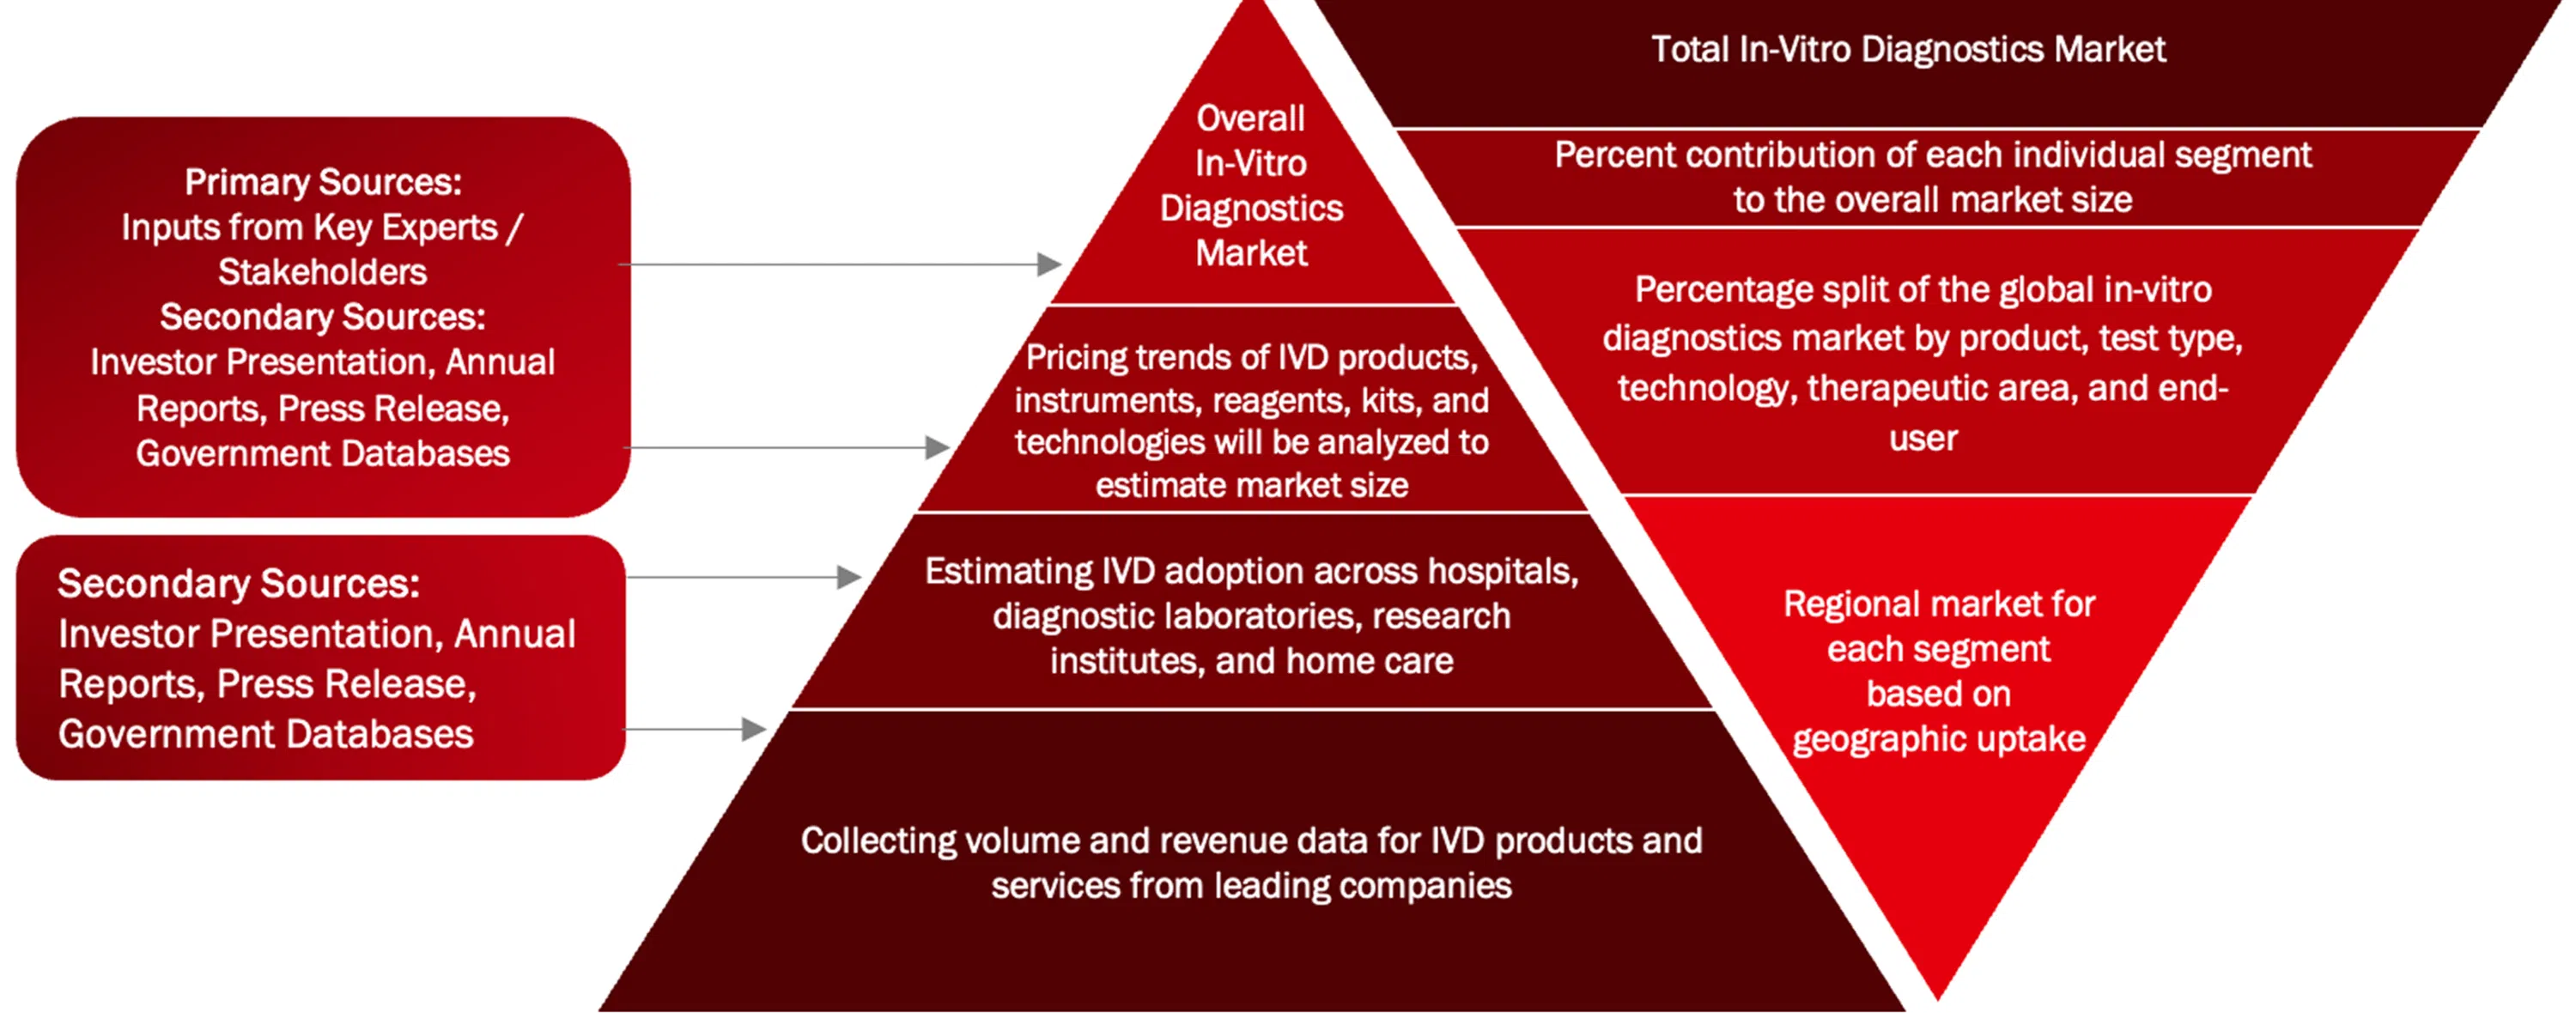
Market size estimation is performed using both top-down and bottom-up approaches. Key market players are identified, and their revenues are analyzed to estimate the overall market size.
The market is further segmented based on:
- Product and service mapping across regions
- Adoption patterns across key application segments
- Insights gathered through primary and secondary research
Data Validation and Research Design
After estimating the overall market size, the data is validated using triangulation methods and market breakdown techniques to ensure accuracy and consistency. Both demand-side and supply-side factors are considered to refine the analysis.
The final data is validated through multiple sources to ensure reliability and to provide accurate insights across all market segments and regions.
Assumptions of the Study
The analysis of the in vitro diagnostics market is based on the following key assumptions:
- Trends in the industry are drawn from historical data and current information within the in vitro diagnostics sector
- The future outlook is underpinned by constant economic conditions in the absence of major shocks to the market
- The adoption rate of in-vitro diagnostic technologies will rise steadily across all important regions
- Advancements in molecular diagnostics, immunoassays, clinical chemistry, point-of-care testing, automation, multiplex testing, and digital diagnostics will continue to drive growth in the in-vitro diagnostics market
- Market size and market share figures are estimated using available information from the industry and publicly available data
- The regulatory environment, healthcare expenditure, diagnostic testing volumes, reimbursement conditions, and pricing trends for IVD products and technologies will not be significantly disrupted during the forecast period
Scope and Limitations
Scope of the Study
This report offers an exhaustive overview of the international in vitro diagnostics market and includes the following components:
- Summary of market size, growth trends, and projections
- Carefully segmented market based on product, test type, technology, therapeutic area, end-user, and geography
- Discussion of primary factors influencing the market
- Competitor analysis
- Insights into regional and national market performance
Limitations of the Study
Despite the best efforts being made to keep the results accurate, the study does suffer from some limitations:
- It has been done using both primary and secondary data that come with their own constraints
- Rapid developments in technology might affect the future course of market dynamics
- Some figures are only approximations due to lack of public disclosure
- The report is not an insurance against any disruptions in macroeconomics and geopolitics
- Future forecasts are indicative and subject to change due to altered industry dynamics
Data Triangulation and Market Breakdown
Data triangulation involved the combination of primary research, secondary research, and the Wissen Research analysis. Once the data points were sourced from the secondary market research, we sanitized the data points to make the market sizing and growth forecast more accurate by developing our own assumptions based on the inputs and insights we gather through the primary interviews with the industry experts. Once the data was thoroughly validated through primary interviews from both, demand and supply side of the market, our team of analyst and other team members involved finalized the market sizing and growth forecast.
Data Triangulation Methodology
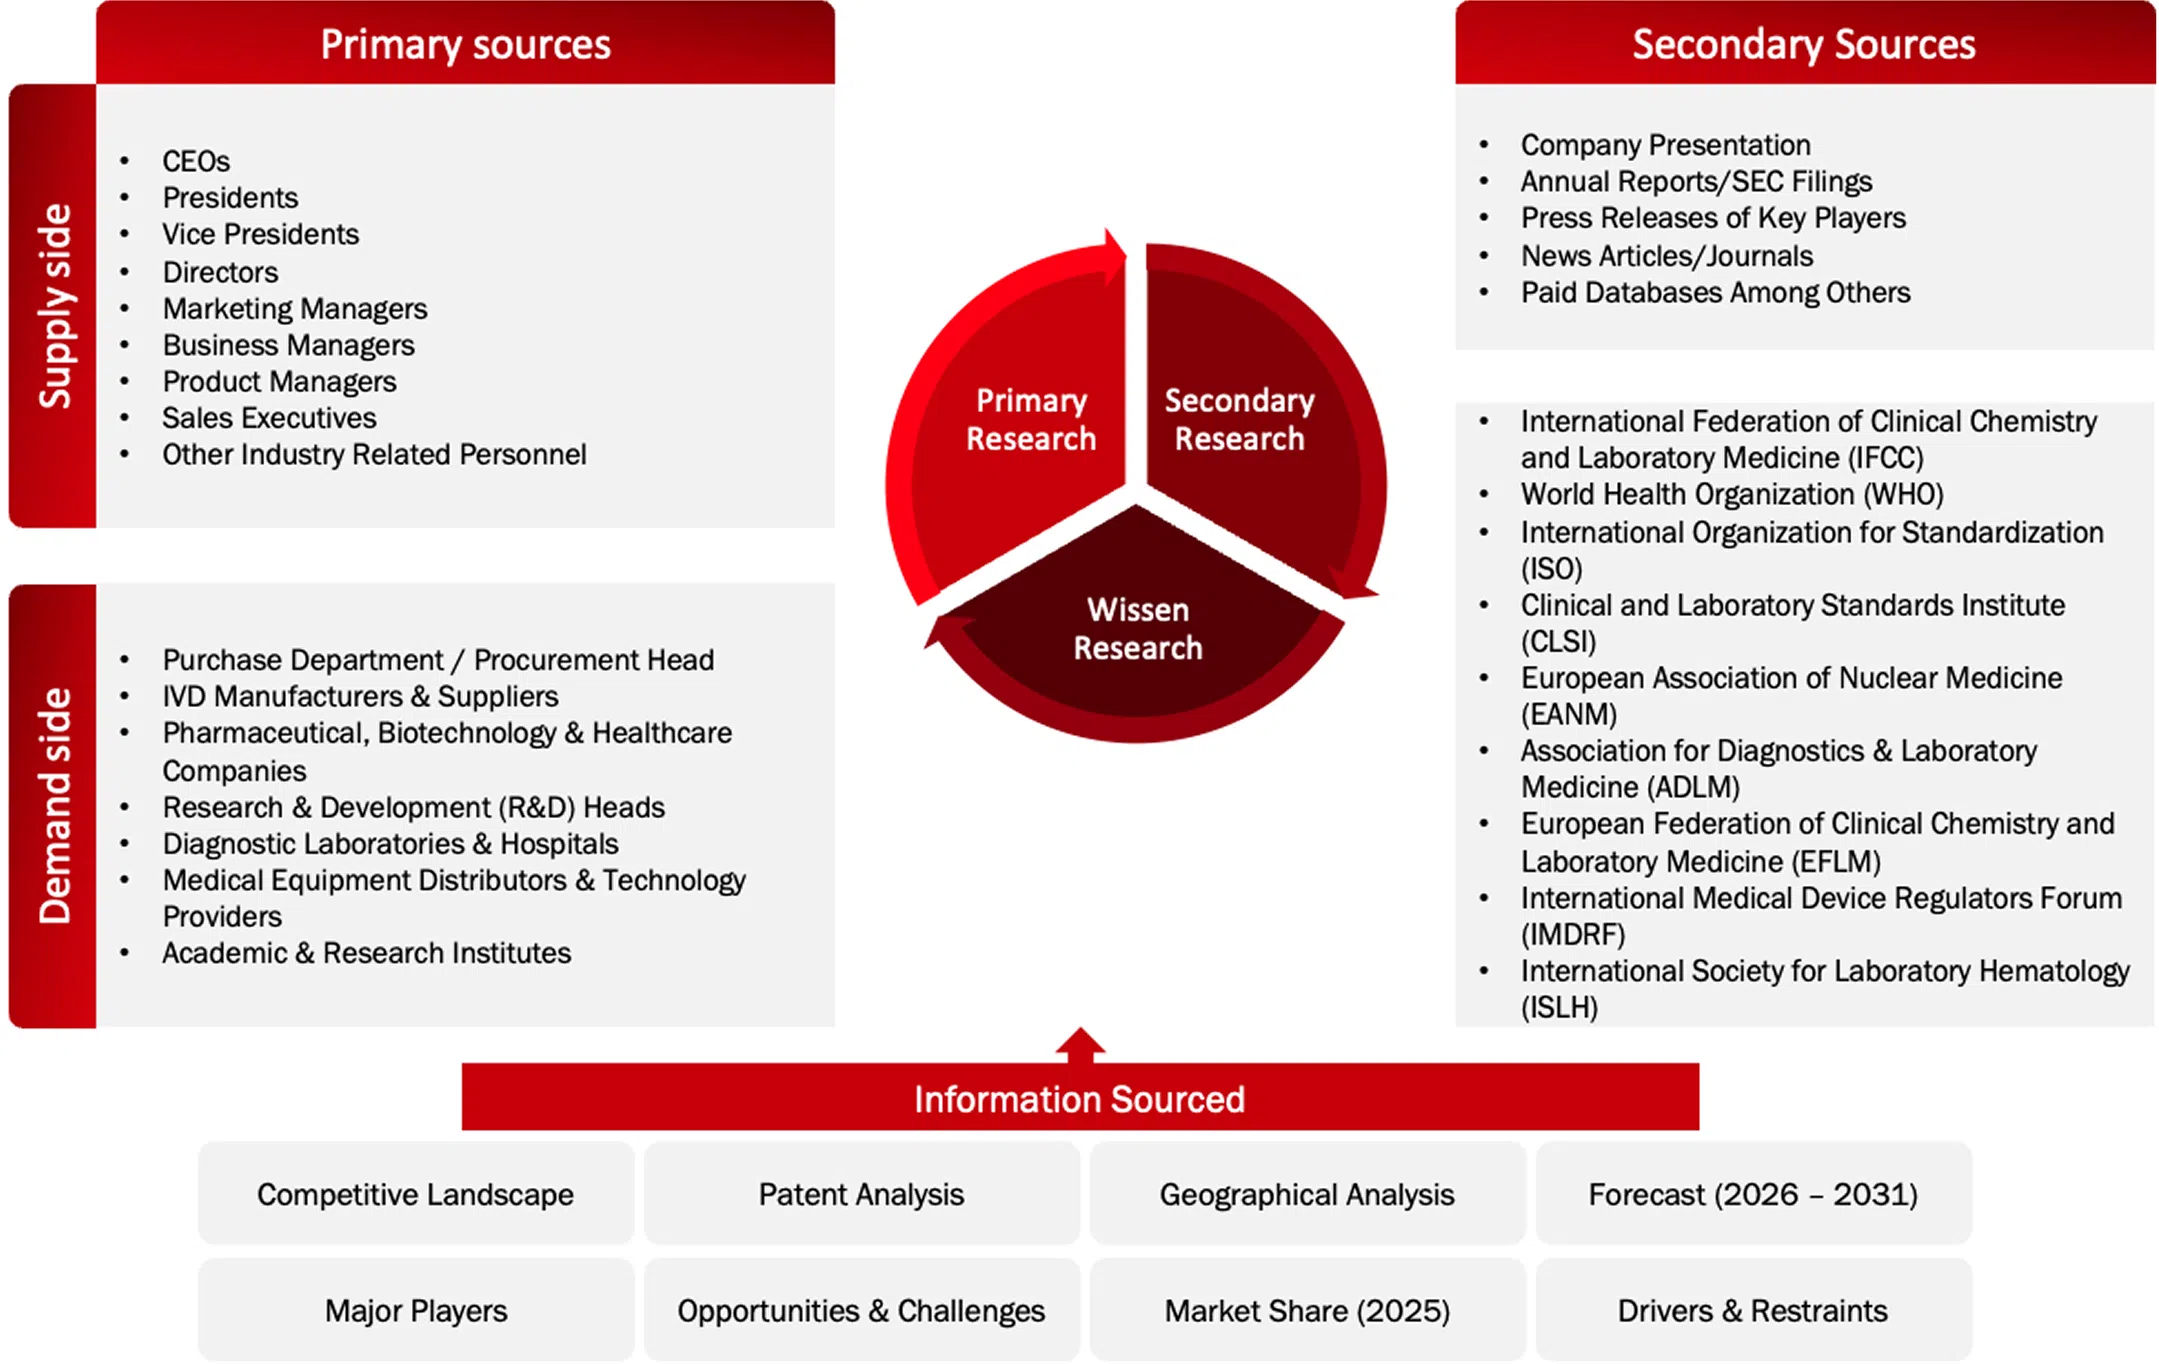
Sources: U.S. Food and Drug Administration, European Medicines Agency, National Institute of Standards and Technology, International Organization for Standardization, International Electrotechnical Commission, Federal Communications Commission, Occupational Safety and Health Administration, American National Standards Institute, Device Coordination Group, Company Website, Press Releases, Annual Reports, Paid Data Sources, and Wissen Research Analysis.
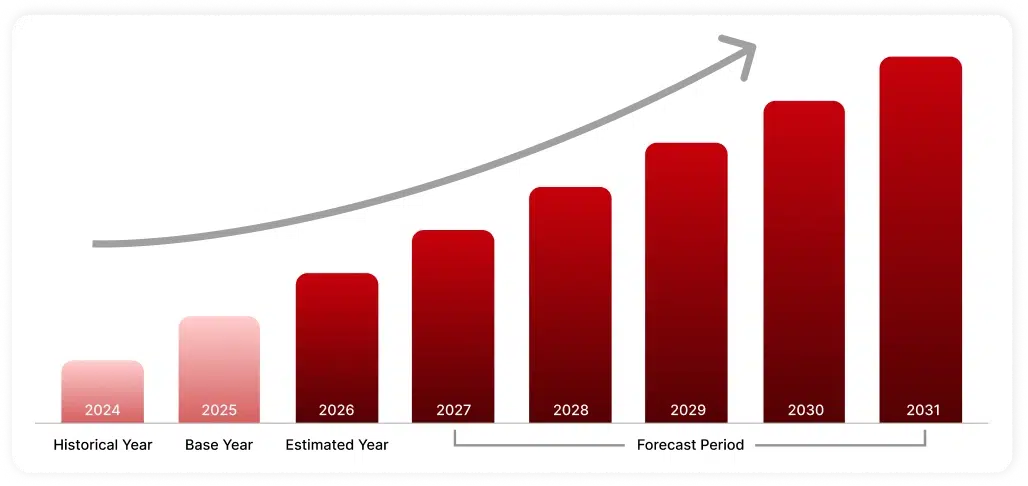
Year Framework
Bottom-Up Approach (Demand Side) And Top-Down Approach (Supply Side)
Bottom-Up Approach (Demand-Side Approach):
Determining the market size through the consolidation of demand among end-users, sectors, and geographic areas, which are calculated according to real-world demand conditions.
Top-Down Approach (Supply-Side Approach):
Calculating the market size through revenue and performance of the industry and its important companies, allocating the market size among various sectors.
Want detailed insights from this report?
Buy this Report
Choose the option that best fits your needs


