Respiratory Care Devices Market
Global Industry analysis, Size, Share, Growth, Trends, and Forecast 2026-2031
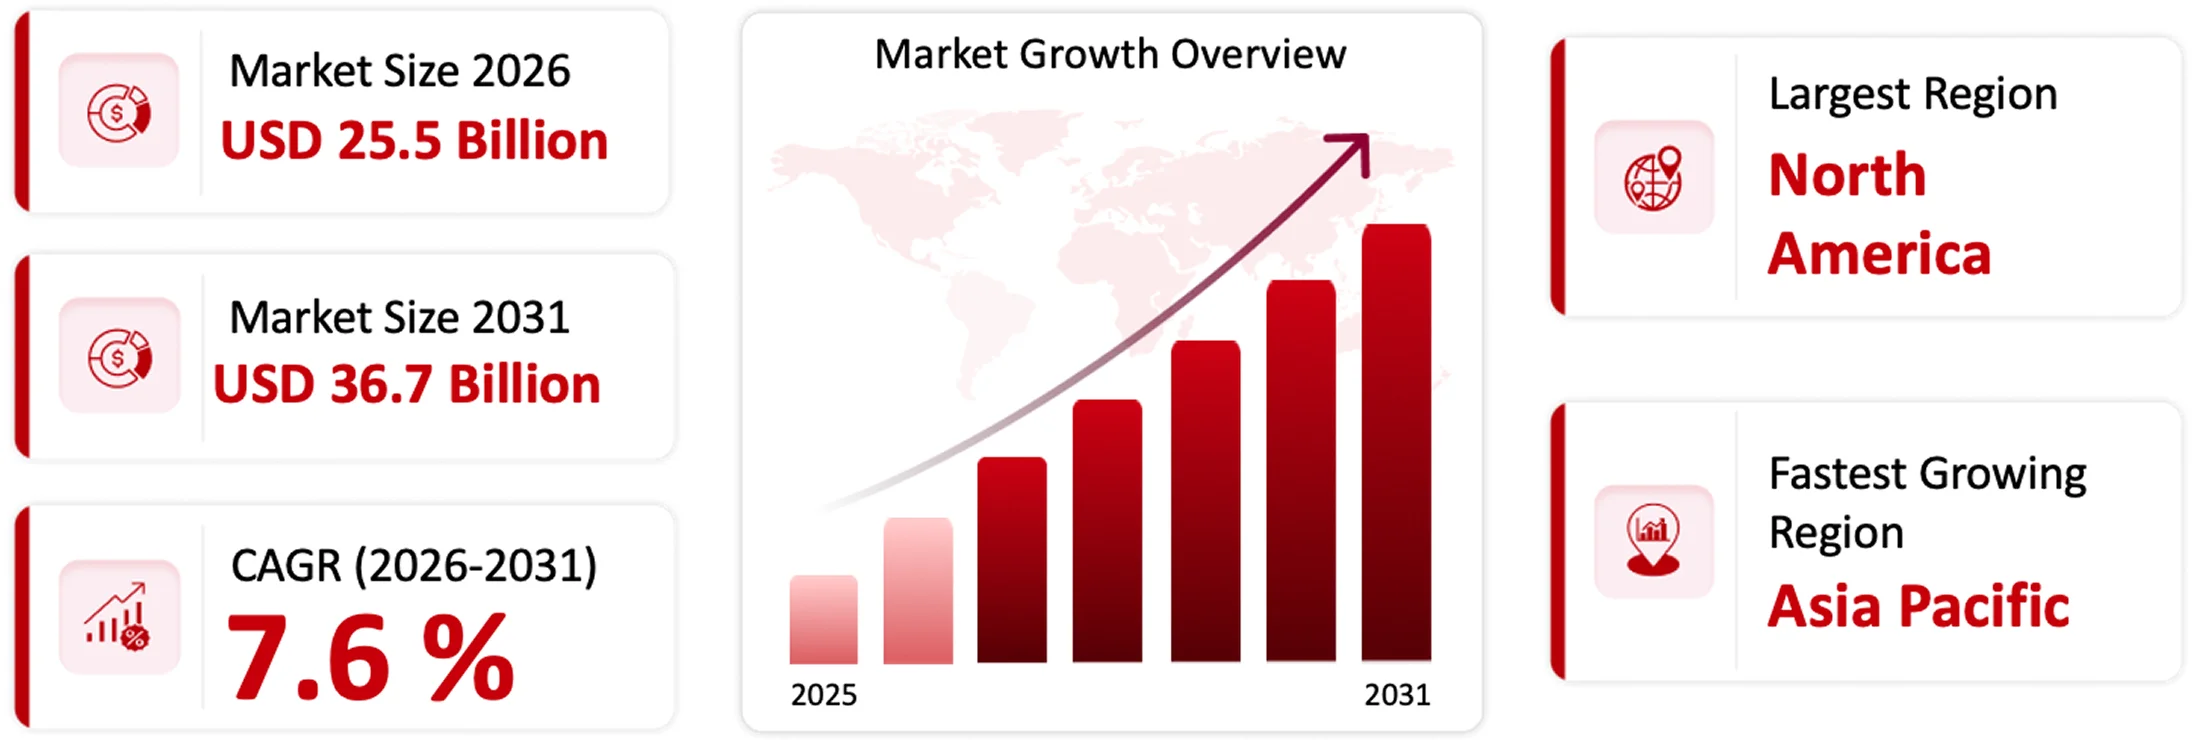
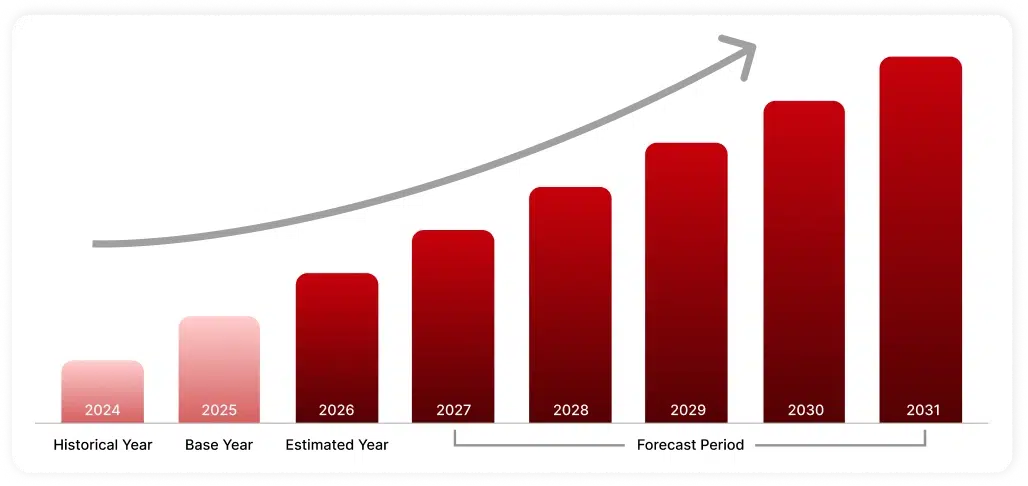
The global respiratory care devices market is projected to reach USD 36.7 billion by 2031, growing at a CAGR of 7.6% during the forecast period.
| Market Size (2026): | Forecast (2031): | CAGR (2026–2031): | Leading Region: | Fastest Growing Region: |
|---|---|---|---|---|
| $ 25.5 Billion | $ 36.7 Billion | 7.6 % | North America | Asia Pacific |
Summarize this report with:


Market Overview
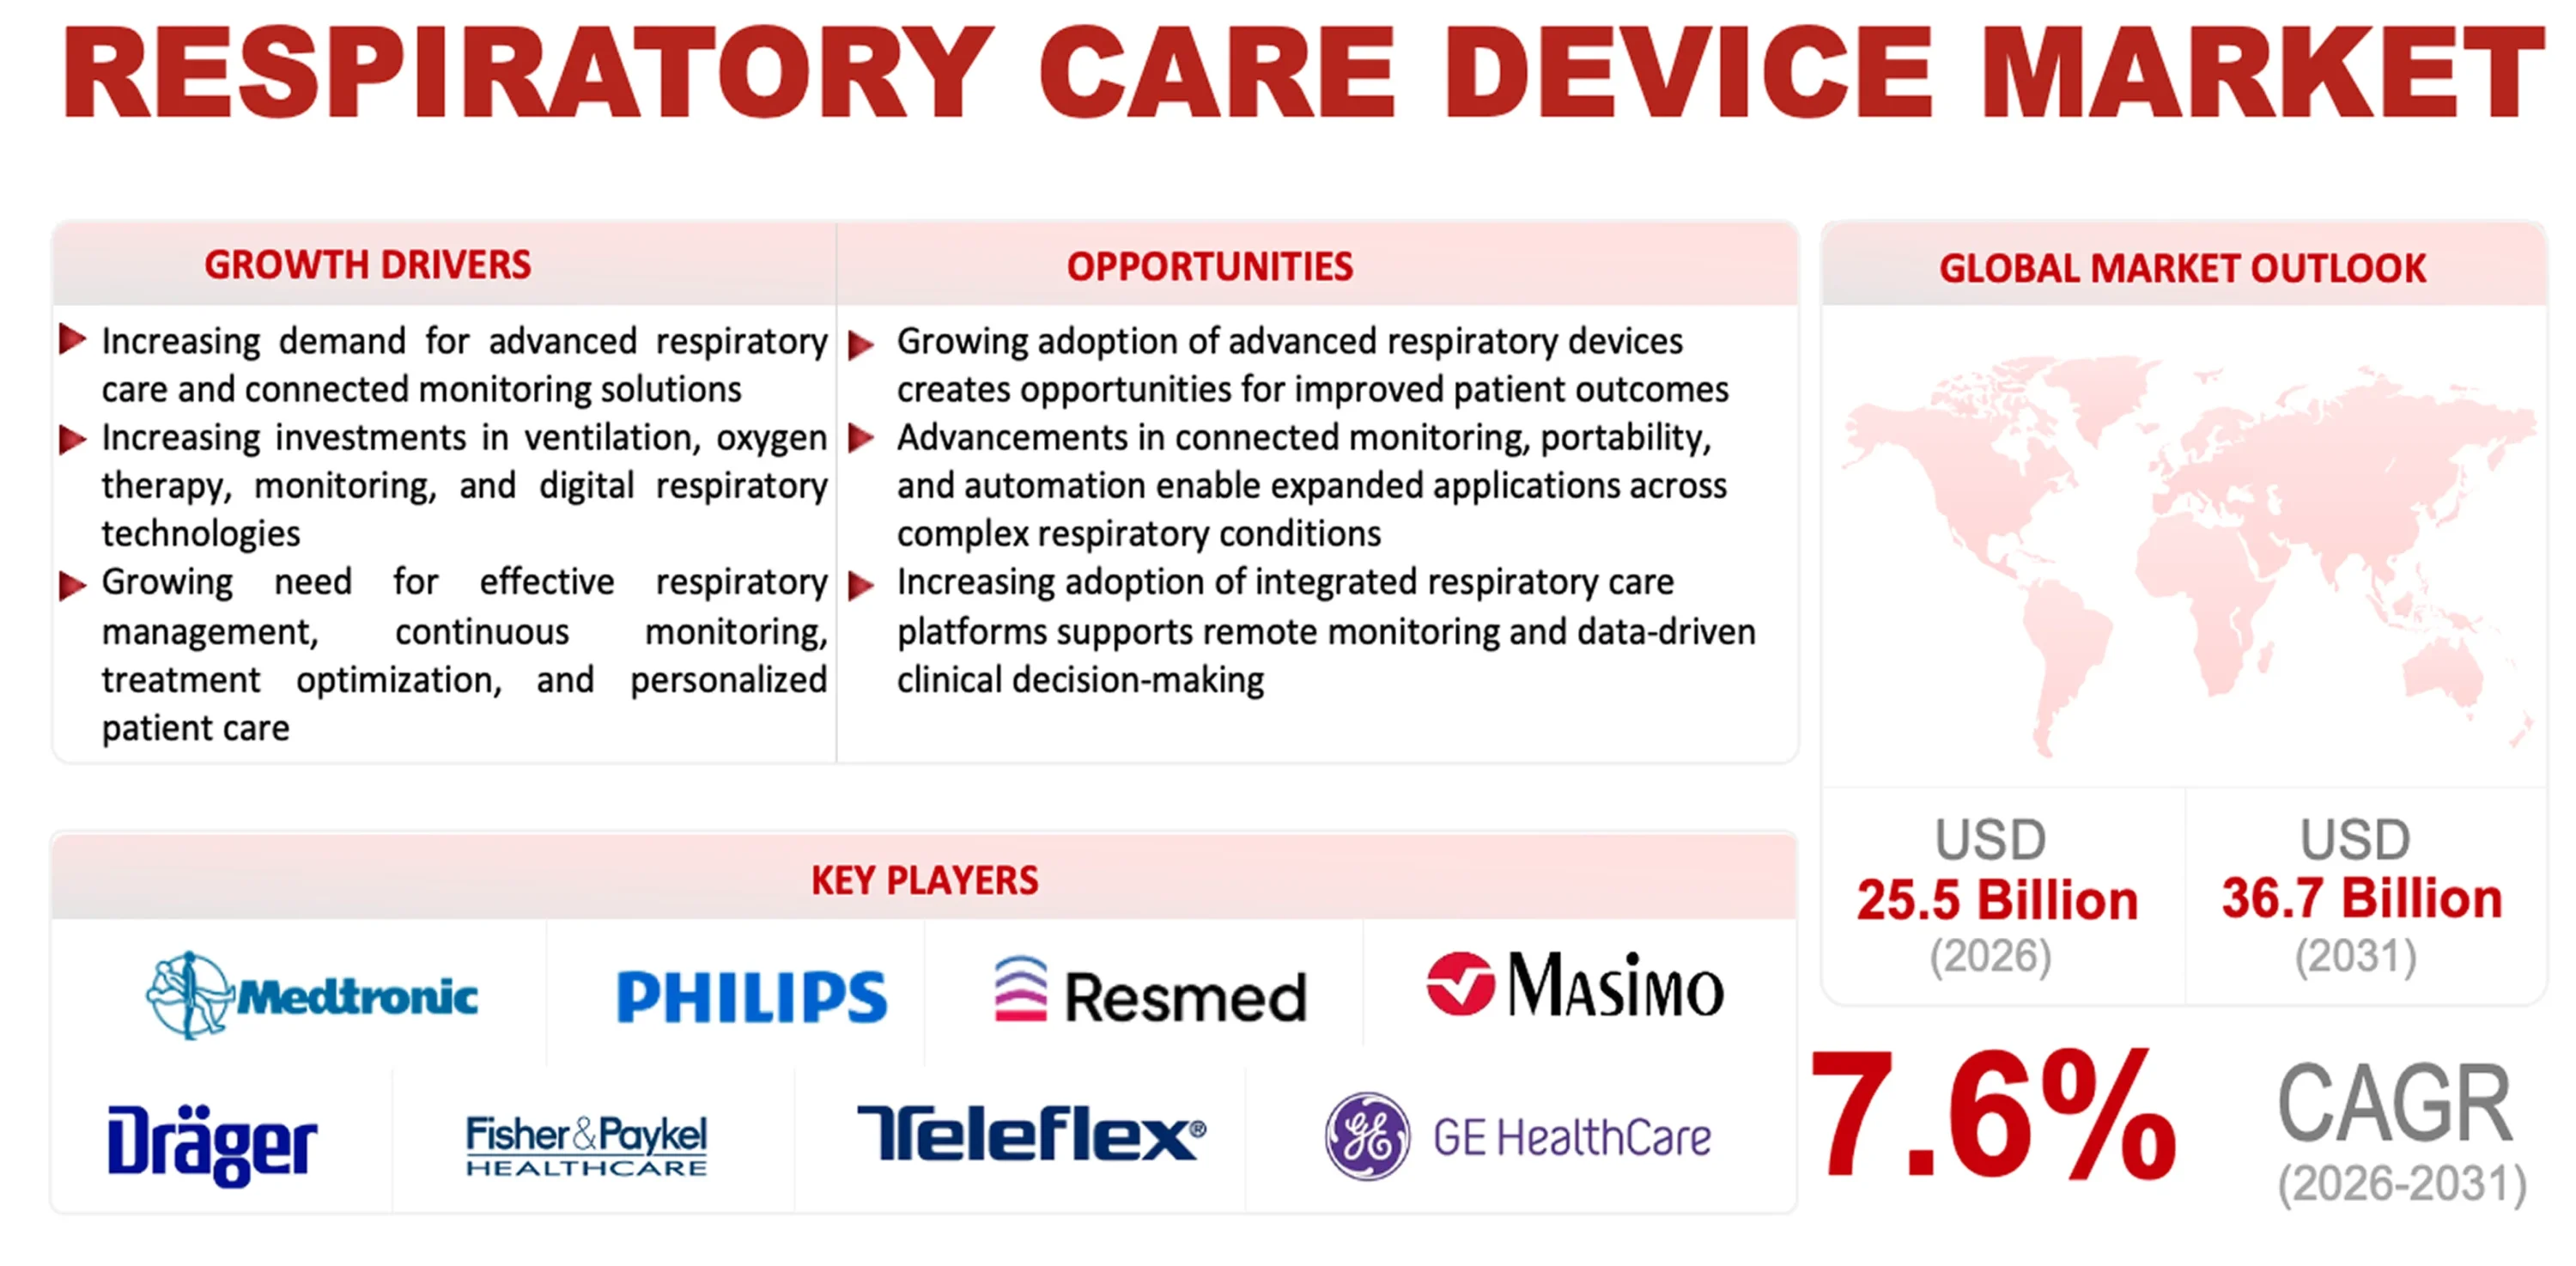
The respiratory care devices market is witnessing sustained demand for technologies that support the diagnosis, monitoring, treatment, and management of acute and chronic respiratory conditions. Respiratory care devices are increasingly used across hospitals, intensive care units, emergency departments, specialty clinics, ambulatory facilities, sleep centers, and home healthcare settings. The market is supported by the growing burden of chronic respiratory diseases, including chronic obstructive pulmonary disease (COPD), asthma, and sleep apnea, as well as increasing demand for respiratory support among aging populations. The World Health Organization estimates that COPD caused approximately 3.4 million deaths globally in 2023, while asthma affected an estimated 363 million people in the same year. The market is estimated to be USD 25.5 billion in 2026 and is projected to reach USD 36.7 billion by 2031, growing at a CAGR of 7.6 % during the forecast period (2026-2031).
Technology Overview
Respiratory care technologies encompass a broad range of medical devices designed to support breathing, deliver oxygen or respiratory therapies, diagnose pulmonary conditions, and monitor respiratory function. The technology landscape includes therapeutic devices such as ventilators, CPAP and BiPAP systems, oxygen concentrators, nebulizers, high-flow oxygen systems, and other respiratory support equipment. Diagnostic and monitoring technologies include spirometers, peak flow meters, pulse oximeters, capnography systems, and other devices used to evaluate respiratory performance and monitor patients.
Modern respiratory care technologies increasingly incorporate non-invasive ventilation, portable oxygen delivery, digital connectivity, remote monitoring, automated therapy adjustment, and data-driven patient management. In home healthcare, connected PAP devices can transmit therapy and adherence information to healthcare providers, while newer ventilatory and oxygen therapy systems increasingly emphasize portability, patient comfort, and ease of use. FDA-recognized respiratory device categories include continuous ventilators, BiPAP/BPAP systems, and CPAP machines used in both clinical and home settings.
Key Growth Drivers
- The rising burden of chronic respiratory diseases such as COPD and asthma increases the need for long-term respiratory therapy, oxygen support, pulmonary monitoring, and disease-management devices. WHO estimates that asthma and COPD together affect more than half a billion people globally.
- The growing prevalence of sleep apnea is increasing demand for positive airway pressure devices, particularly CPAP and BiPAP systems, as healthcare providers increasingly emphasize diagnosis and long-term management of sleep-related breathing disorders.
- The aging global population and increasing prevalence of comorbidities are expanding the population requiring respiratory support, particularly for COPD, respiratory failure, sleep-disordered breathing, and other chronic pulmonary conditions.
- Increasing adoption of home-based respiratory care is shifting selected respiratory therapies beyond hospitals toward home healthcare settings, supported by portable oxygen concentrators, PAP devices, connected monitoring systems, and remote therapy-management platforms.
- Persistent gaps in access to medical oxygen and respiratory equipment, particularly in low- and middle-income countries, create additional demand for oxygen concentrators, oxygen-delivery systems, ventilators, and related respiratory equipment. WHO notes that fewer than half of health facilities surveyed in some LMIC settings had uninterrupted access to oxygen.
- Technological advances in connected and non-invasive respiratory care devices are improving patient monitoring, therapy personalization, device usability, and remote management. Companies are increasingly incorporating digital connectivity and automated algorithms into respiratory equipment.
Respiratory Care Devices Market Key Highlights
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
Respiratory Care Devices Market Trends
The respiratory care devices industry is moving beyond conventional hospital-based respiratory support toward non-invasive, connected, portable, and home-based respiratory management. Healthcare systems are dealing with a growing burden of chronic respiratory diseases while seeking to reduce hospital utilization and improve long-term disease management. This is increasing demand for devices that can provide effective respiratory support while allowing greater patient mobility and enabling healthcare professionals to monitor therapy outside traditional clinical environments.
Increasing Adoption of Non-Invasive Respiratory Support
Non-invasive respiratory support is becoming increasingly important across both acute and chronic respiratory care. CPAP and BiPAP devices provide positive airway pressure without requiring invasive airway access and are used extensively in sleep apnea and selected respiratory-support applications. Ventilatory support is also increasingly complemented by high-flow nasal oxygen and other non-invasive approaches, particularly where clinicians seek to provide respiratory support while reducing the need for invasive ventilation.
The broader shift toward non-invasive treatment is supported by demand for greater patient comfort, reduced invasiveness, home-based treatment, and improved respiratory management. In North America, therapeutic respiratory devices including ventilators, CPAP/BiPAP systems, oxygen therapy equipment, and nebulizers represented the largest product category in 2025.
Growing Shift Toward Home-Based and Connected Respiratory Care
Respiratory care is increasingly extending from hospitals into home healthcare and other decentralized settings. Portable oxygen concentrators, CPAP/BiPAP devices, home ventilators, nebulizers, and connected monitoring technologies enable patients with chronic respiratory conditions to receive continuing therapy outside hospitals.
Connected respiratory devices are also creating opportunities for remote monitoring of therapy usage, adherence, leaks, respiratory parameters, and other patient information. For example, ResMed Inc. (U.S.) integrates connected device capabilities and cloud-based remote monitoring into its sleep and respiratory-care ecosystem. Its AirSense 11 platform includes digital features and over-the-air update capabilities, illustrating the industry’s movement toward connected respiratory therapy.
Key Players in the Respiratory Care Devices Market
Leading companies in the respiratory care devices market are focusing on non-invasive ventilation, oxygen therapy, sleep and breathing technologies, connected care, respiratory monitoring, and hospital-based respiratory support to strengthen their market positions.
Strategic Activities Within the Respiratory Care Devices Market
Nihon Kohden Corporation (Japan) upgraded its NKV-550 ventilator with non-invasive muscle pressure monitoring, Adaptive Ventilation Mode (AVM), and adjustable AdaptiveSync™ technology. The ventilator was manufactured in the U.S., strengthening Nihon Kohden’s respiratory ventilation portfolio and expanding its capabilities for patient-specific respiratory support.
Masimo Corporation (U.S.) received FDA 510(k) clearance for an AI-enabled opioid-induced respiratory depression detection capability on its Radius VSM wearable monitor. The technology analyzed continuous physiological data to identify respiratory risk earlier, expanding the use of continuous pulse oximetry and connected monitoring for hospital respiratory care.
Drägerwerk AG & Co. KGaA (Germany) received FDA 510(k) clearance for version 3.10 of its Evita V800 ventilator software. The clearance expanded the regulatory authorization for the ventilator platform and supported the company’s portfolio of advanced mechanical ventilation solutions for critical-care respiratory support.
Respiratory Care Devices Market Insights
The importance of respiratory care devices is increasing as healthcare systems manage a growing burden of chronic and acute respiratory conditions while shifting selected therapies toward home and outpatient settings. Respiratory care devices extend beyond basic respiratory support and include technologies for ventilation, oxygen therapy, positive airway pressure, aerosolized drug delivery, pulmonary function testing, and respiratory monitoring. These devices are used across intensive care, emergency care, hospitals, sleep centers, specialty clinics, ambulatory settings, and home healthcare. The market is supported by demand for long-term management of COPD, asthma, sleep apnea, respiratory failure, and other pulmonary conditions.
Respiratory care devices are used across a range of clinical applications where maintaining ventilation, oxygenation, airway patency, or respiratory function is required. COPD represents a major application area, supported by the need for long-term oxygen therapy, non-invasive ventilation, nebulization, and respiratory monitoring. Sleep apnea is another important application, particularly for CPAP and BiPAP/PAP devices used to maintain airway patency during sleep. Asthma management utilizes nebulizers, inhalation-related devices, and monitoring technologies, while acute respiratory failure and critical illness require ventilators, high-flow nasal cannula systems, oxygen therapy equipment, and patient monitoring. Respiratory care technologies are also used in pneumonia and other respiratory infections, perioperative care, neonatal and pediatric respiratory support, pulmonary function testing, and home-based chronic disease management. WHO identifies oxygen, ventilators, CPAP/BiPAP systems, high-flow nasal cannula systems, oxygen concentrators, and pulse oximeters as important components of respiratory and oxygen-care systems.
The increasing prevalence of chronic respiratory diseases, together with the need for continuous monitoring and long-term respiratory therapy, is one of the principal factors supporting market growth. COPD alone caused approximately 3.4 million deaths globally in 2023, while asthma affects hundreds of millions of people worldwide, creating substantial demand for respiratory treatment and monitoring technologies. At the same time, the growing prevalence of sleep-disordered breathing is supporting demand for PAP devices, while acute respiratory failure and critical-care requirements continue to support demand for ventilators and high-flow oxygen systems. The transition toward home-based care is creating additional demand for portable oxygen concentrators, home ventilators, PAP devices, nebulizers, and connected respiratory equipment. Furthermore, persistent gaps in access to medical oxygen, particularly in low- and middle-income countries, are encouraging investments in oxygen-generation, storage, distribution, and delivery infrastructure. WHO reports that fewer than half of health facilities in surveyed low- and middle-income countries have uninterrupted access to oxygen.
The respiratory care devices market is increasingly characterized by the adoption of non-invasive respiratory support, connected devices, portable oxygen systems, home-based therapy, and integrated patient monitoring. CPAP and BiPAP systems, high-flow nasal cannula technologies, home ventilators, oxygen concentrators, and connected PAP platforms are becoming increasingly important across chronic and acute respiratory care. Healthcare providers are also placing greater emphasis on devices that can provide therapy while reducing the need for hospital-based care. However, the market continues to face challenges related to device cost, reimbursement, maintenance, power requirements, patient adherence, and availability of trained healthcare personnel. Oxygen systems require reliable generation, distribution, storage, delivery, and monitoring infrastructure, which can be difficult to establish in resource-constrained settings. WHO identifies availability, affordability, quality, supply, maintenance, safety, and human-resource capacity as continuing challenges for medical oxygen systems.
The Asia Pacific respiratory care devices market is supported by expanding healthcare infrastructure, increasing healthcare expenditure, a large and aging patient population, and growing demand for diagnosis and treatment of respiratory diseases. China, Japan, India, South Korea, and Australia are developing hospital capacity, critical-care infrastructure, home healthcare services, and digital health capabilities, creating opportunities for respiratory device manufacturers. The region also faces significant requirements for medical oxygen infrastructure, particularly in emerging healthcare systems where reliable oxygen generation, distribution, and maintenance remain important challenges. WHO has highlighted the need for national oxygen scale-up planning and infrastructure development, including appropriate equipment selection, procurement, maintenance, and workforce training.
Increasing adoption of home-based respiratory therapy is creating additional opportunities across the region, particularly for oxygen concentrators, PAP devices, nebulizers, portable respiratory monitors, and home ventilatory support. In addition, the expansion of private hospitals, specialty respiratory centers, sleep laboratories, ambulatory care facilities, and home healthcare providers is supporting broader deployment of respiratory technologies.
Respiratory Care Devices Market Dynamics
Drivers: Increasing Prevalence of Chronic Respiratory Diseases and Demand for Long-Term Respiratory Support
The growing burden of COPD, asthma, sleep-disordered breathing, and other chronic respiratory conditions is a key factor driving demand for respiratory care devices. COPD requires long-term management and may involve oxygen therapy, nebulization, non-invasive ventilation, and respiratory monitoring, particularly among patients with advanced disease or recurrent exacerbations. The increasing diagnosis and treatment of sleep apnea is also supporting demand for PAP devices, while acute respiratory conditions and respiratory failure require ventilators, high-flow oxygen systems, and other respiratory-support technologies. WHO identifies COPD and asthma among the major chronic respiratory diseases and continues to highlight the substantial global burden associated with these conditions.
The growing need for respiratory support across both hospital and home settings is therefore expanding the addressable application base for manufacturers. In particular, the increasing use of long-term respiratory therapy outside hospitals is encouraging demand for portable and easier-to-use devices that can support continuous disease management.
Opportunities Expansion of Home-Based, Connected, and Portable Respiratory Care
A significant opportunity for the respiratory care devices market lies in the expansion of home-based and connected respiratory care. Portable oxygen concentrators, home ventilators, PAP systems, nebulizers, and connected respiratory monitors allow selected patients to receive continuing therapy outside traditional hospital environments. This trend can help healthcare systems manage chronic conditions while reducing dependence on repeated hospital visits for routine therapy management.
Connected devices also create opportunities for remote monitoring of treatment usage, adherence, respiratory parameters, and device performance. The combination of connected hardware, cloud platforms, remote patient monitoring, and digital clinical workflows can allow healthcare professionals to identify therapy-related issues and manage patients more proactively. This creates opportunities for manufacturers to move from standalone equipment toward integrated respiratory-care ecosystems.
Challenges: Regulatory Complexity, Data Requirements, and Integration Barriers
Despite technological development, respiratory care device manufacturers and healthcare providers continue to face challenges associated with affordability, infrastructure, maintenance, and appropriate device utilization. Oxygen therapy illustrates these challenges particularly clearly because effective treatment requires more than an oxygen-generating device; it requires reliable oxygen sources, distribution, regulation, delivery, monitoring, power supply, and trained personnel. WHO describes medical oxygen as a complex system requiring coordinated infrastructure and ongoing maintenance.
Patient adherence represents another challenge, particularly for long-term therapies such as CPAP and home respiratory support. Device comfort, mask fit, noise, portability, ease of operation, and patient education can influence sustained utilization. Healthcare providers also need trained personnel to select, configure, monitor, clean, and maintain respiratory equipment. These requirements can increase the total cost of ownership and complicate adoption in resource-constrained healthcare systems.
Technology and Market Insights
The respiratory care industry is moving toward non-invasive, portable, connected, and patient-centered respiratory management, expanding the role of respiratory devices across hospitals and home healthcare settings. Healthcare providers are increasingly seeking technologies that can provide effective respiratory support while improving patient mobility, monitoring therapy remotely, and reducing the operational burden associated with long-term respiratory management. Advances in sensors, connectivity, automated control, oxygen-generation technology, ventilation algorithms, and digital monitoring are supporting the development of increasingly integrated respiratory-care systems.
At the same time, respiratory care remains highly dependent on reliable physical infrastructure, trained healthcare personnel, appropriate maintenance, and patient adherence. Consequently, market development is being shaped not only by device innovation but also by healthcare-system capacity, reimbursement, clinical protocols, and access to oxygen and respiratory services.
Technology Scope and Products
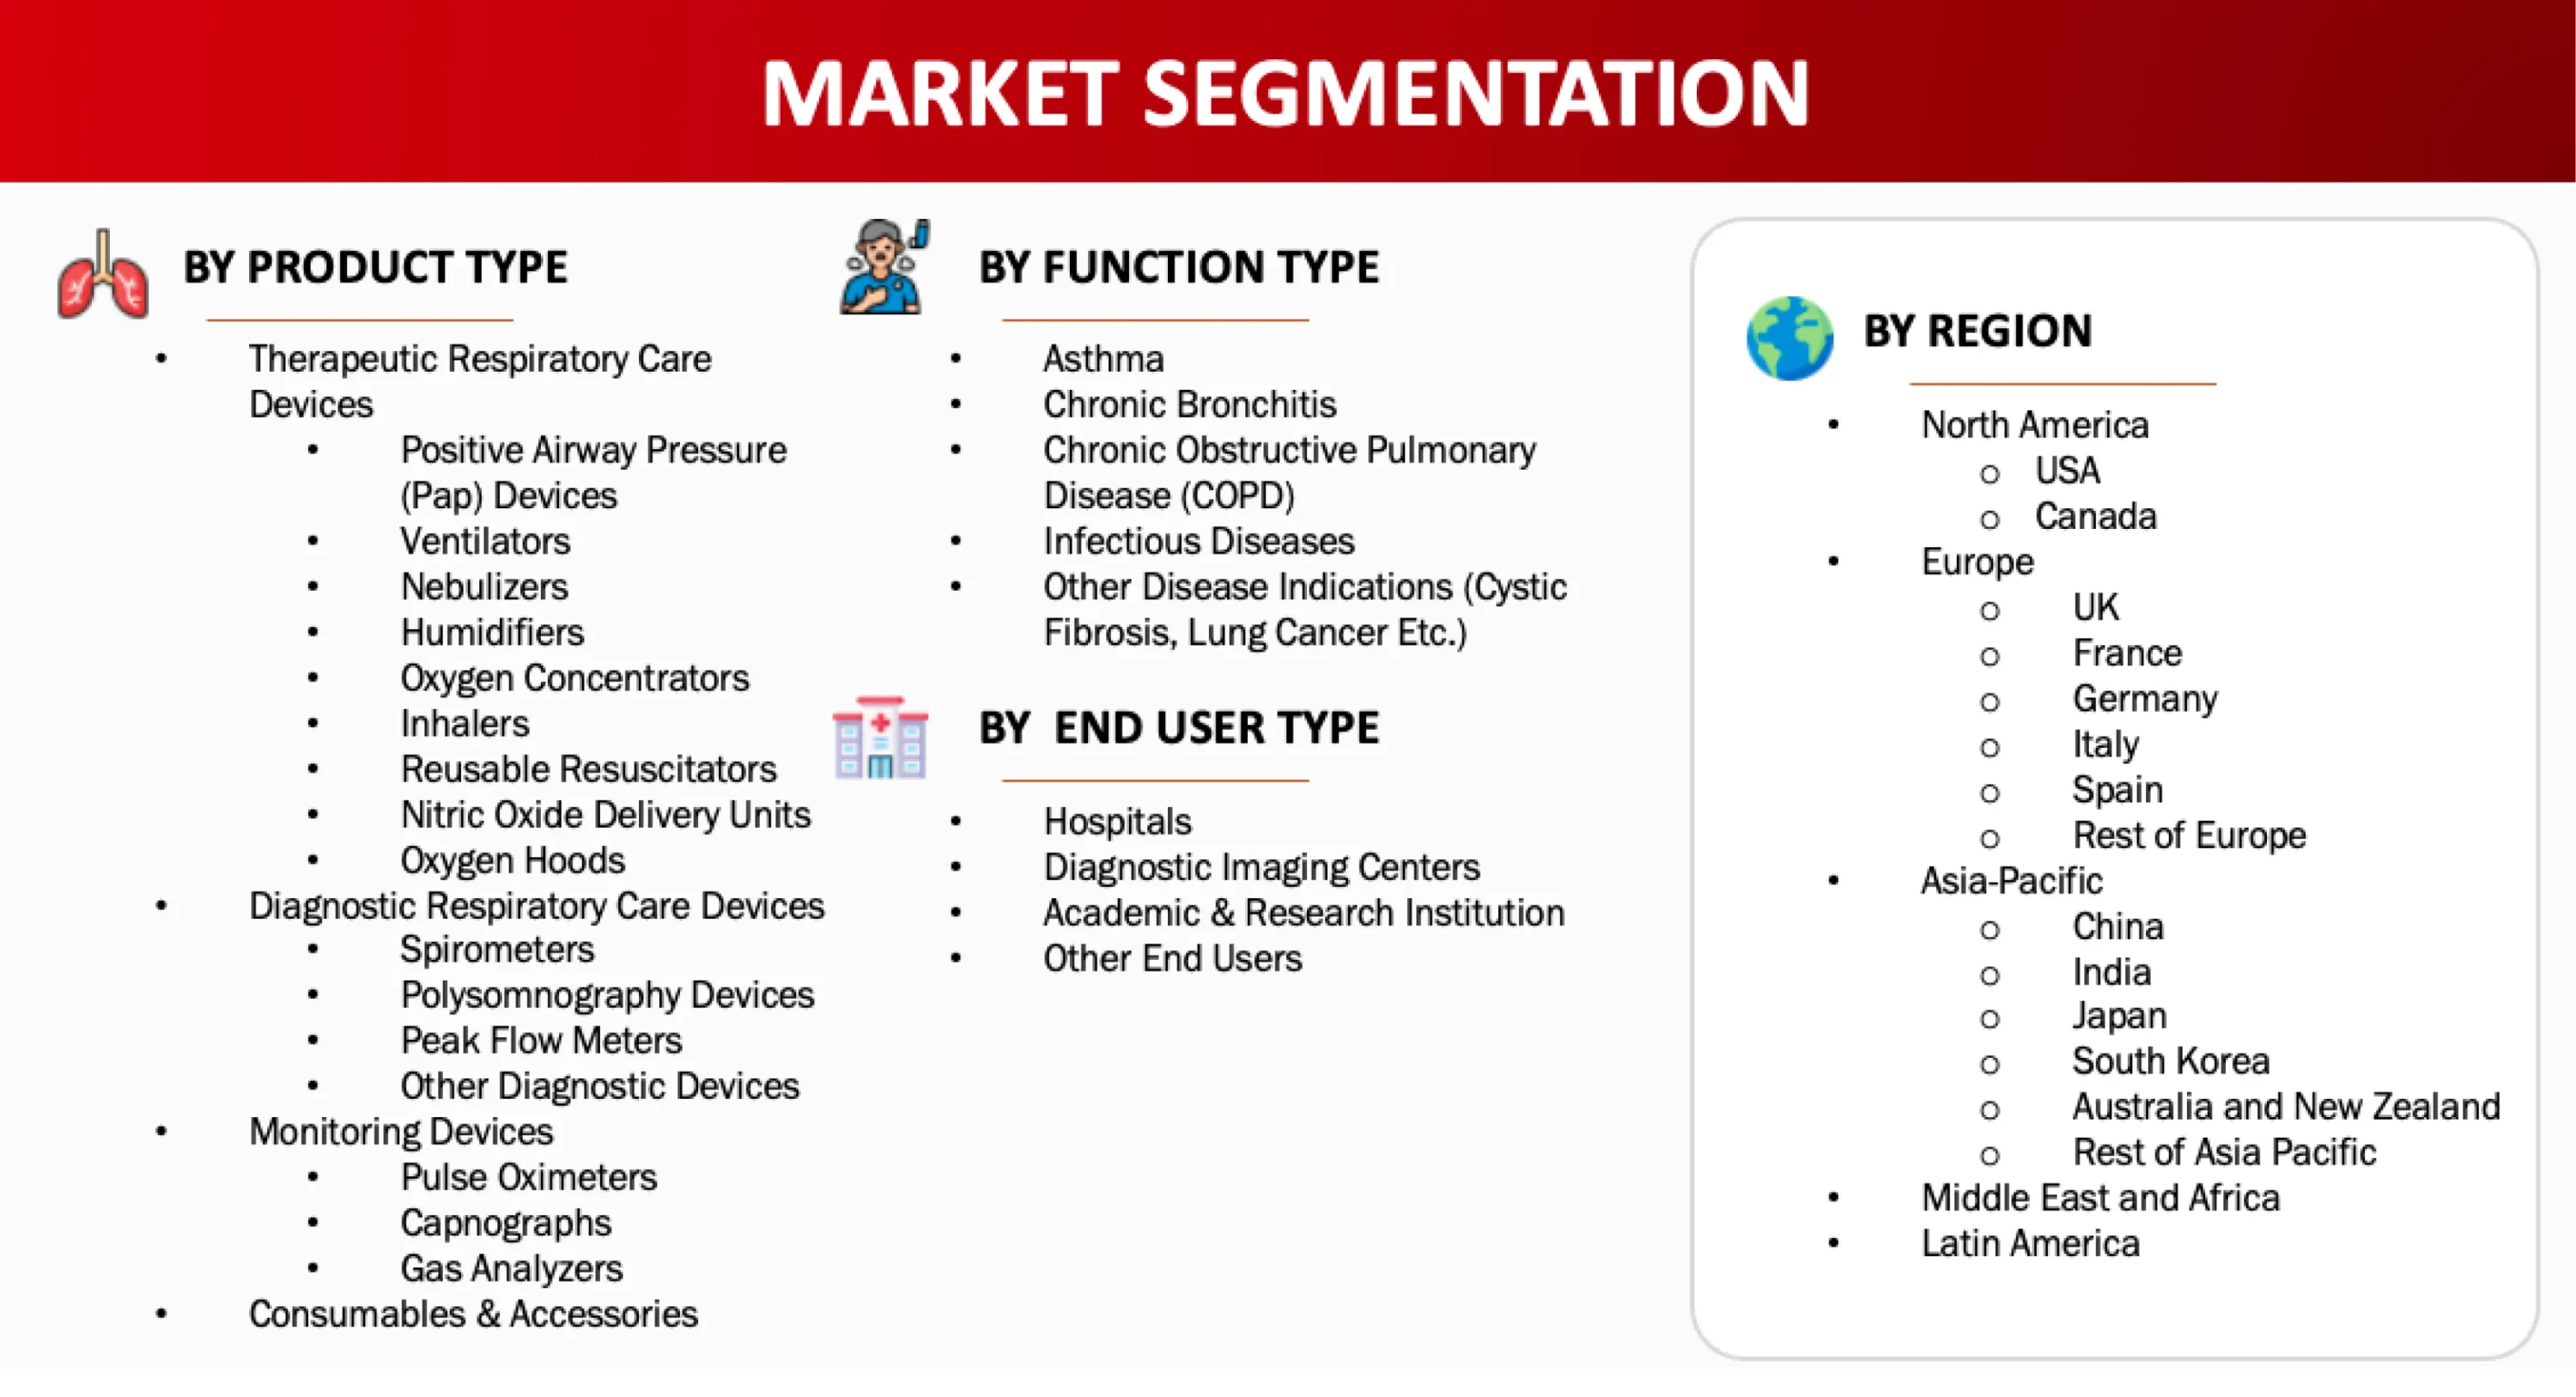
Respiratory Care Devices Market Segmentation
Want detailed insights from this report?
Industry Developments and Competitive Landscape
The competitive landscape in respiratory care devices is evolving through the convergence of ventilation, oxygen therapy, positive airway pressure, respiratory monitoring, connected healthcare, and home-based care. Large medical device companies are expanding their respiratory portfolios through innovations in mechanical ventilation, PAP therapy, oxygen delivery, airway management, and digital monitoring, while specialized manufacturers continue to develop focused solutions for sleep apnea, COPD, critical care, and home respiratory therapy. The competitive environment therefore includes diversified medical technology companies as well as specialized respiratory and sleep-care manufacturers. Competition is increasingly focused on device performance, portability, patient comfort, connectivity, remote monitoring, clinical usability, and integration across hospital and homecare settings.
Therapeutic respiratory care devices represented the largest product category within the respiratory care devices market in 2025. This category encompasses ventilators, CPAP and BiPAP devices, oxygen therapy equipment, nebulizers, and other technologies that directly support respiratory treatment. The broad clinical requirement for these devices across acute respiratory failure, COPD, sleep apnea, asthma, and other respiratory conditions supports their extensive utilization across hospitals, intensive care units, specialty clinics, and homecare settings.
-
Ventilators, positive airway pressure devices, oxygen therapy systems, and nebulizers constitute major components of therapeutic respiratory care and address both acute and chronic respiratory-management requirements.
-
The continuing burden of COPD and other chronic respiratory diseases supports demand for long-term oxygen therapy, non-invasive ventilation, nebulization, and respiratory support.
-
The increasing shift toward home-based respiratory treatment is creating demand for portable oxygen concentrators, home ventilators, PAP systems, and compact respiratory therapy devices.
-
Non-invasive respiratory support is becoming increasingly important across appropriate clinical settings, including CPAP, BiPAP, and high-flow nasal oxygen systems, as healthcare providers seek effective respiratory support while avoiding invasive procedures where clinically appropriate.
-
Increasing demand for portable and connected respiratory devices is encouraging manufacturers to integrate sensors, wireless connectivity, remote monitoring, and automated therapy-management capabilities into respiratory equipment.
Chronic obstructive pulmonary disease (COPD) represented the leading indication for respiratory care devices in 2025. COPD is a progressive respiratory condition that can require long-term management through oxygen therapy, ventilation, nebulization, respiratory monitoring, and other supportive technologies. The World Health Organization estimates that COPD caused approximately 3.4 million deaths globally in 2023, demonstrating the substantial underlying disease burden and continuing need for respiratory management.
-
COPD generates demand across multiple respiratory-device categories, including oxygen concentrators, ventilatory-support devices, nebulizers, non-invasive ventilation systems, and respiratory monitoring technologies.
-
The chronic nature of COPD creates sustained demand for long-term respiratory management, extending beyond acute hospital treatment.
-
Acute exacerbations of COPD can require hospitalization and respiratory support, supporting demand for hospital-based ventilation, oxygen therapy, and monitoring equipment.
-
Increasing population aging and continued exposure to risk factors such as tobacco smoke and air pollution contribute to the long-term COPD burden.
-
Sleep apnea and asthma are also important respiratory-care applications. PAP devices are particularly important in sleep apnea management, while nebulization and other respiratory-delivery technologies are widely used in asthma care.
North America represented the largest regional market for respiratory care devices in 2025, supported by developed healthcare infrastructure, high healthcare expenditure, established hospital and homecare networks, extensive respiratory-device utilization, and the presence of major medical technology manufacturers. The United States represents the dominant market within the region due to its large healthcare system, established reimbursement infrastructure, high utilization of respiratory technologies, and significant home healthcare sector.
-
The U.S. represents the majority of North American demand, supported by extensive use of ventilators, PAP systems, oxygen therapy equipment, nebulizers, and respiratory monitoring technologies across hospitals and homecare settings.
-
The country’s aging population and substantial burden of COPD, asthma, sleep apnea, and other chronic respiratory conditions continue to support respiratory-device utilization.
-
The established home medical equipment and home healthcare infrastructure supports the use of PAP devices, oxygen concentrators, home ventilators, and connected respiratory technologies outside hospitals.
-
North America also has a strong ecosystem of respiratory technology companies and healthcare providers, supporting product development, clinical adoption, and commercialization of advanced respiratory devices.
-
Asia Pacific is expected to experience faster market expansion, supported by increasing healthcare expenditure, expansion of hospital and critical-care infrastructure, rising respiratory disease burden, increasing access to medical oxygen, and growing adoption of home-based respiratory care. The World Health Organization has also highlighted the need to expand oxygen access and strengthen oxygen systems across low- and middle-income countries.
What This Report Covers-
This report provides a comprehensive analysis of the respiratory care devices market, offering insights into key trends, growth drivers, challenges, and future opportunities. It is designed to support strategic decision-making through a combination of quantitative data and qualitative analysis.
Specifically, the report covers:

Market Overview & Definition:
Overview of the market scope, structure, and key terminology

Market Size & Forecast:
Historical data and future projections across key segments and regions

Key Market Trends:
Insights into emerging trends, technological advancements, and evolving demand patterns

Drivers, Restraints & Opportunities:
Analysis of key factors influencing respiratory care devices market growth

Competitive Landscape:
Overview of major players, their strategies, and recent developments

Detailed Patent Analysis:
This includes, top assignees, geography focus of top assignees, legal status, technology evolution, key patents and patent trends and innovations

Segmentation Analysis:
Breakdown by product type, by indication type, by end users type, and region

Regional Insights:
Key regional trends and growth opportunities

Future Outlook:
Strategic insights and future market direction
Research Methodology
The study of the Respiratory Care Devices market is based on a combination of primary and secondary research methodologies, supported by data validation and analytical modelling to ensure accuracy and reliability.
Market Definition: Respiratory Care Devices Market
Respiratory care devices refer to medical devices and equipment used for the prevention, diagnosis, monitoring, treatment, and management of respiratory disorders and conditions affecting the lungs and airways. These devices are designed to support respiratory function, deliver therapeutic gases or medications, monitor respiratory parameters, and assist patients with breathing across acute, chronic, and emergency care settings. The market includes devices used for conditions such as chronic obstructive pulmonary disease (COPD), asthma, sleep apnea, respiratory infections, respiratory failure, and other pulmonary disorders.
Key examples of respiratory care devices include ventilators, continuous positive airway pressure (CPAP) and bilevel positive airway pressure (BiPAP) devices, oxygen concentrators, oxygen therapy equipment, nebulizers, inhalation devices, respiratory monitoring devices, spirometers, peak flow meters, airway clearance devices, and related respiratory therapy equipment. In addition, high-flow oxygen therapy systems, humidifiers, respiratory gas monitoring systems, suction devices, and selected consumable components used with respiratory care equipment are included within relevant product categories. Across healthcare environments, including hospitals, intensive care units, emergency departments, diagnostic centers, sleep laboratories, specialty clinics, home healthcare settings, and ambulatory care facilities, respiratory care devices are used to improve oxygenation and ventilation, support airway management, monitor respiratory function, deliver medications, and enable long-term respiratory disease management.
Key Stakeholders
The respiratory care devices market involves a broad ecosystem of stakeholders:
- Respiratory Care Device Manufacturers (Ventilators, CPAP/BiPAP devices, oxygen concentrators, nebulizers, respiratory monitors, spirometers, and airway clearance devices)
- Medical Device & Healthcare Technology Companies (Respiratory therapy technologies, connected devices, digital monitoring solutions, and integrated respiratory care platforms)
- Oxygen Therapy Equipment Providers (Oxygen concentrators, oxygen delivery systems, liquid oxygen equipment, cylinders, and related accessories)
- Ventilation & Airway Management Providers (Invasive and non-invasive ventilation systems, high-flow oxygen systems, airway clearance equipment, and respiratory support technologies)
- Pharmaceutical & Drug Delivery Companies (Inhaled medications, nebulized therapies, respiratory drug delivery systems, and combination products)
- Healthcare Providers (Hospitals, intensive care units, emergency departments, specialty clinics, outpatient facilities, sleep centers, and home healthcare providers)
- Respiratory Therapists, Pulmonologists & Clinical Specialists (Respiratory assessment, device selection, treatment planning, patient monitoring, and evaluation of therapeutic outcomes)
- Patients and Caregivers (respiratory disease management, home-based therapy, oxygen therapy, sleep apnea treatment, and long-term respiratory monitoring)
- Home Healthcare & Durable Medical Equipment (DME) Providers (Device distribution, installation, maintenance, patient training, monitoring, and home respiratory therapy services)
- Diagnostic & Sleep Testing Centers (Pulmonary function testing, sleep apnea diagnosis, respiratory monitoring, and evaluation of respiratory conditions)
- Medical Imaging & Diagnostic Technology Providers (Pulmonary diagnostic technologies and complementary systems used in respiratory disease assessment)
- Clinical Research Organizations (CROs) (Clinical studies, device validation, respiratory therapy research, patient outcome assessment, and regulatory support)
- Medical Imaging & Respiratory Research Institutions (Respiratory research, device development, clinical validation, pulmonary function studies, and development of advanced respiratory technologies)
- Regulatory & Standards Organizations (Medical device approvals, respiratory equipment safety, performance requirements, quality systems, and regulatory compliance)
- Testing, Inspection & Certification (TIC) Companies (Device testing, electrical and mechanical safety assessment, performance validation, quality assurance, and regulatory certification)
- Healthcare Technology Integrators & Channel Partners (Device implementation, hospital integration, distribution, technical support, equipment servicing, and respiratory care workflow deployment)
- Payers & Reimbursement Organizations (Coverage policies, reimbursement frameworks, medical necessity assessment, and payment for respiratory care equipment and services)
- Investors (Venture capital firms, private equity investors, medical technology companies, and strategic healthcare investors)
Key Objectives of the Study
- To define, describe, analyze, segment, and forecast the respiratory care devices by product type, by indication type, by end users type.
- To describe and forecast the market for four key regions: North America, Europe, Asia Pacific, and Rest of the World
- To provide detailed information regarding key drivers, restraints, opportunities, and challenges influencing market growth
- To strategically analyze the micro indicators with respect to individual growth trends, prospects, and contributions to the overall market size
- To analyze opportunities for stakeholders in the respiratory care devices industry and emphasize on competitive landscape of the market
- To develop competitive benchmarking of the key market players based on technology specifications and end user
- To strategically profile key players and comprehensively analyze their product portfolio offerings, and core competencies
- To analyze competitive developments, such as launches and approvals, agreements, mergers and acquisitions, partnerships, joint ventures, investments and expansions, and collaborations, respiratory care devices domain
Need deeper insights on this market?
Get full report access with detailed forecasts, competitive analysis, and segmentation.
Research Approach
This research employs a systematic approach by using primary research along with secondary research to achieve full coverage and accuracy of information about the respiratory care devices sector. Through this approach, the current market trends in terms of consumer behaviour, technological developments, and competitive environment can be analysed thoroughly.
Secondary Research
Secondary research involves the collection of data from reliable sources such as industry databases, company annual reports, investor presentations, and regulatory filings. This process helps in understanding market trends, identifying key players, and gathering technical and commercial insights.
A comprehensive database of leading companies and market participants is developed through secondary research to support further analysis.
Primary Research
Primary research is conducted to validate findings from secondary research and to gain deeper insights into market dynamics. Interviews are carried out with industry stakeholders across both demand and supply sides, including executives such as CXOs, Vice Presidents, and Directors from business development, marketing, and product teams.
Data is collected through structured questionnaires, email interactions, and telephonic interviews across key regions including North America, Europe, Asia Pacific, and Rest of the World.
Market Size Estimation
Market size estimation is performed using both top-down and bottom-up approaches. Key market players are identified, and their revenues are analysed to estimate the overall market size.
The market is further segmented based on:
- Product and service mapping across regions
- Adoption patterns across key application segments
- Insights gathered through primary and secondary research
Data Validation and Research Design
After estimating the overall market size, the data is validated using triangulation methods and market breakdown techniques to ensure accuracy and consistency. Both demand-side and supply-side factors are considered to refine the analysis.
The final data is validated through multiple sources to ensure reliability and to provide accurate insights across all market segments and regions.
Assumptions of the Study
The analysis of the respiratory care devices market is based on the following key assumptions:
- Trends in the industry are drawn from historical data and current information within the sector
- The future outlook is underpinned by constant economic conditions in the absence of shocks to the market
- The rate of adoption for respiratory care devices will rise steadily in all important regions
- The income statement and market share figures are estimated using available information from the industry and publicly available data
- The exchange rate and price trends will not be greatly affected during the forecast period
Scope and Limitations
Scope of the Study
This report offers an exhaustive overview of the international respiratory care devices market and includes the following components:
- Summary of market size, growth trends, and projections
- Carefully segmented market based on products, platform, sample, end users, by mode of acquiring and geography
- Discussion of primary factors influencing the market
- Competitor analysis
- Insights into regional and national market performance
Limitations of the Study
Despite the best efforts being made to keep the results accurate, the study does suffer from some limitations:
- It has been done using both primary and secondary data that come with their own constraints
- Rapid developments in technology might affect the future course of market dynamics
- Some figures are only approximations due to lack of public disclosure
- The report is not an insurance against any disruptions in macroeconomics and geopolitics
- Future forecasts are indicative and subject to change due to altered industry dynamics
Data Triangulation and Market Breakdown
Data triangulation involved the combination of primary research, secondary research, and the Wissen Research analysis. Once the data points were sourced from the secondary market research, we sanitized the data points to make the market sizing and growth forecast more accurate by developing our own assumptions based on the inputs and insights we gather through the primary interviews with the industry experts. Once the data was thoroughly validated through primary interviews from both, demand and supply side of the market, our team of analyst and other team members involved finalized the market sizing and growth forecast.
Data Triangulation Methodology
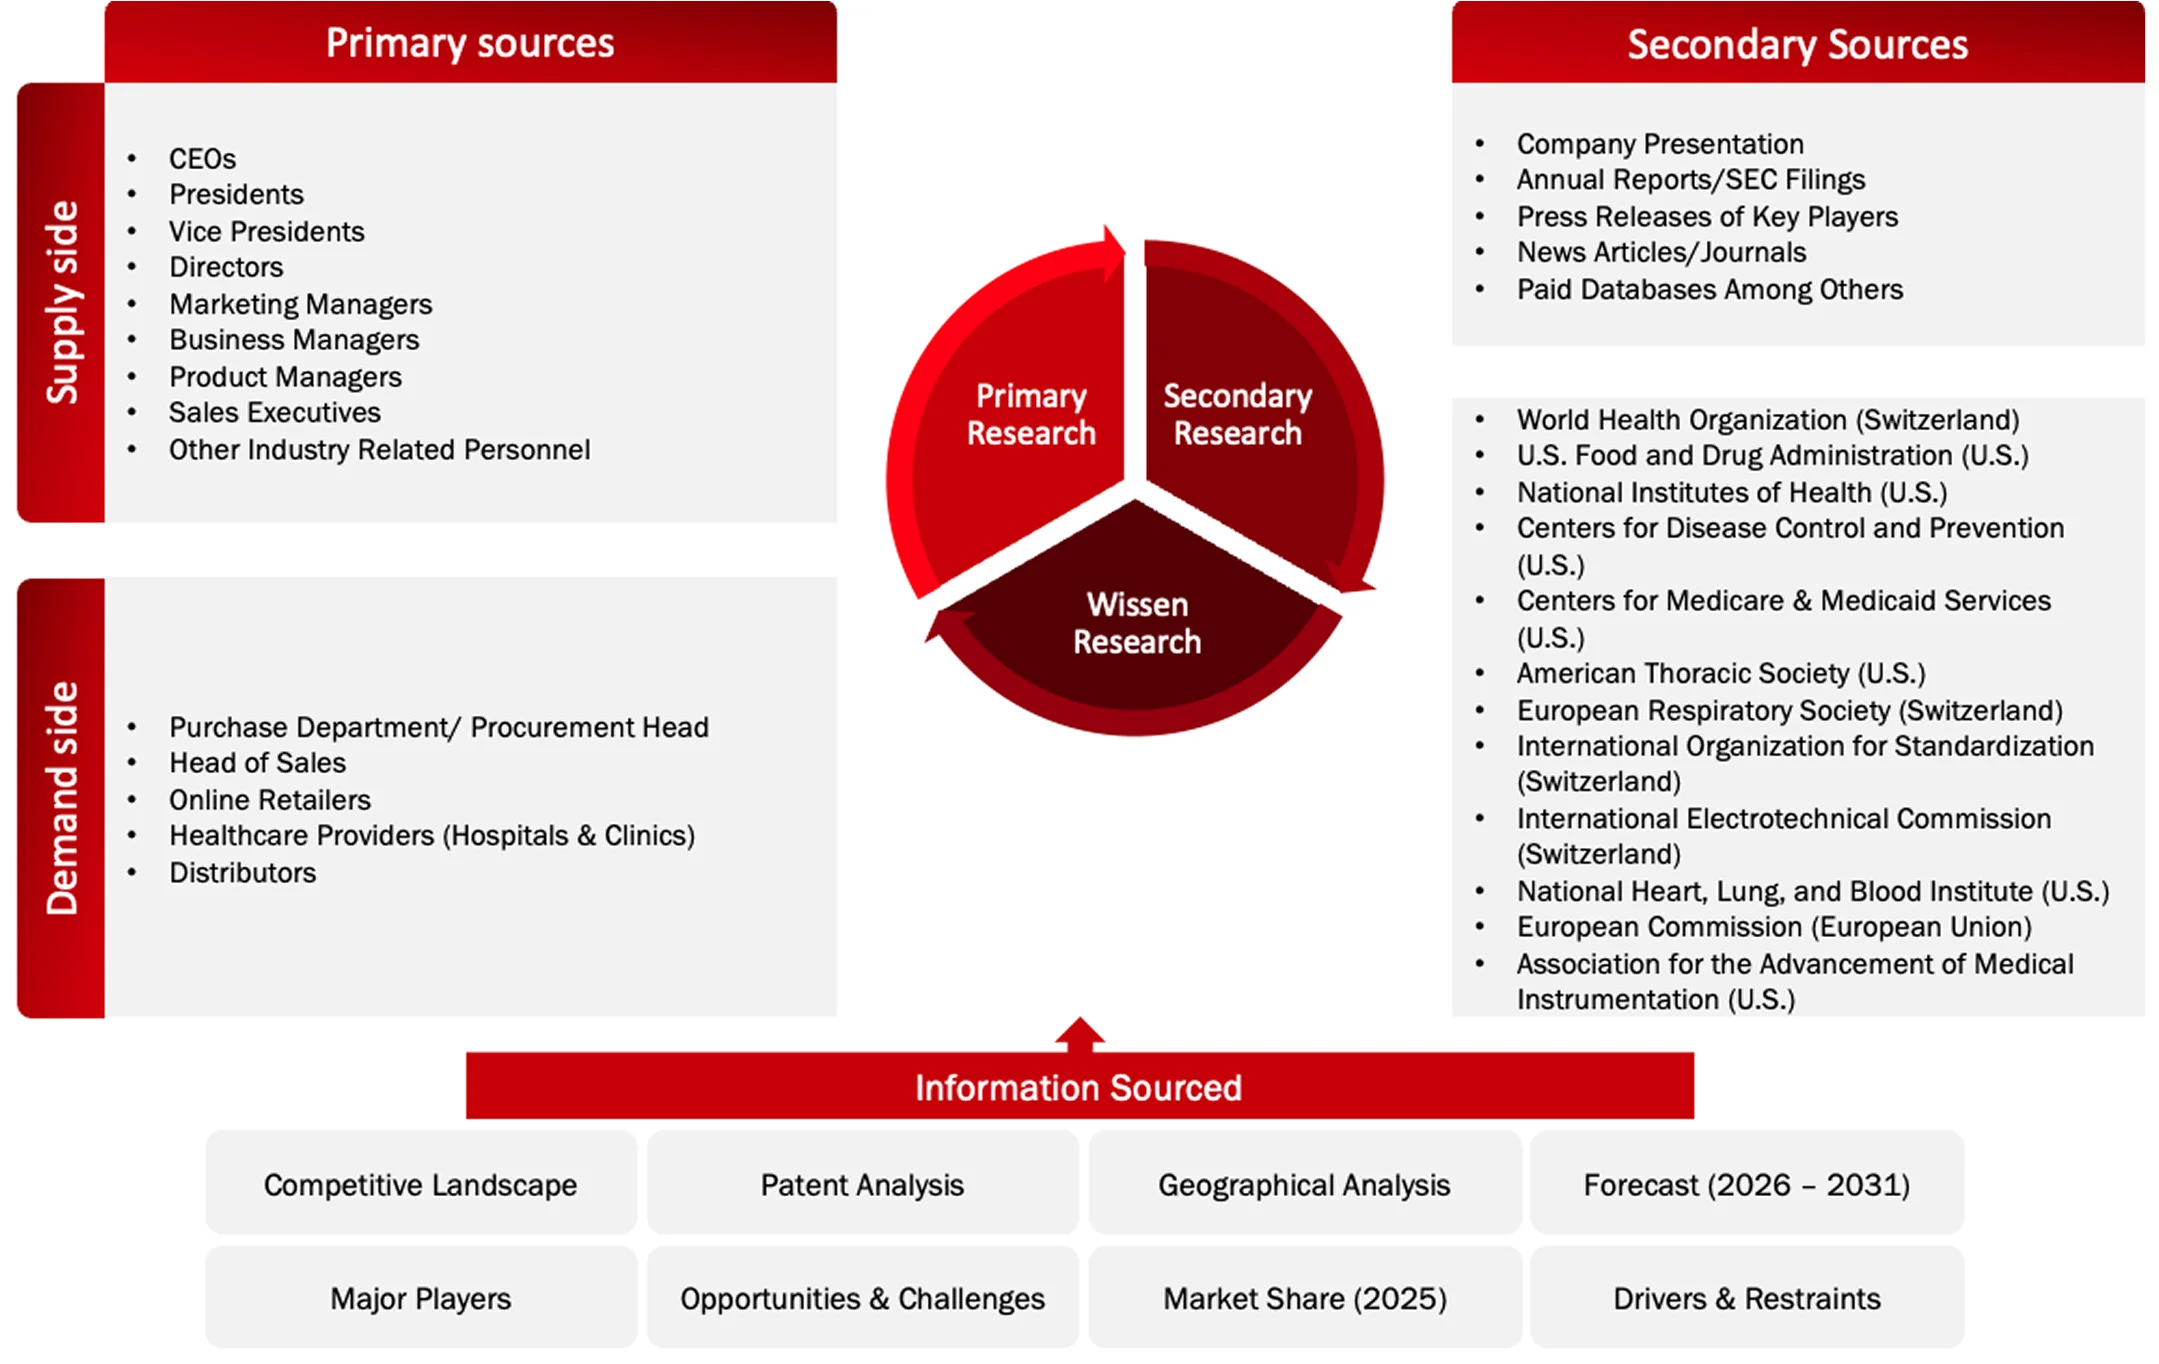
Sources: U.S. Food and Drug Administration, National Institutes of Health, National Cancer Institute, Centers for Medicare & Medicaid Services, Radiological Society of North America, American College of Radiology, Society for Imaging Informatics in Medicine, European Society of Radiology, European Association of Nuclear Medicine, World Health Organization, International Organization for Standardization, International Electrotechnical Commission, Company Websites, Press Releases, Annual Reports, Paid Data Sources, and Wissen Research Analysis.
Years Framework
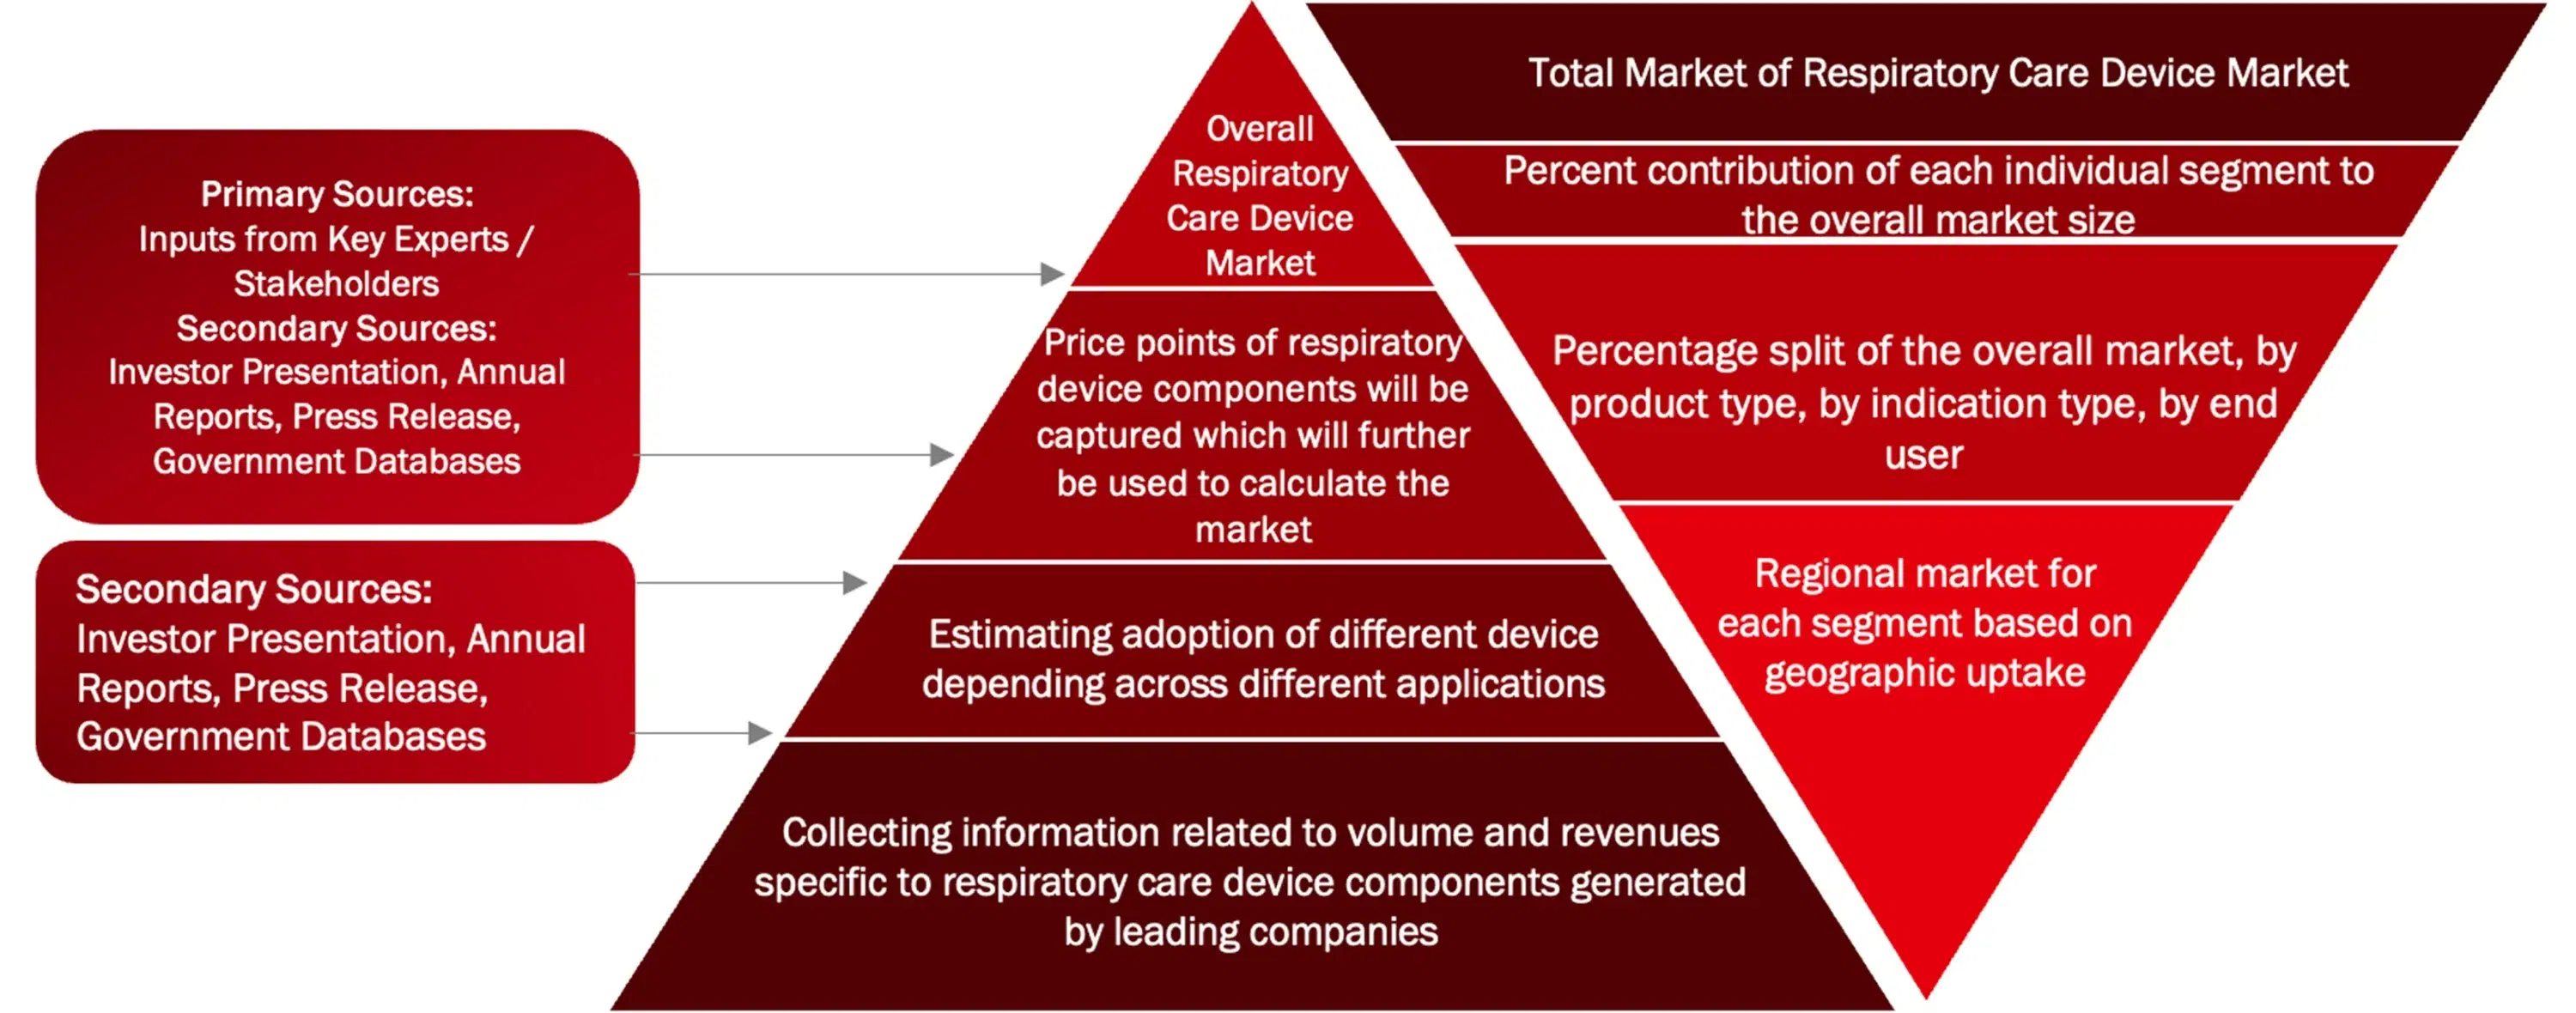
Bottom-Up Approach (Demand Side) And Top-Down Approach (Supply Side)
Bottom-Up Approach (Demand-Side Approach):
Determining the market size through the consolidation of demand among end-users, sectors, and geographic areas, which are calculated according to real-world demand conditions.
Top-Down Approach (Supply-Side Approach):
Calculating the market size through revenue and performance of the industry and its important companies, allocating the market size among various sectors.
Want detailed insights from this report?
Buy this Report
Choose the option that best fits your needs